










TechD first-half revenue more than doubles as margin normalises to 34%
Key highlights
- TechD reported H1 FY27 revenue from operations of Rs 39.05 crore, up 115% year on year.
- H1 FY27 EBITDA was Rs 13.21 crore and profit after tax was Rs 9.67 crore.
- TechD reported a 34% H1 FY27 EBITDA margin, versus 49% in H1 FY26 and 33% in H2 FY26.
- TechD reported a Rs 70 crore order book at 30 September 2026 and a sales funnel above Rs 150 crore.
powered by IRIS
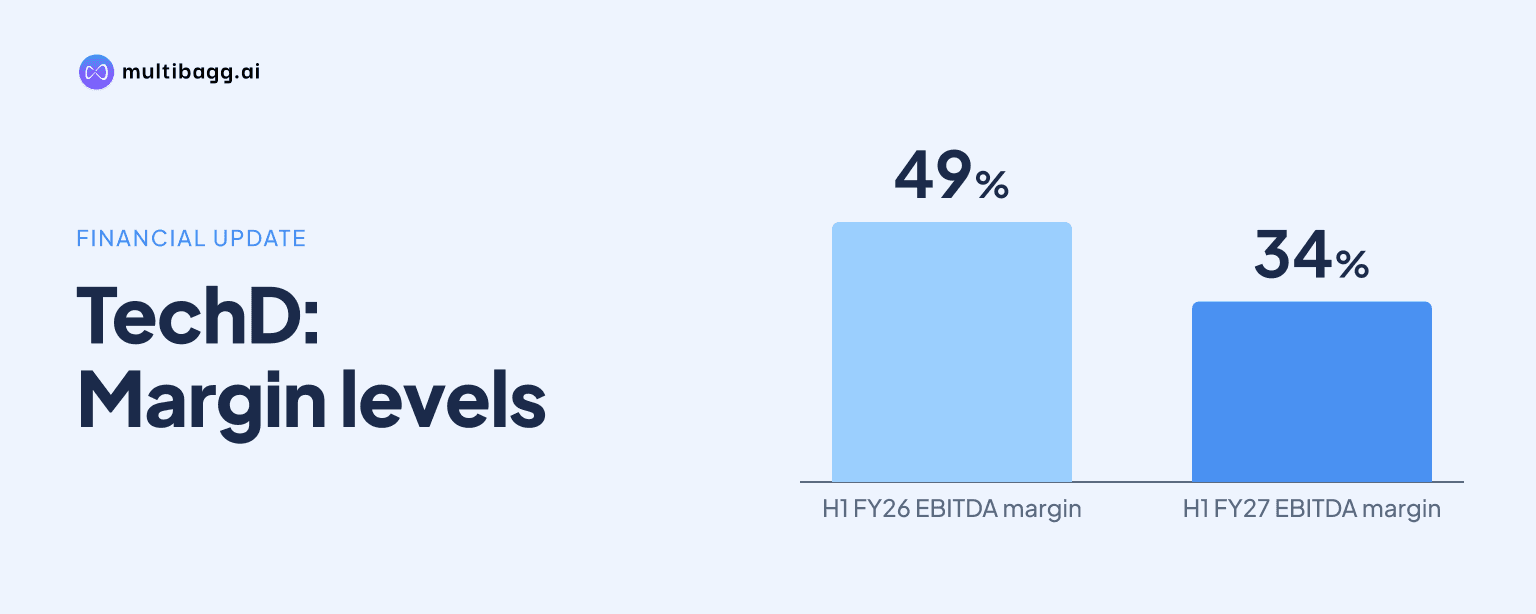
TechD Cybersecurity Limited reported first-half financial year 2027 (H1 FY27) revenue from operations of Rs 39.05 crore, up 115% year on year, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin normalised to 34% from 49% in H1 FY26 as it spread original equipment manufacturer (OEM) costs and recurring-customer revenue more evenly through the year.
Know TechD Cybersecurity inside out
Results, valuation, peers and who's buying, in one view.
How did TechD perform in H1 FY27?
TechD delivered higher revenue, EBITDA and profit after tax in H1 FY27 than in H1 FY26. Revenue from operations rose to Rs 39.05 crore in the April-September 2026 half year from Rs 18.18 crore a year earlier, an increase of 115%. The company described this as 2.1 times growth in revenue, while the H1 FY27 revenue level also exceeded the Rs 33.63 crore reported for H2 FY26.
EBITDA increased 47% year on year to Rs 13.21 crore from Rs 8.99 crore. Profit after tax rose 52% to Rs 9.67 crore from Rs 6.37 crore. TechD therefore reported faster growth in revenue than in EBITDA and profit after tax during H1 FY27, consistent with the lower reported EBITDA-margin profile described by management.
TechD’s H1 FY27 figures are consolidated figures, according to the presentation. The company executed more than 920 orders and served 690 customers in the half year, including 230 new logos. Its reported customer-renewal rate was 98%, while managed security operations centre (SOC) customers numbered 250 in the H1-at-a-glance section.
Why did TechD’s EBITDA margin fall to 34%?
TechD’s EBITDA margin fell because management is deliberately moving revenue and costs into a steadier quarterly pattern. The company said its historical model produced lower first-half revenue and higher first-half margin, with H1 FY26 revenue of Rs 18.18 crore and an EBITDA margin of 49%. That first-half pattern was followed by higher H2 FY26 revenue of Rs 33.63 crore but a lower EBITDA margin of 33%, owing to OEM costs and other costs.
TechD reported a 34% EBITDA margin on H1 FY27 revenue of Rs 39.05 crore, describing the result as revenue ahead of H2 FY26 with margin steady. This changes the relevant comparison from a simple year-on-year margin movement to the company’s stated effort to reduce the first-half versus second-half swing. The presentation does not provide a full-year FY27 margin target or a quarterly revenue schedule.
Management said it is normalising OEM costs by spreading them more evenly through the year, restructuring customer contracts so recurring customers contribute evenly every quarter, and aligning the cost base to a steadier revenue profile. These measures are tied to TechD’s stated shift from a seasonal business to a steady, recurring one, rather than to a disclosed change in the H1 FY27 EBITDA amount of Rs 13.21 crore.
Got a follow-up? Ask IRIS
What is driving TechD’s revenue mix and recurring model?
TechD’s H1 FY27 revenue was 76% domestic and 24% international, while its customer base spanned regulated, small and medium business (SMB), and enterprise clients. Of the 690 customers served in H1, 300, or 43%, were regulated customers such as banks, non-banking financial companies, brokers, insurers and International Financial Services Centres Authority clients. Another 220 customers, or 32%, were in the SMB segment, and 170, or 25%, were enterprise customers.
TechD identifies three-year contracts, 24x7 managed SOC services, staff augmentation, multi-platform SOC services, artificial-intelligence red teaming and global capability centre build-outs as growth drivers. Its multi-platform SOC offering includes Securonix, Seceon and CrowdStrike, according to the presentation. The recurring-revenue normalisation plan is therefore connected to managed-service and contract-based work, although the presentation does not assign revenue amounts to each driver.
The company describes managed security service provider (MSSP) revenue and product revenue as its two growth engines. Its product revenue includes the TechD One platform and products, and it reported orders across Human Trust, Darkvector and Provenance AI. In H1 FY27, TechD also cited a managed SOC engagement for Alef Education in the United Arab Emirates and Fluent Commerce in Australia, alongside an International Financial Services Centres Authority audit for ANZ Banking Group in GIFT City.
What do TechD’s order book and pipeline indicate?
TechD reported an order book of Rs 70 crore as of 30 September 2026 and a sales funnel of more than Rs 150 crore across government and international projects. The order book is a stated point-in-time figure, while the funnel is a broader sales-stage measure; the presentation does not provide expected conversion rates, delivery dates, or the portion of either figure that will be recognised in FY27 revenue.
The company also said average revenue ticket size per order is increasing, without disclosing an average order value for H1 FY27 or an earlier comparison. More than 920 orders were executed during the half year, which provides the volume context for that statement, but TechD does not break out the Rs 39.05 crore of H1 revenue by order size, country or individual service line.
TechD’s customer activity includes wins or work associated with HDFC Life, Aditya Birla Capital, ICICI Securities, UltraTech Cement, 1Pay and Alef Education. It also cited new H1 customer acquisition in Mauritius, government work involving the Department of Atomic Energy and SSB, and expansion into market infrastructure institutions through Mills. These disclosed examples support the company’s stated government, international and regulated-sector pipeline focus, but do not quantify the revenue attached to each account.
Conclusion
TechD’s H1 FY27 result combines Rs 39.05 crore of revenue, 115% year-on-year growth and Rs 13.21 crore of EBITDA with a reported 34% margin. Compared with H1 FY26’s Rs 18.18 crore revenue and 49% margin, the company has reported substantially more first-half revenue while accepting a margin profile closer to H2 FY26’s 33% on Rs 33.63 crore of revenue.
The next results will show whether TechD’s plan to spread OEM costs and recurring-customer revenue evenly continues to reduce the historical H1-H2 contrast. Investors can also watch execution against the Rs 70 crore order book at 30 September 2026 and the more than Rs 150 crore funnel, for which management has not disclosed conversion timing or rates.