










Technocraft Ventures Limited approves Q2 FY27 results after review
Key highlights
- Technocraft Ventures approved unaudited Q2 FY27 and H1 FY27 results for the period ended September 30, 2026.
- The Board approved the results on November 14, 2026.
- The consolidated review included a 26% interest in the TESPL-LRS-TCPL JV and remained unmodified.
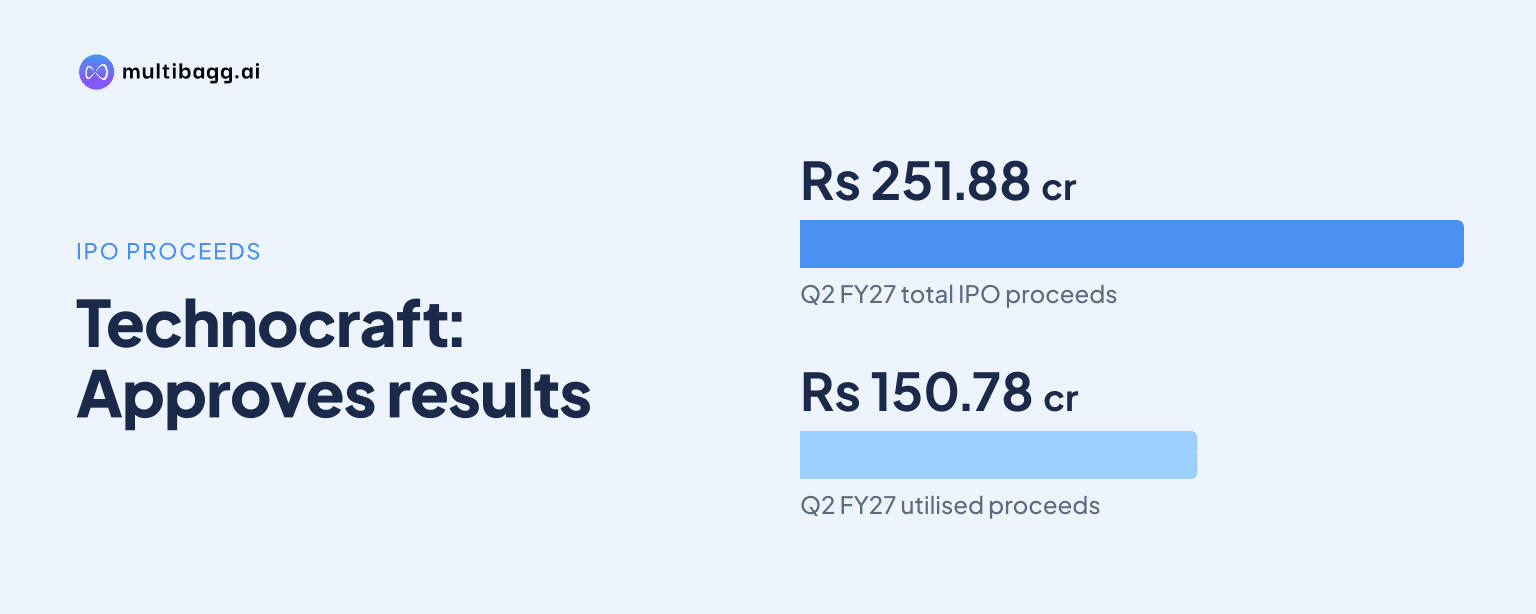
- Technocraft Ventures reported total IPO proceeds of ₹251.88 crore, with ₹150.78 crore stated as utilised.
powered by IRIS
Technocraft Ventures Limited approved unaudited standalone and consolidated results for Q2 FY27 and the half year ended September 30, 2026, with statutory auditors reporting no material misstatement in their limited reviews. The consolidated review remained unmodified and included the company’s 26% interest in the TESPL-LRS-TCPL JV.
Know Technocraft Ventures inside out
Results, valuation, peers and who's buying, in one view.
What did Technocraft Ventures approve for Q2 FY27?
Technocraft Ventures approved its standalone and consolidated unaudited financial results for the quarter and half year ended September 30, 2026. The Board of Directors took the decision at its meeting on November 14, 2026, following an earlier intimation that the meeting would consider the quarterly and half-yearly statements.
The company said the approved results and the accompanying Independent Auditor’s Review Report were submitted to the stock exchanges and made available on its website. However, the supplied filing text does not contain legible revenue, operating margin, or net profit figures for Q2 FY27 or the first half of FY27. Therefore, the approval establishes the reporting event, but does not permit a numerical assessment of the latest quarter’s performance from the available information.
The results cover both the parent company’s standalone position and the group’s consolidated position. This distinction is relevant because consolidated reporting includes the impact of entities or interests that are not reflected in the standalone statements in the same manner.
What did the auditors say about the financial statements?
The statutory auditor, Rishi Kapoor & Company, reported that its limited review did not identify anything causing it to believe that the unaudited standalone and consolidated financial statements contained a material misstatement or omitted disclosures required under applicable requirements. The auditor conducted the review under Standard on Review Engagements 2410.
A limited review is different from a full statutory audit. It is designed to provide a conclusion based primarily on inquiries and analytical procedures rather than the broader testing generally carried out in an audit. In this case, the conclusion was unmodified, meaning the auditor did not qualify its review conclusion based on the work performed.
For the consolidated statements, the review also considered financial information relating to the TESPL-LRS-TCPL JV. The source states that this associate or partnership interest was reviewed by another auditor, and the group auditor’s conclusion was not modified because of that component’s inclusion.
How does the 26% JV interest affect consolidated reporting?
Technocraft Ventures’ consolidated results include its 26% interest in the TESPL-LRS-TCPL JV. The availability of consolidated statements gives investors a view that incorporates the company’s interest in the JV alongside the parent company’s own financial results.
The supplied information does not provide the associate’s revenue, profit, asset, or liability contribution for Q2 FY27. It also does not show how much of the consolidated result was attributable to the JV. Investors therefore cannot quantify the associate’s current-period effect from the disclosed text, although its inclusion and separate review are explicitly confirmed.
The consolidated limited-review conclusion remained unmodified despite reliance on another auditor’s review of the JV-related financial information. That indicates the group auditor did not report a modification to its conclusion arising from the component information described in the source.
Got a follow-up? Ask IRIS
What earlier financial information is available for comparison?
The latest legible operating figures in the supplied material relate to Q1 FY27, ended June 30, 2026, rather than Q2 FY27. Technocraft Ventures reported operating income of ₹92.70 crore, EBITDA of ₹18.49 crore, profit before tax of ₹14.47 crore, and profit after tax of ₹10.70 crore for that quarter.
Against Q1 FY26, the company’s operating income was reported to have risen 2.24% from ₹90.67 crore. EBITDA increased 16.36% from ₹15.89 crore, while profit before tax rose 15.76% from ₹12.50 crore. Profit after tax was reported at ₹10.70 crore compared with ₹9.34 crore in the corresponding quarter of the prior year, an increase of 14.56%.
The source also presents a sequential comparison in which Q1 FY27 revenue of ₹92.70 crore was 33.58% below ₹139.57 crore, and net profit of ₹10.69 crore was 54.63% below ₹23.56 crore. These sequential figures relate to the quarter before the newly approved Q2 results and should not be treated as Q2 FY27 performance. Since Q2 figures are not legible in the available text, a quarter-on-quarter update cannot be calculated.
Why does the Q2 FY27 approval matter to investors?
The Board approval completes an important reporting step for Technocraft Ventures’ second-quarter and first-half FY27 financial statements. For investors, the unmodified limited-review conclusion provides assurance that the statutory auditors did not identify a matter requiring a modified conclusion on the statements reviewed.
The filing also keeps focus on the company’s use of IPO proceeds. The source states that total IPO proceeds were ₹251.88 crore, of which ₹150.78 crore had been utilised as of the reporting date. It further states that ₹50.75 crore remained unutilised and was temporarily invested in fixed deposits. The supplied text does not provide a detailed break-up of expenditure categories or a reconciliation of all proceeds beyond these stated amounts.
Technocraft Ventures listed on August 14, 2026, according to the supplied material. As a newly listed company, its periodic disclosures are particularly relevant for establishing a public reporting record. The current announcement confirms regulatory submission of the Q2 and half-yearly results, but investors would need the full financial statements to assess margins, cash flow, order activity, leverage, and the contribution from the JV.
Conclusion
Technocraft Ventures approved its Q2 FY27 and first-half FY27 unaudited standalone and consolidated financial results on November 14, 2026. The most important disclosed finding is the unmodified limited-review conclusion, including the consolidation of the company’s 26% interest in the TESPL-LRS-TCPL JV, while the available filing text does not show legible Q2 revenue or profit figures.
The next item to watch is the detailed financial-results document submitted to the exchanges and hosted on the company website. Investors will need the full statement to review Q2 revenue, profitability, half-year trends, cash deployment from IPO proceeds, and the financial contribution of the TESPL-LRS-TCPL JV.