










Tiaan Consumer enters CIRP over Rs 106.6127414 crore default
Key highlights
- The NCLT admitted Tiaan Consumer into CIRP on November 17, 2026.
- The petition claimed Rs 106.6127414 crore, including interest calculated through August 31, 2026.
- The underlying principal loan was Rs 90 crore, disbursed in December 2024.
- Shri Niwas Leasing and Finance Limited must deposit Rs 5 lakh for initial CIRP costs within seven days.
powered by IRIS
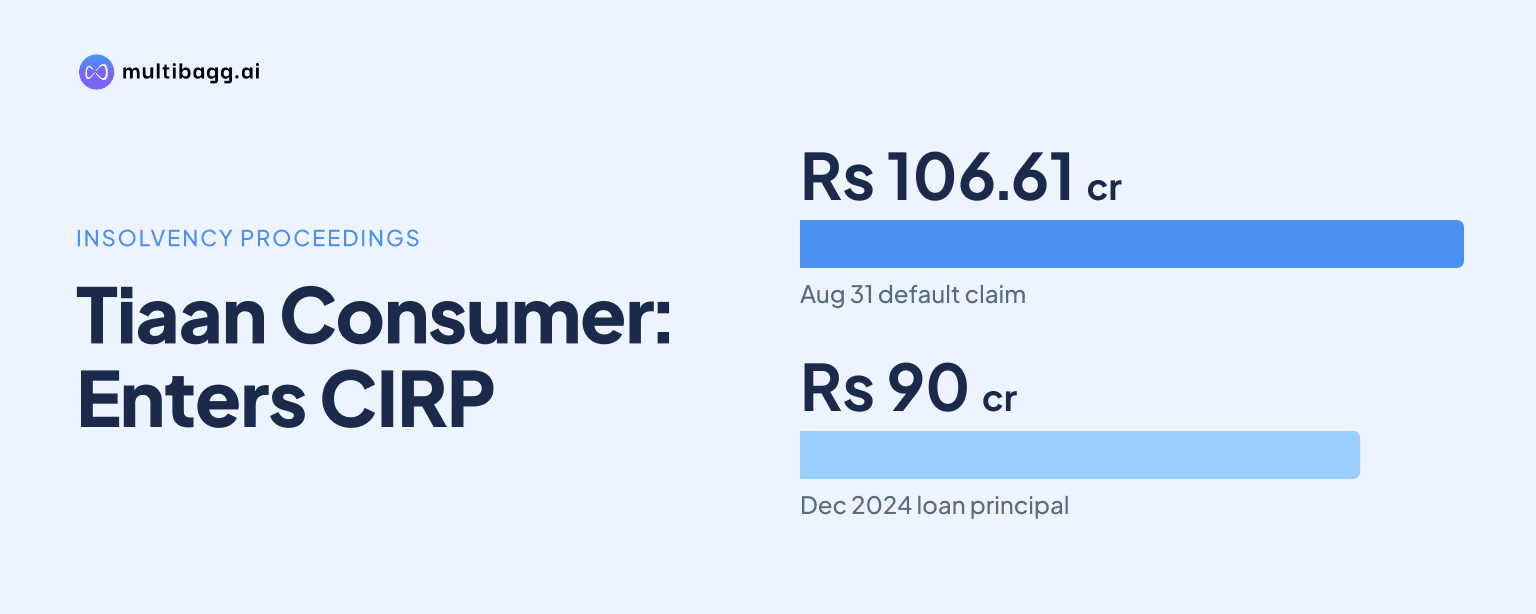
Tiaan Consumer Limited entered the corporate insolvency resolution process on November 17, 2026, after the National Company Law Tribunal admitted a Section 7 petition claiming Rs 106.6127414 crore, including interest through August 31, 2026. The order suspended the board’s powers and appointed Mukesh Kumar Jain as interim resolution professional.
Know Tiaan Consumer inside out
Results, valuation, peers and who's buying, in one view.
Why did Tiaan Consumer enter CIRP?
Tiaan Consumer entered the corporate insolvency resolution process, or CIRP, because the National Company Law Tribunal, Ahmedabad Bench, admitted Shri Niwas Leasing and Finance Limited’s Section 7 application on November 17, 2026. The petition, CP (IB) No. 289/7/AHM/2026, was filed on October 5, 2026 and first listed on September 29, 2026.
The tribunal found that the application was complete, the stated default exceeded the threshold under Section 4 of the Insolvency and Bankruptcy Code, 2016, and no disciplinary proceeding against the proposed interim resolution professional had been brought to its notice. It therefore admitted the petition under Section 7(5)(a), 49 days after the first listing.
The financial creditor claimed Rs 106.6127414 crore, including 12% annual interest calculated up to August 31, 2026. Tiaan Consumer contested the petition, arguing that the creditor had not established an enforceable financial debt, a precise default date or a verified interest calculation, but the tribunal concluded that the documentary record supported admission.
What loan and repayment default did the tribunal examine?
The tribunal examined a Rs 90 crore loan disbursed in December 2024, with Rs 89.9903 crore transferred on December 11, 2024 and Rs 9.7 lakh transferred on December 20, 2024. It described the bank statements, loan agreement and subsequent supplementary agreement as material evidence of a financial transaction.
The original loan agreement was executed on January 11, 2025, after the two disbursements, and specified interest of 12% a year. Tiaan Consumer argued that the timing of the agreement cast doubt on whether its terms, including interest, were mutually agreed when funds were sent. The tribunal held that a later agreement did not by itself negate the existence of financial debt.
A supplementary loan agreement dated August 5, 2025 extended the tenure from one year to 20 months from the first disbursal on December 11, 2024. Under clause 4, Tiaan Consumer acknowledged Rs 90 crore of outstanding principal plus applicable interest, and the 20-month tenure ended on August 11, 2026.
The creditor identified August 11, 2026 as the default date because the extended repayment period had expired without repayment of principal or interest. By August 31, 2026, the claim had increased from Rs 90 crore in principal to Rs 106.6127414 crore inclusive of the creditor’s stated interest calculation.
Why did the NCLT admit the petition despite Tiaan Consumer’s objections?
The tribunal held that Tiaan Consumer’s objections did not displace the documentary acknowledgement of Rs 90 crore in principal liability. The company disputed the interest component because it said no detailed calculations, tax deducted at source certificates or corresponding Form 26AS entries had been supplied, but the order said the precise interest amount could be considered against contractual terms and supporting account records.
Tiaan Consumer also said the September 4, 2026 loan-recall notice conflicted with the creditor’s August 11, 2026 default date. The tribunal found that the August 5, 2025 supplementary agreement set a 20-month maturity from December 11, 2024, and that a recall notice issued after maturity did not itself alter the contractual repayment date or extinguish an earlier default.
Settlement correspondence between September 11 and September 28, 2026 did not establish discharge of the debt, the tribunal said. Tiaan Consumer sought more time in emails of September 14 and September 17, then proposed on September 25 to sell equity investments or shares at a discounted or mutually agreed value; the creditor rejected that proposal on September 28.
The tribunal also rejected the proposition that Tiaan Consumer’s claimed status as a going concern could independently defeat admission. It noted that the Insolvency and Bankruptcy Code (Amendment) Act, 2026 took effect on May 26, 2026 and revised Section 7(5) to provide for admission when default has occurred, the application is complete and the proposed resolution professional has no pending disciplinary proceeding.
Got a follow-up? Ask IRIS
What changes for Tiaan Consumer after the CIRP order?
Tiaan Consumer’s board powers were suspended from November 17, 2026, with Mukesh Kumar Jain appointed to act as interim resolution professional. Under Sections 17, 18 and 20 of the Code, he is to take over management and control of the company’s assets, records and information for the CIRP.
A Section 14 moratorium began on the order date of November 17, 2026. It bars the institution or continuation of specified suits and proceedings, execution actions, asset transfers or encumbrances, security enforcement and recovery of property held by Tiaan Consumer.
The moratorium continues until CIRP completion, approval of a resolution plan under Section 31(1), or a liquidation order under Section 33. The order says essential goods and services cannot be terminated, suspended or interrupted during that period except as permitted by Sections 14(2), 14(2A) and other applicable provisions.
The Section 14(1) restrictions do not apply to proceedings against a surety under a contract of guarantee to Tiaan Consumer. The tribunal also directed the company’s personnel, promoters and management-associated persons to cooperate under Section 19, allowing the interim resolution professional to seek further directions if cooperation is not provided.
What are the next CIRP deadlines for Tiaan Consumer?
Mukesh Kumar Jain must make a public announcement and invite creditor claims within three days of his appointment, under Section 15 and Regulation 6 of the CIRP Regulations, 2016. He must also file an affidavit within three days of uploading of the order stating his number of ongoing assignments as interim resolution professional, resolution professional and liquidator.
Shri Niwas Leasing and Finance Limited must deposit Rs 5 lakh, excluding applicable taxes, with the interim resolution professional within seven days of the November 17, 2026 order. The tribunal said this advance would cover initial CIRP costs, including public notice and invitation of claims, subject to adjustment against costs approved by the committee of creditors.
The interim resolution professional must examine Tiaan Consumer’s books, bank statements and other records, including board-resolution sequences, fund sources and movements, transactions between the parties and financial particulars. He must file a compliance status report before the tribunal within 20 days of receiving the order.
The claim-verification and record-review steps will shape the creditor pool and the subsequent resolution process. The order does not state a value for other creditor claims, any resolution proposal or a timetable beyond the three-day, seven-day and 20-day directions.
Conclusion
The November 17, 2026 order places Tiaan Consumer under a court-supervised insolvency process after the tribunal found a documented Rs 90 crore loan, an acknowledged principal liability and a default on August 11, 2026. The admitted petition cites Rs 106.6127414 crore inclusive of interest through August 31, 2026, while the precise interest component remains subject to contractual terms and supporting account records.
Next, investors should watch the public announcement and creditor claims process within three days, the Rs 5 lakh initial-cost deposit within seven days, and the interim resolution professional’s status report within 20 days. The tribunal has specifically directed review of Tiaan Consumer’s books, fund movements and records, which will inform the next steps in CIRP.