










Tirupati Forge Reports INR 581.5 Million Q2 FY27 Revenue
Key highlights
- Tirupati Forge reported Q2 FY27 revenue of INR 581.5 million, up 51% quarter on quarter from INR 384.3 million.
- Q2 FY27 profit after tax was INR 41.2 million, up 238% sequentially from INR 12.2 million.
- EBITDA was INR 109.1 million in Q2 FY27, up 27% year on year.
- Tirupati Forge reported operating margin of 14.2% and PAT margin of 7.2% in Q2 FY27.
powered by IRIS
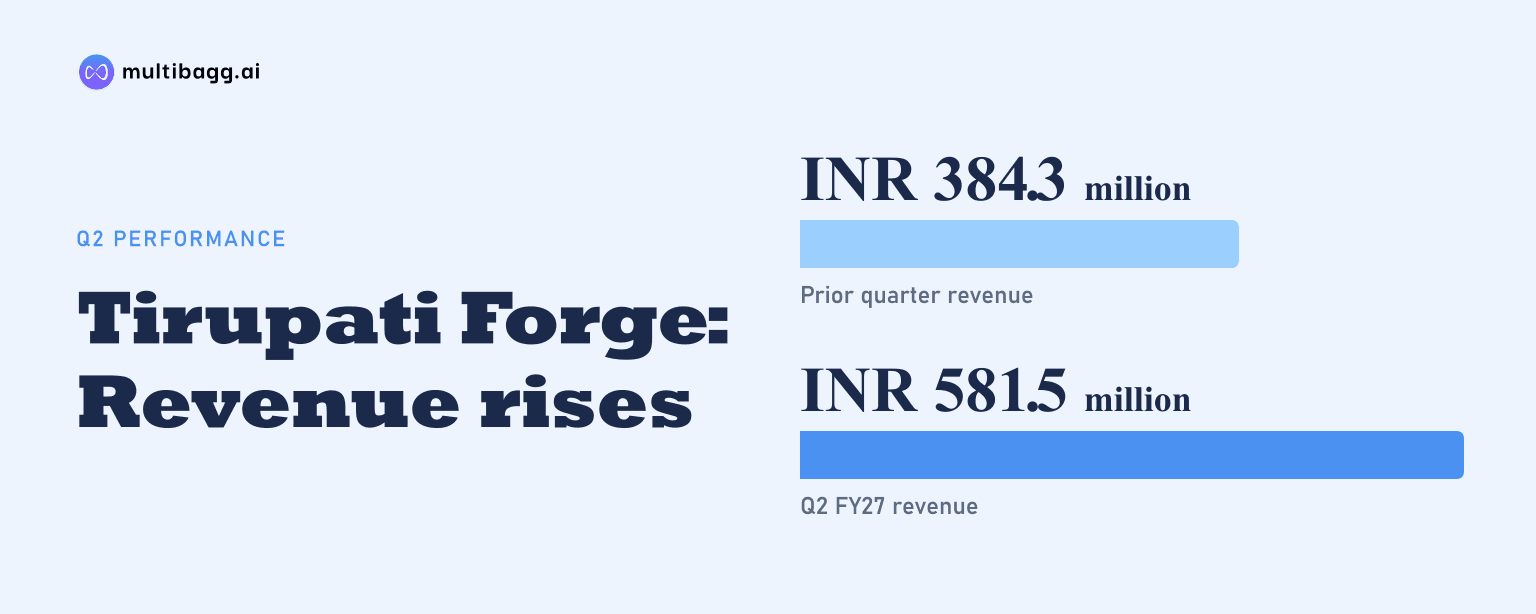
Tirupati Forge Limited reported revenue of INR 581.5 million for Q2 FY27, a 51% increase from INR 384.3 million in Q1 FY27, while profit after tax rose 238% sequentially to INR 41.2 million. The figures indicate a sharp sequential improvement in the September 2026 quarter, although the company has not published an earnings-call transcript for the period.
Know Tirupati Forge inside out
Results, valuation, peers and who's buying, in one view.
What did Tirupati Forge report for Q2 FY27?
Tirupati Forge reported Q2 FY27 revenue of INR 581.5 million, according to its investor presentation. Revenue was higher than INR 384.3 million reported for Q1 FY27, resulting in sequential growth of 51%.
Earnings improved faster than revenue on a quarter-on-quarter basis. Profit after tax was INR 41.2 million, compared with INR 12.2 million in the preceding quarter. The investor presentation therefore showed a 238% increase in quarterly profit after tax.
The Q2 FY27 figures cited here are drawn from the investor presentation rather than an earnings-call transcript or management guidance. The available material states that the company is optimistic about demand prospects, particularly in North America, and identifies defence manufacturing capacity and international-market expansion as areas of focus.
How did Tirupati Forge's profitability change year on year?
Tirupati Forge reported EBITDA of INR 109.1 million in Q2 FY27, up 27% year on year. Operating profit was INR 80.9 million, an increase of 31% from the corresponding quarter of the previous year.
Profit after tax rose 6% year on year to INR 41.2 million. The difference between the stronger sequential increase and the more modest year-on-year profit growth is important because both comparisons describe different periods. The company did not provide an earnings-call transcript explaining the specific drivers of these changes.
Operating margin stood at 14.2%, up 10 basis points year on year. PAT margin was 7.2%, down 160 basis points year on year. These margin measures show that operating profitability improved slightly from a year earlier, while the share of revenue retained as profit after tax was lower.
What is driving Tirupati Forge's operational focus?
Tirupati Forge has identified demand from North America, expansion in international markets and the scaling of defence manufacturing capabilities as its stated growth areas. The presentation also refers to a dedicated, fully automated plant for 155mm artillery shell bodies intended for India's military procurement market.
The artillery-shell body initiative is relevant because it is linked to domestic defence procurement. The available information describes this business as a high-margin opportunity, but it does not provide plant capacity, investment outlay, commissioning dates, order values or revenue contribution. Those details remain necessary to assess the financial scale of the project.
The company operates in a manufacturing environment where production execution, customer demand and export-market access can affect quarterly performance. Its stated international focus means that reported growth is relevant not only to domestic industrial demand but also to the pace of overseas business development.
Got a follow-up? Ask IRIS
How do the Q2 FY27 results compare with recent quarters?
Tirupati Forge's Q2 FY27 profit after tax of INR 41.2 million was materially above the INR 12.2 million reported for Q1 FY27. Earlier reported quarterly profit figures included INR 15.22 million for the March 2026 quarter and INR 20.22 million for the December 2025 quarter.
For the April-June 2026 period, another reported update stated revenue of INR 381.0 million and profit of INR 12.2 million. The Q2 investor presentation uses INR 384.3 million as the Q1 FY27 revenue comparison base. The small difference should be treated as a variation between the disclosed data references, while the 51% sequential growth calculation is the figure stated in the Q2 presentation.
The company had announced that its board would meet on 5 November 2026 to consider Q2 and first-half FY27 unaudited standalone results. The disclosure also noted that listed companies are required to publish quarterly results within 45 days of the quarter-end, with the July-September 2026 results indicated as due by 14 November 2026.
What do these results mean for investors and the industry?
Tirupati Forge's reported revenue and profit expansion provides a current data point on its operating momentum, especially after the lower Q1 FY27 profit base. The 51% quarter-on-quarter revenue increase and 238% rise in profit after tax are the clearest sequential indicators in the presentation.
For investors, the margin figures provide an additional measure beyond sales growth. Operating margin improved by 10 basis points year on year, but PAT margin declined by 160 basis points. No share-price movement, valuation data or management guidance was provided in the supplied material, so the available disclosures do not establish a market-price impact.
The defence manufacturing plan is also relevant to the wider industrial sector because it is tied to domestic procurement priorities. However, the financial contribution of the proposed artillery-shell body plant cannot be quantified from the disclosed information. Production milestones, customer orders and capacity details would be required for a fuller assessment.
Conclusion
Tirupati Forge reported Q2 FY27 revenue of INR 581.5 million and profit after tax of INR 41.2 million, with both measures showing strong sequential improvement from Q1 FY27. Year-on-year data showed EBITDA growth of 27%, operating-profit growth of 31% and PAT growth of 6%, while PAT margin declined from the prior-year quarter.
Investors will watch the formal Q2 and first-half FY27 standalone results process, which the company scheduled for board consideration on 5 November 2026 and which was indicated as due by 14 November 2026. Further disclosures on North American demand, international expansion and the 155mm artillery-shell body plant would help clarify the scale and timing of the company's stated growth plans.