










Titagarh Rail Systems restates results after Firema discrepancy
Key highlights
- Titagarh Rail Systems restated September 2025 comparatives for a Rs 53.56 crore Firema-related provision.
- Restated standalone profit before tax for the half year ended September 30, 2025 was Rs 77.91 crore.
- Transporti Ferroviari was listed as an associate only up to July 23, 2026.
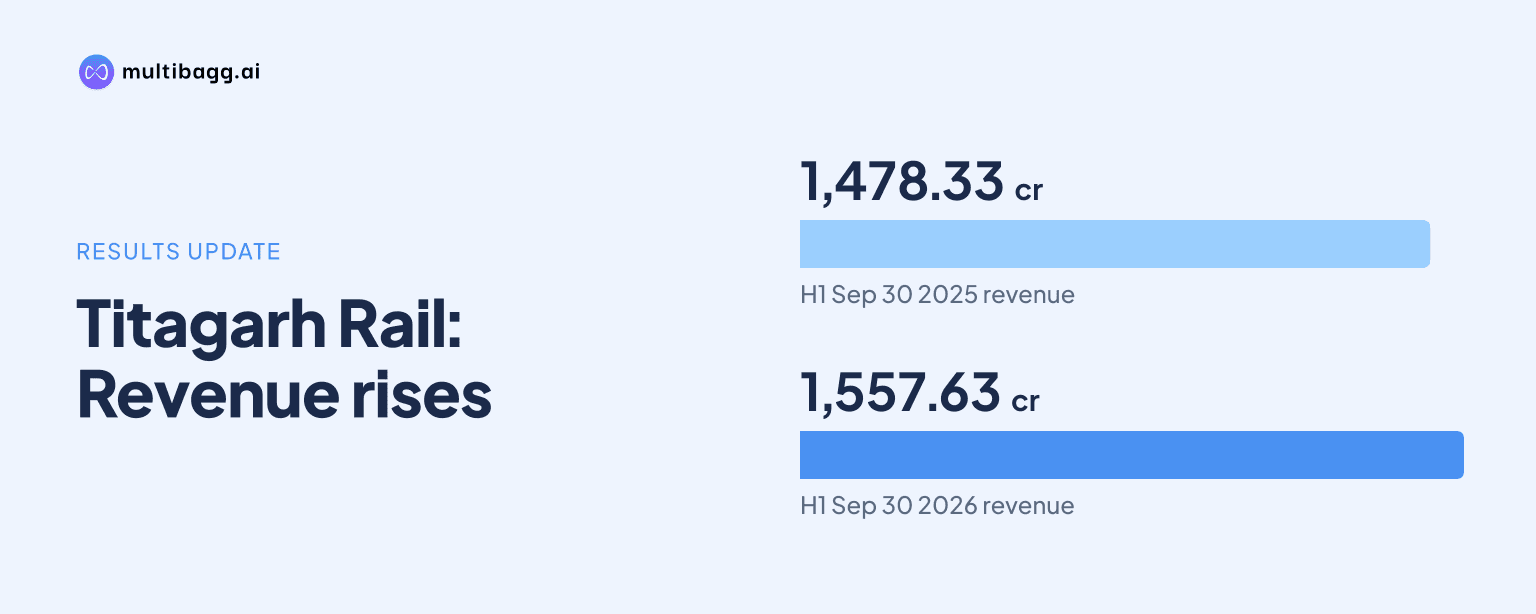
- Consolidated revenue rose to Rs 1,557.63 crore in the half year ended September 30, 2026 from Rs 1,478.33 crore.
powered by IRIS
Titagarh Rail Systems Limited restated its September 2025 comparative results after identifying a Rs 53.56 crore provision linked to Firema, whose statutory audited loss differed significantly from management accounts previously used in consolidation. The correction reduced the comparability of prior-period profit figures and coincided with Transporti Ferroviari S.p.A. being listed as an associate only until July 23, 2026.
Know Titagarh Rail Systems inside out
Results, valuation, peers and who's buying, in one view.
Why did Titagarh Rail Systems restate the September 2025 comparatives?
Titagarh Rail Systems restated prior-period comparative information because Firema’s statutory audited financial statements for the year ended March 31, 2025 reported a significantly different loss from the management accounts used for consolidation. The company said those management accounts had been audited by a component auditor, but the variation required correction of the earlier reported information.
The joint auditors drew attention to the adjustment as a correction of prior-period errors under Indian Accounting Standard 8, or Ind AS 8, which covers accounting policies, changes in accounting estimates and errors. Their review report, dated November 10, 2026, said its conclusion was not modified in respect of the matter. The adjustment was recorded in the quarter ended June 30, 2025 and consequently affected the half year ended September 30, 2025 and the corresponding standalone cash-flow statement.
The disclosed item was a Rs 53.56 crore provision towards loans and receivables connected with Titagarh Rail Systems’ exposure to Transporti Ferroviari S.p.A., formerly Titagarh Firema S.p.A. The standalone notes identify that amount as an exceptional item, while the consolidated results also show Rs 53.56 crore of exceptional items in the comparative half year. No equivalent exceptional item is shown in the half year ended September 30, 2026.
What did the Firema correction change in reported profit?
The restated standalone half-year figures show exceptional items of Rs 53.56 crore, profit before tax of Rs 77.91 crore and profit after tax of Rs 60.80 crore for the half year ended September 30, 2025. These are the comparative figures after the company incorporated the Firema-related provision, rather than newly reported charges for September 2026.
At the consolidated level, profit before share of loss of joint ventures and associates, exceptional items and tax was Rs 124.38 crore in the restated half year ended September 30, 2025. After a Rs 11.08 crore share of losses from joint ventures and associates and the Rs 53.56 crore exceptional item, consolidated profit before tax was Rs 59.36 crore. The source therefore makes clear that the pre-exceptional operating comparison and the final profit-before-tax comparison measure different effects.
For the half year ended September 30, 2026, Titagarh Rail Systems reported consolidated profit before share of losses, exceptional items and tax of Rs 154.13 crore. Its share of joint-venture and associate loss fell to Rs 1.24 crore, and consolidated profit before tax was Rs 152.89 crore without an exceptional item in that line. The increase from Rs 59.36 crore in the restated comparative period includes the absence of the earlier Rs 53.56 crore charge.
When did Transporti Ferroviari stop being an associate?
Transporti Ferroviari was listed in the auditors’ entity schedule as an associate only up to July 23, 2026. The source identifies it as Transporti Ferroviari S.p.A., formerly Titagarh Firema S.p.A., and the supplied topic information states that the Italian associate entered liquidation, ending Titagarh Rail Systems’ significant influence and equity accounting for that business.
The review report separately lists Titagarh Firema Engineering Services Private Limited among subsidiaries, making it distinct from Transporti Ferroviari. It also lists Titagarh Singapore Pte Ltd only up to May 5, 2026, while noting that one subsidiary’s interim information was prepared on a liquidation basis through that date. The report does not connect that May 5 liquidation-basis disclosure to Transporti Ferroviari.
The supplied filing does not disclose a liquidation distribution, the investment carrying value removed, or a gain or loss specifically generated by Transporti Ferroviari’s exit from associate accounting. It also does not quantify residual loans, receivables or guarantees after July 23, 2026. The Rs 53.56 crore provision concerns the earlier comparative correction and should not be presented as a disclosed 2026 exit loss.
Got a follow-up? Ask IRIS
How did the latest half year compare with the restated period?
Titagarh Rail Systems reported consolidated revenue from operations of Rs 1,557.63 crore for the half year ended September 30, 2026, up Rs 79.30 crore from Rs 1,478.33 crore in the restated half year ended September 30, 2025. Total income rose to Rs 1,571.48 crore from Rs 1,504.62 crore, although other income declined to Rs 13.85 crore from Rs 26.08 crore.
Operating cash generation moved in the opposite direction to revenue. Consolidated net cash generated from operating activities was Rs 152.96 crore in the latest half year, down Rs 32.50 crore from Rs 185.46 crore in the restated comparative period. Payments for property, plant and equipment, including capital work in progress, were Rs 186.26 crore, compared with Rs 203.20 crore a year earlier.
The group’s share of losses from joint ventures and associates improved by Rs 9.84 crore, from Rs 11.08 crore in the restated period to Rs 1.24 crore in the latest half year. That improvement occurred alongside the change in Transporti Ferroviari’s associate status on July 23, 2026, but the filing does not attribute the movement in equity-accounted losses to that event.
What did the auditors conclude on the restatement?
The joint auditors issued an unmodified limited-review conclusion on November 10, 2026. They conducted the work under Standard on Review Engagements 2410, under which a review provides moderate assurance and is narrower in scope than an audit. They specifically highlighted Note 4 on the Ind AS 8 restatement without modifying their conclusion.
The report distinguishes reviewed information from information not reviewed by subsidiary auditors. One reviewed subsidiary had total assets of Rs 212.64 crore and net assets of Rs 117.30 crore as at September 30, 2026, with Rs 49.76 crore of revenue in the six months from April 1, 2026. Two unreviewed subsidiaries and one trust together had Rs 4.17 crore of total assets and Rs 2.55 crore of net assets, which management said were not material to the group.
The auditors also reported that one joint venture contributed a Rs 1.24 crore share of net loss to the group for the six months ended September 30, 2026. For one associate and two joint ventures based on unreviewed interim information, the group’s reported share of profit or loss was nil for both the quarter and six-month period. Those disclosures do not change the separately disclosed Firema comparative correction.
Conclusion
Titagarh Rail Systems corrected a material prior-period reporting issue after statutory accounts for Firema showed a significantly different loss from the management accounts used in consolidation. The Rs 53.56 crore provision reshaped the September 2025 comparative profit figures, while the latest half year showed revenue of Rs 1,557.63 crore and profit before tax of Rs 152.89 crore without a corresponding exceptional charge.
The next disclosure to watch is the accounting outcome of Transporti Ferroviari’s liquidation and the end of associate treatment after July 23, 2026. The filing establishes the classification cut-off but leaves unresolved the amount of any derecognition, liquidation proceeds, exit gain or loss, and any remaining Firema-related exposure.