










TPL Plastech Q2 revenue rose 39.9% while EBITDA margin fell to 9.3%
Key highlights
- TPL Plastech reported Q2 FY27 revenue of Rs 149.52 crore, up 39.9% year on year.
- Q2 FY27 EBITDA was Rs 13.86 crore, while EBITDA margin fell to 9.3% from 11.1%.
- Q2 FY27 volume grew 15.0%, primarily led by the IBC segment.
- The Bhuj facility is expected by management to add about Rs 100 crore of annual revenue within three years.
powered by IRIS
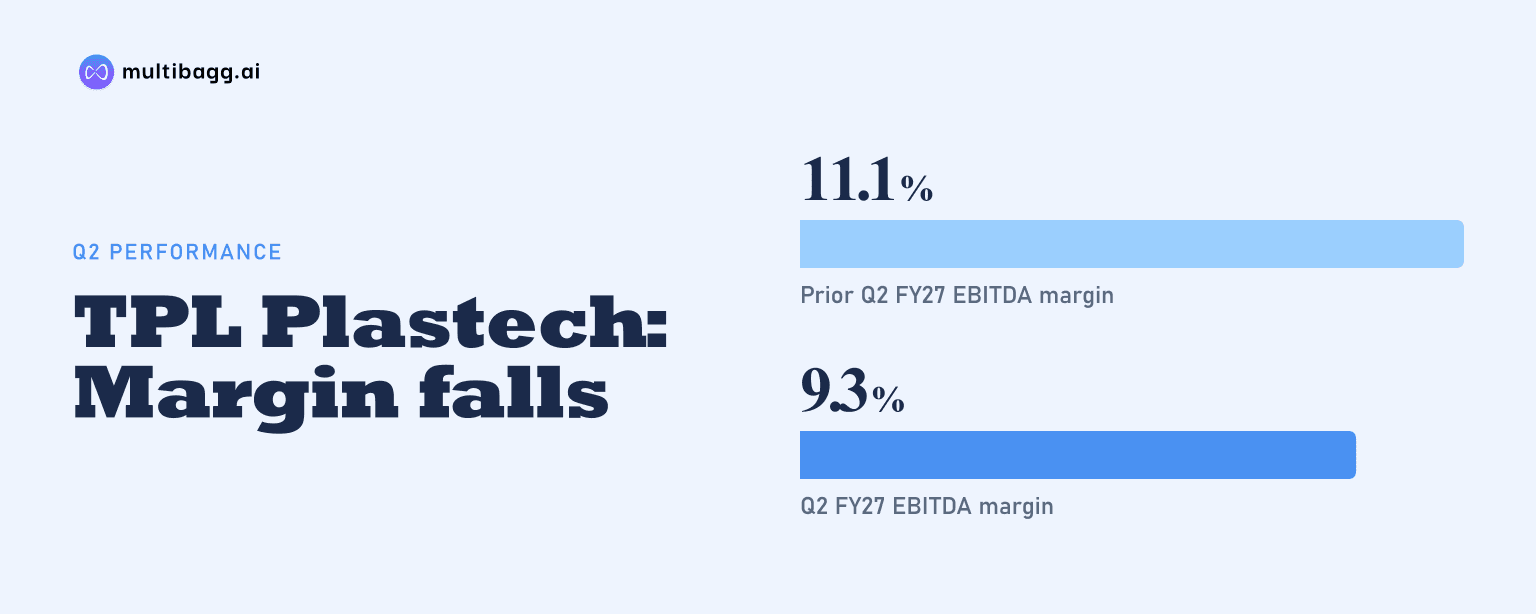
TPL Plastech Limited reported revenue growth of 39.9% to Rs 149.52 crore in Q2 FY27, the second quarter of financial year 2027, but earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell 180 basis points to 9.3% from 11.1%, as volume increased 15.0% primarily through the intermediate bulk container (IBC) segment.
Know TPL Plastech inside out
Results, valuation, peers and who's buying, in one view.
Why did TPL Plastech revenue rise faster than EBITDA in Q2 FY27?
TPL Plastech’s revenue rose faster than EBITDA because revenue increased 39.9% year on year while EBITDA increased 16.7%. Revenue from operations reached Rs 149.52 crore in Q2 FY27, compared with Rs 106.88 crore in Q2 FY26. EBITDA was Rs 13.86 crore, up from Rs 11.88 crore in the comparable quarter. The difference in these growth rates resulted in EBITDA margin moving to 9.3% from 11.1%.
The company reported 15.0% volume growth in Q2 FY27, primarily driven by the IBC segment and supported by demand across other packaging products. This means sales growth exceeded reported volume growth, with revenue rising by nearly 40%. The release does not quantify the contribution of volumes, product mix or pricing to revenue growth, so it does not establish a specific cause for the 180-basis-point margin decline.
How did TPL Plastech’s first-half profitability compare with last year?
TPL Plastech’s first-half, or H1, FY27 profitability also trailed revenue growth, with EBITDA margin at 9.2% versus 11.1% in H1 FY26. For the six months, revenue from operations increased 38.8% to Rs 274.06 crore from Rs 197.29 crore. EBITDA rose 15.6% to Rs 25.33 crore from Rs 21.92 crore, while profit after tax increased 22.2% to Rs 15.05 crore.
The first-half figures show a similar pattern to Q2 FY27: revenue grew by more than twice the EBITDA growth rate. Profit after tax margin was 5.5% in H1 FY27, compared with 6.2% in H1 FY26, a reduction of 70 basis points. Profit after tax nonetheless grew faster than EBITDA, at 22.2% versus 15.6%, based on the company’s reported consolidated figures.
What is driving TPL Plastech’s volume growth and capacity plan?
TPL Plastech attributed Q2 FY27 volume growth of 15.0% primarily to the IBC segment, while management cited stable demand from chemicals, specialty chemicals and pharmaceutical sectors. The company makes technology-based industrial packaging, including plastic drums, jerry cans and IBCs. Its customer industries also include petrochemicals, plasticizers, fast-moving consumer goods and food products.
The company commenced commercial operations at its Bhuj, Gujarat facility within its committed timeline. The plant makes industrial packaging products, including IBCs, and is expected by management to generate about Rs 100 crore of additional annual revenue within three years. TPL Plastech has five manufacturing locations, at Silvassa, Ratlam, Bhuj, Vizag and Dahej, according to the November 4, 2026 release.
Management has outlined a volume growth target of about 15% a year over the coming years, subject to fluctuations in key input costs. That target is broadly in line with Q2 FY27 volume growth of 15.0% and above H1 FY27 volume growth of 13.7%. The release identifies the target as a management plan rather than a reported forecast of future revenue or profit.
Got a follow-up? Ask IRIS
What actions has TPL Plastech disclosed to improve capital efficiency?
TPL Plastech reported return on capital employed (ROCE) of 22.6% in H1 FY27, up from 21.0% in H1 FY26. The 160-basis-point improvement occurred despite the H1 EBITDA margin declining 190 basis points to 9.2%. Management is targeting an annual ROCE increase of 1.5% to 2.0%, although the release does not provide a timeline beyond the annual target.
The company plans to source about 75% of its power requirement through solar energy, requiring estimated investment of about Rs 5 crore. Management estimates annual savings of about Rs 4 crore and an 18-month payback period, and says the project will contribute to ROCE. These figures are plans and estimates, not reported savings for Q2 FY27 or H1 FY27.
Management also said it is consolidating products and facilities, reducing manpower and power costs, automating operations, re-engineering moulds and machinery, and optimising working capital. TPL Plastech said its institutional model uses long-term customer relationships and mutually agreed pricing mechanisms intended to pass through input-cost fluctuations. The release says these mechanisms help maintain margin stability, but supplies no quarter-specific cost or pricing data.
How could the proposed merger affect TPL Plastech?
TPL Plastech’s board has approved a proposed merger by absorption into parent Time Technoplast Limited, which holds 75% of TPL Plastech. The scheme would take effect from April 1, 2026, subject to statutory and regulatory approvals and an order from the National Company Law Tribunal. The disclosure does not state when those approvals may be completed.
According to the company, the proposed merger aims to streamline operations and enhance efficiencies by combining the businesses. The Q2 FY27 release provides no merger exchange ratio, financial impact estimate or expected completion date. As a result, reported Q2 revenue of Rs 149.52 crore and EBITDA margin of 9.3% remain the disclosed current-period operating metrics.
Conclusion
TPL Plastech delivered substantial reported sales growth in Q2 FY27 and H1 FY27, supported by 15.0% quarterly volume growth and IBC-led demand. However, EBITDA increased more slowly than revenue in both periods, producing a Q2 margin of 9.3% and H1 margin of 9.2%, against 11.1% in the respective prior-year periods.
Next, readers can watch progress at the Bhuj facility, which management expects to add about Rs 100 crore of annual revenue within three years, and the planned solar project with estimated Rs 4 crore annual savings. Other disclosed milestones are management’s approximately 15% annual volume-growth target, its 1.5% to 2.0% annual ROCE-improvement target, and regulatory approval of the proposed merger.