










Vipul reviewer cannot conclude on Rs 10.8066 crore advance
Key highlights
- Vipul’s reviewer could not conclude on recovery of a Rs 10.8066 crore advance to an associate at September 30, 2026.
- Vipul had not provided interest expense on certain ICDs of Rs 15.8228 crore while lender negotiations continued.
- Outstanding ICDs totalled Rs 63.3530 crore at September 30, 2026, without executed agreements or supporting documents.
- Vipul reported Rs 145.4143 crore of loans and advances for which recovery terms were still being finalised.
powered by IRIS
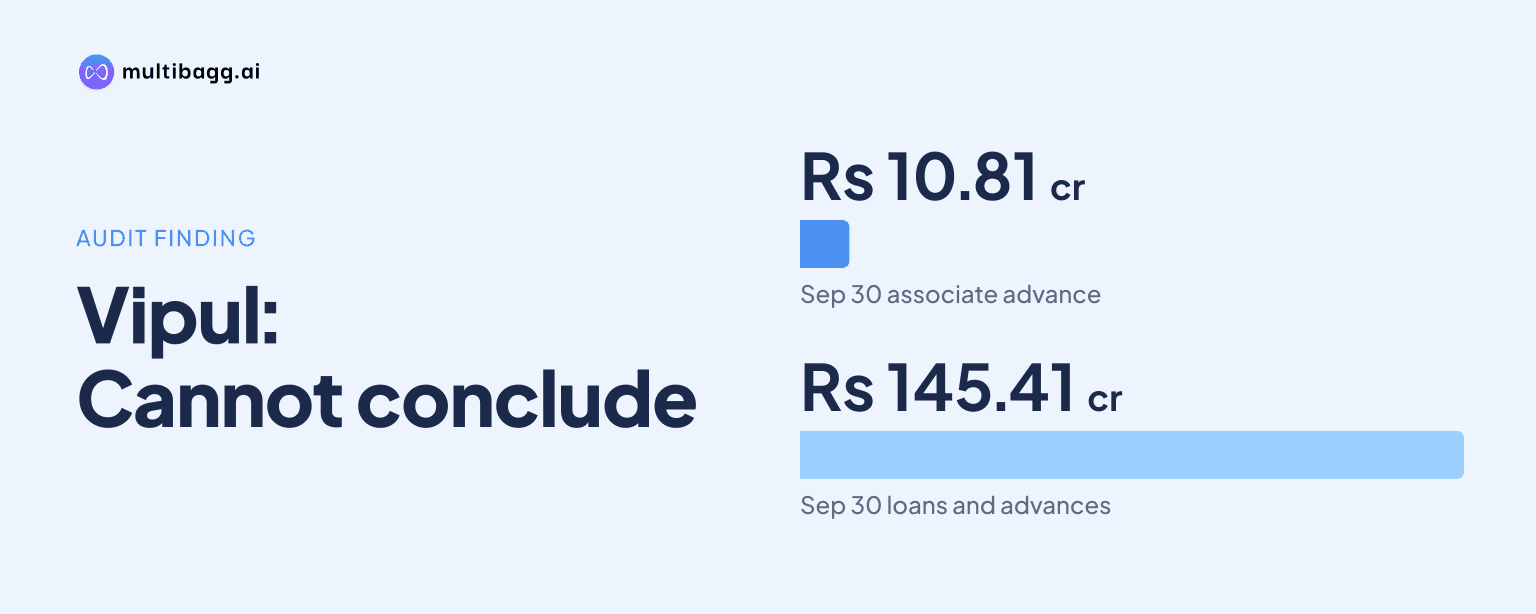
Vipul Limited’s reviewer could not conclude on recovery of a Rs 10.8066 crore associate-project advance at September 30, 2026 because the project was on hold over regulatory issues; it also could not determine the effect of unprovided interest on Rs 15.8228 crore of inter-corporate deposits.
Know Vipul inside out
Results, valuation, peers and who's buying, in one view.
Why could the reviewer not conclude on Vipul’s project advance?
The reviewer could not conclude whether Vipul could recover the Rs 10.8066 crore project advance to Vipul Karamchand SEZ Private Limited because the associate’s project was on hold due to regulatory issues. The amount was included in other non-current assets at September 30, 2026 and was presented under the basis for disclaimer of conclusion in the limited review report dated November 5, 2026.
Vipul’s filing does not state that it impaired or wrote off the Rs 10.8066 crore balance. Instead, it says the project’s status prevented the reviewer from assessing recoverability at the reporting date. That differs from a quantified impairment charge because neither the final recoverable amount nor a potential provision was determined in the report.
The same September 30, 2026 review separately identified Rs 32.7025 crore advanced to two wholly owned subsidiaries, Vipul Southern Infracon Limited and Vipul Hospitality Limited. Their net worth had eroded, and Vipul said it had initiated their merger process during the relevant quarter, but this subsidiary balance was an emphasis-of-matter item rather than part of the stated disclaimer basis.
What did the report say about Vipul’s ICD interest and liabilities?
Vipul had not provided interest expense on certain inter-corporate deposits, or ICDs, amounting to Rs 15.8228 crore because negotiations with lenders were under way for a mutual settlement. The filing also says interest on customer advances had not been booked while negotiations over settlement of those amounts continued.
The reviewer said agreements governing those balances were unavailable, so it could not determine the terms needed to set an applicable interest rate or calculate the related expense. It therefore said any potential overstatement or understatement could not be ascertained. The Rs 15.8228 crore figure identifies the ICDs on which interest had not been provided, rather than a quantified interest liability.
Vipul separately reported Rs 63.3530 crore of outstanding ICDs at September 30, 2026 for which agreements and supporting documentation had not been executed and were unavailable. This principal balance is larger than the Rs 15.8228 crore ICD amount associated with unprovided interest, showing that the two disclosures address different issues: documentation for outstanding deposits and measurement of related interest expense.
The filing says Vipul had negotiated with 12 inter-corporate lenders whose claims, including interest, were Rs 52.9618 crore. The lenders had initiated proceedings before the National Company Law Tribunal, National Company Law Appellate Tribunal and Real Estate Regulatory Authority, as well as action under Section 138 of the Negotiable Instruments Act and FIR No. 38/2026 with the Economic Offences Wing, Delhi.
What settlement has Vipul disclosed with ICD lenders?
Vipul said negotiations with the 12 lenders concluded on October 30, 2026, when the parties signed a Master Settlement Agreement with Tulip Infratech Pvt. Ltd. as confirming party. Vipul said it would recognise any gain or loss from that settlement only after the agreement’s conditions were fulfilled.
The October 30 agreement does not remove the uncertainty identified in the September 30, 2026 review because the filing does not state that its conditions had been met by the reporting date. Nor does it quantify a settlement gain, settlement loss, revised principal amount or interest charge. The reviewer’s inability to determine the interest effect was linked to unavailable agreements and terms for the underlying balances.
The report also records that Vipul had taken and granted several secured and unsecured loans and advances during the quarter, with agreements and documentation still being signed. Interest payable and receivable was computed from management-provided details wherever available, and Vipul said any impact would be recognised after documentation was completed.
Got a follow-up? Ask IRIS
What other asset-recovery issues did the reviewer identify at Vipul?
The largest balance in the qualified matters was Rs 145.4143 crore of secured and unsecured loans and advances included in current assets at September 30, 2026. Vipul was still finalising recovery terms and conditions, and the reviewer said the loans and advances should have been impaired, meaning current assets and profit for the year may be overstated by any required impairment.
Vipul had also advanced Rs 60.8631 crore to Flying Fox Private Limited under other financial assets, without recording impairment although the entity’s net worth had eroded. Separately, the Amritsar Project carried Rs 35.885 crore of advances subject to ongoing litigation; the reviewer described recovery as doubtful and said assets and profit may be overstated by any impairment ultimately required.
Another project-advance issue involved Rs 24 crore recoverable from Shri Kamala Priya Auto and General Agencies Private Limited and Mallipudi Anand. Vipul made a 50% provision of Rs 12 crore in financial year 2025-26, while recovery of the remaining Rs 12 crore was described as uncertain after the company’s name was struck off from the Register of Companies.
The report additionally referred to Rs 215.86 crore of income recognised in an earlier year under an arbitral award and interest under an MDA Agreement, included in trade receivables from Solitaire Ventures Pvt. Ltd. and Tanamera Developments Private Limited. Litigation for recovery was under way in the Delhi High Court and Supreme Court, and Vipul had not received the entire amount.
How do the disclaimer matters differ from Vipul’s qualified matters?
The disclaimer matters are the Rs 10.8066 crore associate advance and the unmeasurable interest effects on ICDs and customer advances, where the reviewer said it could not express a conclusion. The qualified matters, by comparison, include stated concerns over impairment, recovery terms, unconfirmed trade receivables and the accounting treatment of an amalgamation.
One accounting qualification concerns the merger of five wholly owned subsidiaries, approved by the National Company Law Tribunal on April 17, 2026 with an appointed date of April 1, 2022. Vipul used the pooling-of-interest method, but revenue and project costs from the Lavanya Project joint development agreement were recognised in the year ended March 31, 2026 rather than from the appointed date.
The reviewer said that treatment was not in accordance with Indian Accounting Standards and the scheme, affecting revenue, project costs, profit or loss, assets, liabilities, reserves and comparative information. Vipul separately disclosed that its board gave in-principle approval on September 15, 2026 for a fast-track merger of six wholly owned subsidiaries, which remained subject to approvals and had no impact on the September 30, 2026 results.
Conclusion
Vipul’s September 30, 2026 limited review identifies unresolved measurement and recovery questions alongside broader qualified matters. The Rs 10.8066 crore associate advance cannot yet be assessed for recovery, while terms needed to calculate interest on certain ICDs remain unavailable; these issues sit beside Rs 63.3530 crore of ICDs without executed supporting documents and other advances where the reviewer cited potential impairment.
The next disclosed developments to watch are fulfilment of conditions under the October 30, 2026 Master Settlement Agreement, which would trigger recognition of any gain or loss, and progress in documenting loan arrangements. Vipul also disclosed a proposed six-subsidiary fast-track merger that requires approvals, while resolution of regulatory issues at the associate project would be relevant to any later assessment of the Rs 10.8066 crore advance.