










Viyash Scientific’s operating cash flow rises to Rs 182.74 crore
Key highlights
- Viyash Scientific generated Rs 182.74 crore of operating cash in the half year ended 30 September 2026, up from Rs 151.27 crore.
- Net working-capital changes consumed Rs 207.24 crore, including Rs 121.94 crore absorbed by inventories.
- Cash and cash equivalents rose Rs 236.78 crore during the half year to Rs 492.54 crore.
- Financing activities generated Rs 109.37 crore, compared with a Rs 91.42 crore outflow in the restated prior-year half.
powered by IRIS
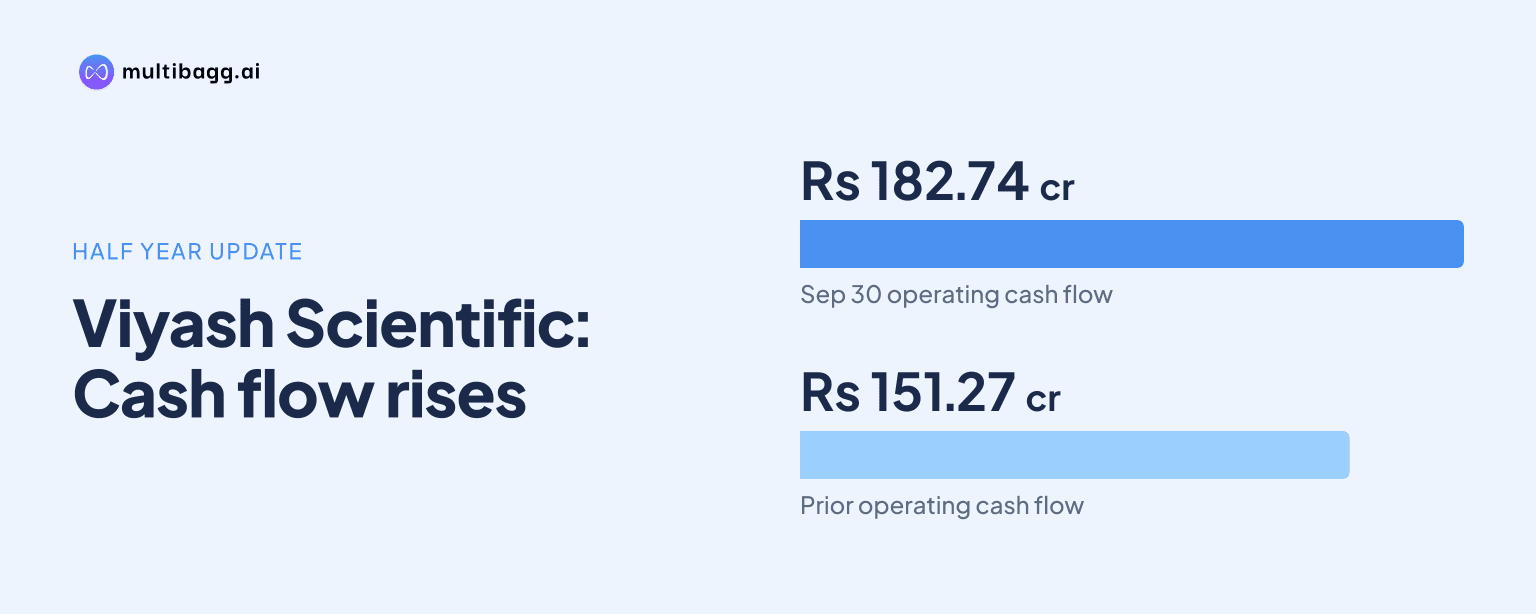
Viyash Scientific Limited generated Rs 182.74 crore of net operating cash in the half year ended 30 September 2026, up from Rs 151.27 crore a year earlier, although a Rs 207.24 crore net working-capital outflow absorbed nearly half of its Rs 417.20 crore operating profit before working-capital changes. Viyash Scientific ended the period with Rs 492.54 crore in cash and cash equivalents.
Know Viyash Scientific inside out
Results, valuation, peers and who's buying, in one view.
How did Viyash Scientific’s operating cash flow change?
Viyash Scientific’s net cash generated from operating activities rose Rs 31.47 crore year on year to Rs 182.74 crore in the half year ended 30 September 2026. Cash generated from operations before tax payments increased to Rs 209.96 crore from Rs 188.08 crore, while net income taxes paid declined to Rs 27.22 crore from Rs 36.81 crore. The comparison uses the restated half-year period ended 30 September 2025.
The rise in operating cash came alongside a larger increase in operating profit before working-capital changes, which reached Rs 417.20 crore from Rs 332.09 crore. Profit before tax was Rs 230.09 crore, compared with Rs 150.71 crore in the prior-year half, while depreciation and amortisation was Rs 107.10 crore versus Rs 114.70 crore. The cash-flow statement also records Rs 66.65 crore of share-based-payment expense, against Rs 22.96 crore a year earlier, as a non-cash adjustment in reaching operating profit before working-capital changes.
The table shows that the additional working-capital requirement was Rs 63.23 crore larger than in the comparable period. As a result, the Rs 85.11 crore increase in operating profit before working-capital changes produced a Rs 31.47 crore increase in reported operating cash flow. The source reports these figures on a consolidated basis for the half-year periods.
Why did working capital absorb more cash at Viyash Scientific?
Viyash Scientific recorded a Rs 207.24 crore net cash outflow from working capital in the half year ended 30 September 2026, compared with an outflow of Rs 144.01 crore in the restated prior-year period. Trade receivables, advances to suppliers and other assets consumed Rs 180.16 crore, versus Rs 139.75 crore previously. Inventories consumed a further Rs 121.94 crore, sharply above the Rs 17.68 crore outflow reported a year earlier.
An increase in trade payables, customer advances, other liabilities and provisions offset part of those demands, contributing Rs 94.86 crore of cash, compared with Rs 13.42 crore in the prior-year half. This offset did not cover the Rs 302.10 crore combined outflow from receivables-related assets and inventories. The cash-flow statement therefore identifies the inventory build as the largest change in the working-capital pattern between the two periods.
The 30 September 2026 balance sheet provides a narrower, point-in-time view of the movement. Inventories stood at Rs 921.11 crore, up from Rs 803.20 crore at 31 March 2026, while trade receivables were Rs 1,167.22 crore, compared with Rs 1,045.23 crore. Those balance-sheet movements are not identical to the cash-flow categories, which also include supplier advances and other assets, but they are consistent with the period’s larger working-capital cash use.
Got a follow-up? Ask IRIS
What funded Viyash Scientific’s higher cash balance?
Viyash Scientific’s cash and cash equivalents increased by Rs 236.78 crore during the half year, ending at Rs 492.54 crore on 30 September 2026 versus Rs 255.76 crore at the start of the period. Operating activities supplied Rs 182.74 crore and investing activities used Rs 55.33 crore. Financing activities added Rs 109.37 crore, whereas financing had used Rs 91.42 crore in the restated half year ended 30 September 2025.
Financing inflows included Rs 46.48 crore from the allotment of employee stock options, Rs 55.24 crore of proceeds from long-term borrowings and Rs 40.56 crore of net proceeds from short-term borrowings. These were partly offset by Rs 5.49 crore of long-term borrowing repayments, Rs 5.76 crore of lease-liability payments and Rs 21.66 crore of interest and other borrowing costs paid. The source therefore shows both new borrowings and option-allotment proceeds contributing to the increase in cash.
Investing cash use was Rs 55.33 crore, slightly above Rs 51.42 crore in the prior-year half. Purchases of property, plant and equipment, capital work in progress, capital creditors, capital advances and intangible assets totalled Rs 67.38 crore, offset by Rs 8.65 crore of interest received and Rs 1.69 crore of disposal proceeds. Capital work in progress on the balance sheet was Rs 42.13 crore at 30 September 2026, down from Rs 68.73 crore at 31 March 2026.
How comparable are Viyash Scientific’s prior-year cash-flow figures?
Viyash Scientific’s prior-year comparative cash-flow figures were restated following the Composite Scheme of Amalgamation. The National Company Law Tribunal sanctioned the scheme on 18 November 2025, it became effective on 18 December 2025, and the appointed date was 1 April 2025. Viyash Scientific accounted for the business combination using the pooling-of-interest method under Appendix C of Indian Accounting Standard 103, or Ind AS 103.
The restatement materially changes the basis for comparison with originally reported figures. For the period ended 30 September 2025, reported net operating cash flow was Rs 44.90 crore, while the restated figure used in the current statement is Rs 151.27 crore. Reported investing cash outflow was Rs 4.22 crore and reported financing cash outflow was Rs 32.57 crore, compared with restated outflows of Rs 51.42 crore and Rs 91.42 crore, respectively.
The auditor’s review states that the comparative financial information for the quarter and period ended 30 September 2025 was restated to reflect the amalgamation, and its conclusion was not modified in respect of that matter. Viyash Scientific is primarily engaged in pharmaceuticals and reports no separate reportable segment under Indian Accounting Standard 108, or Ind AS 108, according to the notes accompanying the results.
Conclusion
Viyash Scientific generated more operating cash in the half year ended 30 September 2026, with net operating inflow rising to Rs 182.74 crore from Rs 151.27 crore. The increase was moderated by a Rs 207.24 crore working-capital outflow, led by Rs 180.16 crore tied to receivables, supplier advances and other assets and Rs 121.94 crore tied to inventories. Financing inflows of Rs 109.37 crore, together with operating cash, helped raise cash and cash equivalents to Rs 492.54 crore.
The disclosed item to watch next is Viyash Scientific’s planned acquisition of BioforLife Italia S.r.l. through step-down wholly owned subsidiary Alivira Animal Health Limited, Ireland. Viyash Scientific entered a share-purchase agreement on 21 July 2025 to acquire 100% of the issued and outstanding share capital, but completion remains subject to required approvals. The source does not state that those approvals had been received by 30 September 2026.