










Earnings Per Share: EPS Drives P/E Ratios in India in 2026
Key highlights
- The Nifty 50 closed at 23,779.15 on 7 September 2026.
- Nifty Bank had the lowest P/E in the table at 13.51.
- Nifty Midcap Select had the highest P/E in the table at 31.98.
- The Nifty 50’s published P/E of 20.10 equalled a 4.98% earnings yield.
powered by IRIS
Earnings per share (EPS) explains the earnings side of a P/E ratio: on 7 September 2026, the Nifty 50 closed at 23,779.15 against a published P/E of 20.10. It divides profit attributable to each ordinary share, so a P/E changes when either price or underlying earnings move.
One clarification first, because it causes constant confusion in India. In the share market, EPS means earnings per share. In employment and provident fund contexts, EPS means the Employees' Pension Scheme, which is an entirely different thing. This article is about the first.
What does EPS mean in the share market?
EPS is the portion of a company's profit that belongs to each ordinary share. Profit becomes comparable to a share price only once it is expressed per share.
Consider the alternative: a company earning Rs 500 crore tells you nothing next to one earning Rs 50 crore until you know how many shares each of those profits is spread across. Reported profit arrives quarterly for listed companies, visible per instrument on the stocks hub.
What is the EPS formula?
EPS equals profit for ordinary shareholders divided by weighted average ordinary shares in issue. Profit here means after tax and after anything owed to preference shareholders, not headline revenue.
The denominator is a weighted average across the period rather than the closing share count. Shares issued halfway through a year were outstanding for only half of it, and the weighting accounts for that.
That weighted average is where most hand calculations go wrong. A company that doubles its share count on the last day of the year has barely changed the weighted average for that year, so its EPS falls only slightly. Do the same on day one and the average nearly doubles, and EPS roughly halves. The total shares at year end are the same, but the EPS is very different, which is why the denominator must be read as a period measure rather than a snapshot.
What is the difference between basic and diluted EPS?
Basic EPS uses the share count as it stands, while diluted EPS counts the shares that would exist if everything convertible into equity converted. Employee stock options, convertible debentures and warrants all create claims on future shares.
Diluted EPS assumes those claims are exercised, which raises the share count and therefore lowers the per-share figure. Companies report both figures, and the diluted number is the more conservative of the two.
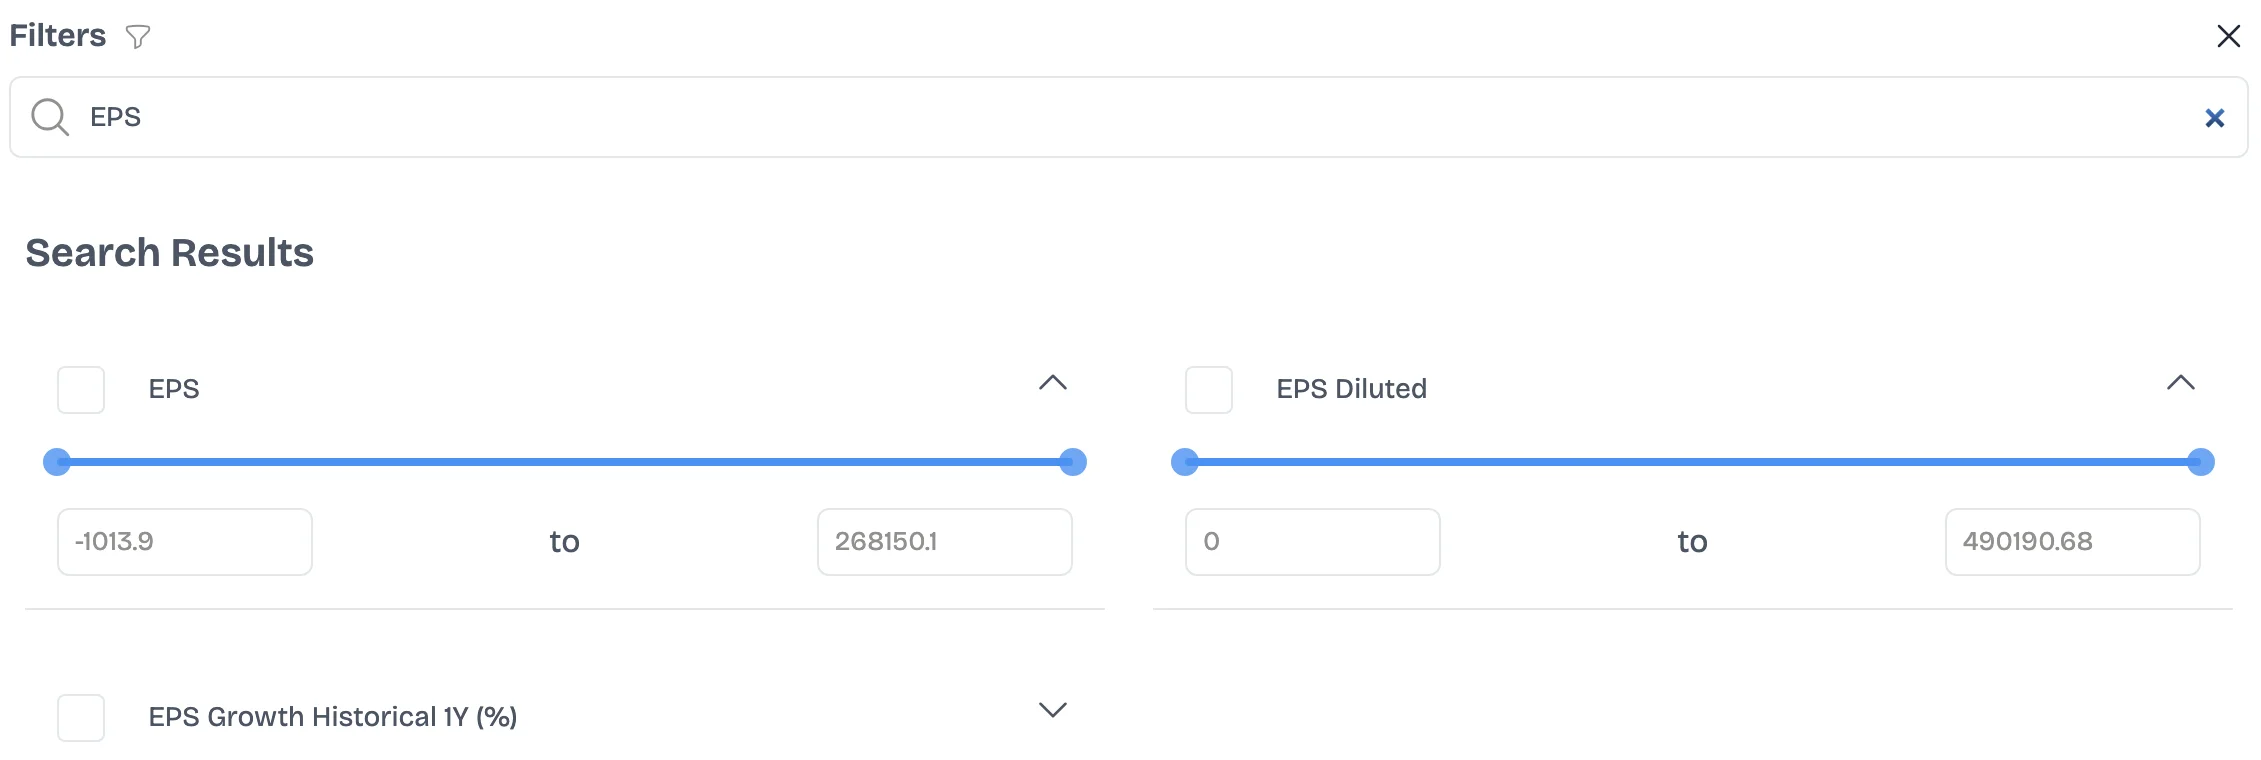
Basic and diluted EPS are held as two separate fields, which lets the gap between them be screened rather than inferred. Screenshot taken 15 September 2026.
Mind the gap between the two figures. A wide gap says a meaningful quantity of future equity has already been promised to someone.
What does EPS look like behind index levels in India in 2026?
An index carries a P/E of its own, and the same earnings logic sits underneath it. Each index below is shown at its settled close with the P/E that NSE publishes against it.
Closes: NSE, as of 7 September 2026. P/E: NSE, as of 8 September 2026. Earnings yield computed as 1 ÷ P/E from the published ratio in the preceding column.
The last column is the earnings yield, simply the P/E turned upside down. A P/E of 20.10 says the market is paying 20.10 times one year's earnings, while an earnings yield of 4.98% says those earnings amount to 4.98% of what is being paid. The two carry identical information; the yield form is more useful when comparing with something quoted as a percentage, such as a bond or deposit rate.
It is also the one per-unit figure this table can carry without an assumption. Dividing an index level by its P/E appears to yield earnings per index unit, but NSE does not state which level its ratio is struck against. Inverting the ratio needs no such assumption because 1 ÷ P/E is arithmetic on the published number alone, whatever base it was struck against. NSE Indices computes the Nifty 50 on free-float market capitalisation, which shapes the earnings behind the index without being published as a per-unit number.
The spread runs from 13.51 to 31.98 on P/E, or from 7.40% down to 3.13% on earnings yield, across four indices drawn from the same market on the same day. Each ratio has an earnings figure underneath it, and the ratio moves whenever either half does.
Got a follow-up? Ask IRIS
How do EPS, P/E and TTM figures work together?
Dividing a share price by EPS produces the P/E, while TTM EPS uses the four latest reported quarters instead of the most recent completed financial year. EPS is therefore the quieter half of the better-known P/E ratio.
The two measures are inseparable. A falling P/E has two possible causes, a lower price or higher earnings, and they are not the same event. Anyone reading the ratio without knowing which one moved is reading half the story.
The same split appears at index level, where the Nifty 50 carries a published P/E alongside its level, and both fields sit side by side across listed companies in Multibagg's screener.
Annual figures go stale fast. By the third quarter, last year's EPS describes a period that ended nine months ago, while the trailing 12-month version has already absorbed three newer quarters of trading. Quarterly results are where those updates arrive, browsable by financial year on the earnings tracker.
Is higher EPS better and what mistakes should I avoid?
Higher EPS is not a valid comparison between companies because EPS depends on the share count, and share counts are arbitrary. Two identical businesses with the same total profit can report different EPS if one has fewer shares outstanding.
Comparing raw EPS between companies therefore compares share structures as much as performance. EPS is more useful when tracked over time for one company, or when fed into a ratio such as P/E that puts the price back in.
Earnings also move with the wider economy, which is why arguments about India's headline growth reach aggregate earnings expectations, and why a single quarter can swing sharply for one company.
The most common EPS errors involve confusing its meaning, using the wrong share count or overlooking what changed in the profit figure. Five errors account for most misread EPS figures.
- Confusing the two EPS meanings. In the share market it is earnings per share; in provident fund contexts it is the Employees' Pension Scheme.
- Comparing raw EPS between companies. Share counts differ, so the comparison measures share structure as much as profit.
- Using basic EPS where diluted EPS matters. If a company has issued large numbers of options or convertibles, the basic figure overstates what each share earns after those claims convert.
- Missing exceptional items behind an EPS jump. Reported EPS includes one-off gains and losses, including an asset sale, court settlement, restructuring charge or impairment. Adjusted EPS strips these out to show the underlying run rate, and the two can differ sharply in a year where something unusual happened. A reported EPS that rises on the back of a land sale has not shown that the business earned more. Check whether a change came from operations or an exceptional item before treating it as a trend, and note that “adjusted” is not a standardised term: each company decides what it excludes.
- Treating a falling P/E as a conclusion on its own. At the Nifty 50's 20.10 on 8 September 2026, the ratio moves when either the level or the earnings behind it moves, and only one reflects higher earnings.
Conclusion
EPS translates a company's profit into a per-share figure, making it the earnings input behind P/E. Basic and diluted EPS can differ because of future equity claims, and the weighted average share count means the timing of share issuance matters as much as the closing number of shares.
The practical takeaway is to identify whether price, earnings or share count caused a change in EPS or P/E. Use TTM EPS when newer quarterly results make the last completed financial year less current, and check for exceptional items before interpreting an EPS change as an operating trend.
Disclaimer: This article is for informational and educational purposes only and is not investment, financial, legal or tax advice. Multibagg AI does not recommend whether to buy, sell or hold any security. Figures are as of the dates stated and may change. Consult a SEBI-registered investment adviser before making any investment decision.