










Zee Q2 revenue rose 13% as EBITDA margin fell to 3.2%
Key highlights
- Zee’s Q2 FY27 operating revenue rose 13% year on year to Rs 2,224.6 crore.
- Zee’s Q2 FY27 EBITDA fell 52% to Rs 70.8 crore as the EBITDA margin declined to 3.2% from 7.4%.
- Subscription revenue increased 30% year on year to Rs 1,332.4 crore, while advertising revenue was flat at Rs 803 crore.
- Zee’s Q2 FY27 profit after tax fell 40% year on year to Rs 45.6 crore.
powered by IRIS
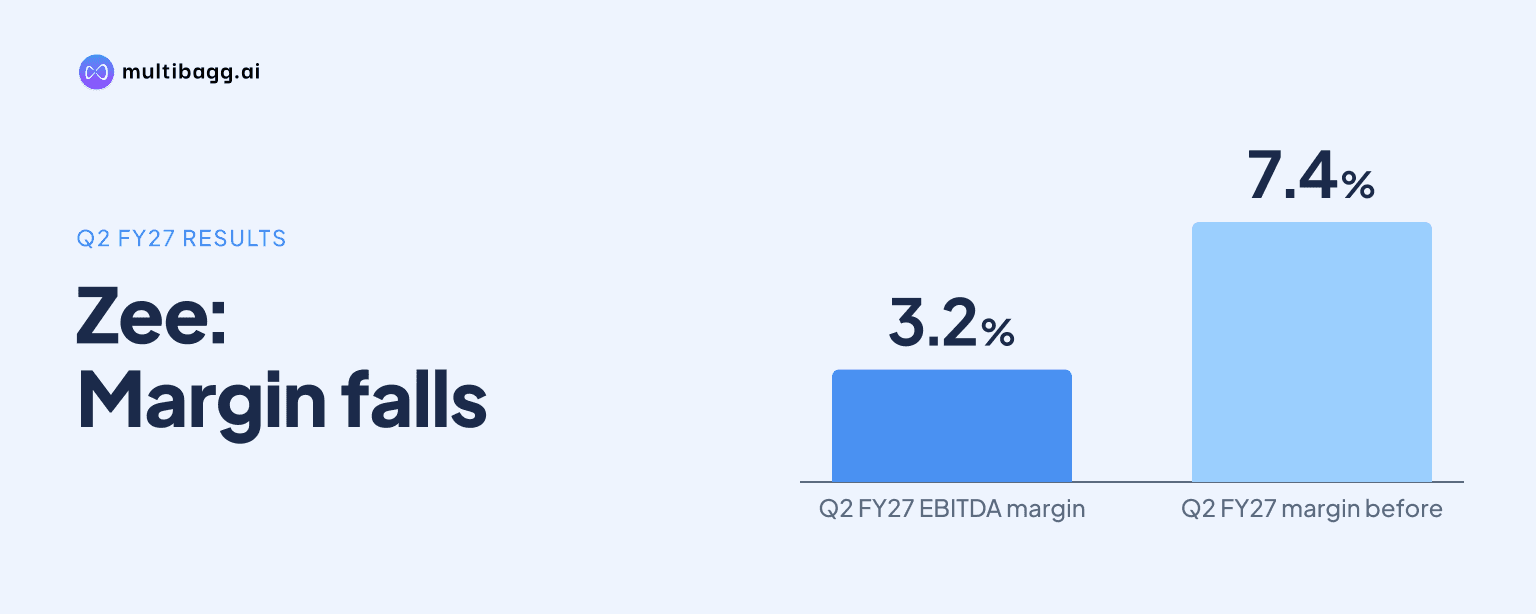
Zee Entertainment Enterprises Limited reported Q2 FY27 operating revenue growth of 13% year on year to Rs 2,224.6 crore, led by a 30% increase in subscription revenue. However, expenditure rose 18% to Rs 2,153.8 crore, causing earnings before interest, tax, depreciation and amortisation (EBITDA) to fall 52% to Rs 70.8 crore and the EBITDA margin to decline to 3.2% from 7.4%.
Know Zee Entertainment Enterprises inside out
Results, valuation, peers and who's buying, in one view.
Why did Zee’s EBITDA margin fall in Q2 FY27?
Zee’s EBITDA margin fell because its 18% increase in expenditure exceeded the 13% increase in operating revenue, while programming, advertising and promotion spending rose for FIFA 2026 and strategic initiatives. EBITDA declined 52% year on year to Rs 70.8 crore in Q2 FY27 from Rs 146.4 crore in Q2 FY26, despite revenue increasing by Rs 255.4 crore.
The quarter also showed sequential pressure on profitability. Revenue rose 17% from Rs 1,907.3 crore in Q1 FY27 to Rs 2,224.6 crore in Q2 FY27, but EBITDA declined 10% from Rs 78.9 crore. The EBITDA margin therefore moved from 4.1% in Q1 FY27 to 3.2% in Q2 FY27, following a 7.4% margin in the comparable prior-year quarter.
Profit after tax fell 40% year on year to Rs 45.6 crore and 39% sequentially from Rs 74.3 crore. Profit before tax declined 45% from Rs 115.4 crore in Q2 FY26 to Rs 63.1 crore, while other income decreased from Rs 26.4 crore to Rs 22.6 crore. Finance cost declined to Rs 2.5 crore from Rs 13 crore, but that reduction did not offset the rise in expenditure.
Which revenue streams drove Zee’s Q2 FY27 growth?
Subscription was Zee’s principal growth driver, rising 30% year on year to Rs 1,332.4 crore in Q2 FY27, while advertising remained flat at Rs 803 crore. Subscription also increased 17% from Rs 1,136.9 crore in Q1 FY27, making it the largest contributor to the Rs 317.3 crore sequential increase in operating revenue.
Management attributed subscription growth to FIFA 2026 and a strong content pipeline, which it said supported higher digital average revenue per user (ARPU) and subscriber growth. The presentation did not disclose subscriber numbers, ARPU amounts or FIFA 2026’s specific revenue contribution, but identified those factors as drivers of the increase.
Advertising revenue of Rs 803 crore was slightly below Rs 806.3 crore in Q2 FY26, although it rose 20% from Rs 671.4 crore in Q1 FY27. Management said domestic advertising was flat, aided by FIFA, marquee shows including Sa Re Ga Ma Pa and fresh programme launches. It also said the upcoming festive season would aid advertising-revenue growth.
Other sales and services declined 36% year on year to Rs 89.2 crore from Rs 139.9 crore. It also fell 10% sequentially from Rs 99 crore. Management linked the decline to a lower number of movies produced and released, meaning subscription growth offset reduced revenue in this category rather than growth across every revenue line.
Got a follow-up? Ask IRIS
How much did Zee’s Q2 FY27 costs increase?
Zee’s operating expense category increased to Rs 1,224.7 crore in Q2 FY27 from Rs 1,078 crore a year earlier, while advertising and promotion (A&P) expense rose 55% to Rs 571 crore. Total expenditure reached Rs 2,153.8 crore, up Rs 331 crore from Q2 FY26, exceeding the Rs 255.4 crore increase in revenue.
Management said programming expenses increased because of FIFA 2026 and an expanded content offering across platforms. Operating expense rose from Rs 1,031.7 crore in Q1 FY27 to Rs 1,224.7 crore in Q2 FY27, a sequential increase of Rs 193 crore and the largest absolute movement among the reported cost categories.
A&P expense increased from Rs 369.1 crore in Q2 FY26 and Rs 446.8 crore in Q1 FY27 to Rs 571 crore. Management attributed the higher spending to FIFA 2026 and investments in Bullet and Music. Zee also said it would continue to selectively invest in growth initiatives including KidZ, Bullet and Live.
Personnel cost moved in the opposite direction, decreasing 8% year on year to Rs 197.7 crore from Rs 214.2 crore and falling from Rs 212.6 crore in Q1 FY27. Other expenses were nearly unchanged from a year earlier at Rs 160.4 crore versus Rs 161.5 crore, but increased from Rs 137.3 crore sequentially. The reported rise in expenditure was therefore concentrated in programming-related and A&P costs.
What does the first half show about Zee’s profitability?
Zee’s H1 FY27 operating revenue rose 9% to Rs 4,131.9 crore, but EBITDA fell 60% to Rs 149.7 crore and margin declined to 3.6% from 9.9% in H1 FY26. The half-year figures show that Q2’s margin compression followed a broader first-half increase in expenditure.
Subscription revenue grew 23% in H1 FY27 to Rs 2,469.3 crore, while advertising revenue declined 6% to Rs 1,474.4 crore and other sales and services fell 16% to Rs 188.2 crore. Management said the Middle East crisis affected the advertising environment and that investments in new initiatives lowered profitability. This differs from Q2, when advertising was flat year on year and subscription grew 30%.
H1 expenditure increased 16% to Rs 3,982.2 crore, compared with 9% operating-revenue growth. A&P expense rose to Rs 1,017.8 crore from Rs 644.3 crore, while operating expense increased to Rs 2,256.4 crore from Rs 2,049 crore. Personnel cost declined to Rs 410.3 crore from Rs 434.3 crore, but this reduction was smaller than the increases in operating and A&P expense.
H1 profit after tax declined 46% to Rs 119.9 crore from Rs 220.2 crore, while profit before tax fell 56% to Rs 137.2 crore. In Q2 FY27, Zee’s international operations reported advertising revenue of Rs 44.7 crore, subscription revenue of Rs 118.9 crore and other sales and services revenue of Rs 15.1 crore. The presentation did not provide comparable international revenue or profitability figures.
Conclusion
Zee’s Q2 FY27 revenue mix was led by subscription, whose Rs 1,332.4 crore contribution offset flat advertising revenue and lower movie-related sales and services. Yet the revenue increase did not translate into higher operating profit because expenditure grew faster, with FIFA 2026 content costs and A&P spending on FIFA, Bullet and Music contributing to the lower margin.
The next factors to watch are management’s expectation that the festive season will aid advertising revenue and its continued selective investment in KidZ, Bullet and Live. The presentation identifies FIFA 2026, the content pipeline, digital ARPU and subscriber growth as subscription drivers, while leaving the scale, timing and returns of those investments undisclosed.