










3C IT Solutions swings to Rs 84.70 lakh first-half loss
Key highlights
- 3C IT Solutions reported an Rs 84.70 lakh loss for the half year ended September 30, 2026, against an Rs 14.04 lakh profit a year earlier.
- Revenue from operations doubled to Rs 42.6701 crore from Rs 21.1937 crore in the corresponding 2025 half year.
- Purchases of stock-in-trade rose to Rs 43.7326 crore from Rs 18.3638 crore.
- Cash and cash equivalents increased to Rs 78.37 lakh at September 30, 2026 from Rs 46.14 lakh at March 31, 2026.
powered by IRIS
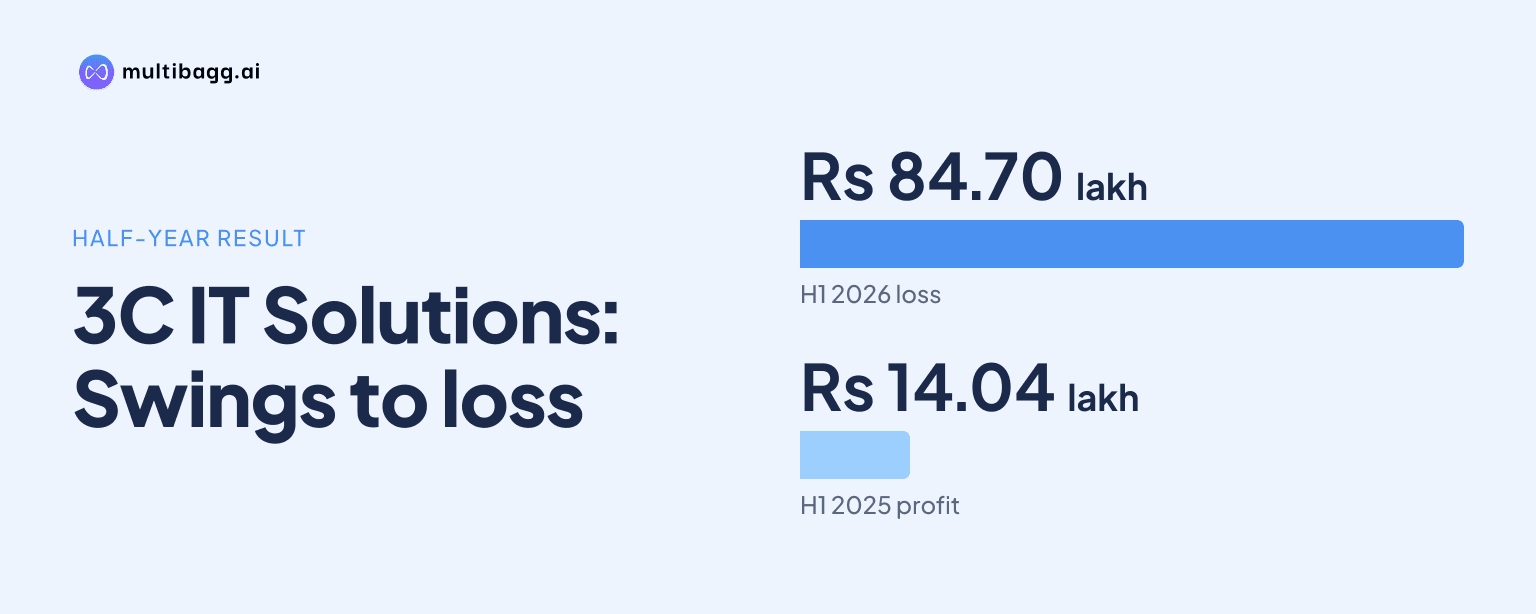
3C IT Solutions & Telecoms (India) Limited reported an Rs 84.70 lakh net loss for the half year ended September 30, 2026, against an Rs 14.04 lakh profit a year earlier, although revenue from operations doubled to Rs 42.6701 crore. Higher stock-in-trade purchases, employee costs and other expenses exceeded the increase in income.
Know 3C IT Solutions & Telecoms (India) inside out
Results, valuation, peers and who's buying, in one view.
What did 3C IT Solutions report for the September 2026 half year?
3C IT Solutions reported total income of Rs 42.8522 crore for the half year ended September 30, 2026, compared with Rs 21.1941 crore in the corresponding half year of 2025. Revenue from operations accounted for Rs 42.6701 crore, up from Rs 21.1937 crore, while other income rose to Rs 18.21 lakh from Rs 0.04 lakh.
The increase in sales did not produce a profit because total expenses reached Rs 43.6314 crore, compared with Rs 21.1267 crore in the previous-year half. This left a pre-tax loss of Rs 77.92 lakh, reversing a pre-tax profit of Rs 6.73 lakh in the comparable period. After a deferred-tax charge of Rs 6.78 lakh, the loss from continuing operations was Rs 84.70 lakh.
Basic and diluted earnings per share were both a loss of Rs 1.41 for continuing operations and total operations, against earnings of Rs 0.23 a year earlier. The company reported no exceptional items, extraordinary items or discontinuing operations in either half-year period. Its results were standalone and unaudited, with a limited review completed by the statutory auditor.
Why did 3C IT Solutions make a loss despite higher revenue?
3C IT Solutions made a loss because the Rs 25.3688 crore increase in purchases of stock-in-trade was greater than the Rs 21.4764 crore increase in revenue from operations. Purchases reached Rs 43.7326 crore in the September 2026 half from Rs 18.3638 crore a year earlier, while the expense line for changes in inventories was negative Rs 3.6603 crore, compared with a positive Rs 30.02 lakh cost previously.
Employee benefits expense increased to Rs 1.9787 crore from Rs 1.4592 crore, and other expenses rose to Rs 1.2538 crore from Rs 58.28 lakh. Finance costs increased to Rs 17.13 lakh from Rs 5.26 lakh. These increases were partly offset by depreciation and amortisation falling to Rs 15.54 lakh from Rs 36.82 lakh, but that reduction did not prevent total expenses from exceeding total income.
The tax position also differed between the two half years. The latest period had no current-tax expense and recorded deferred tax of Rs 6.78 lakh, taking the pre-tax loss of Rs 77.92 lakh to an Rs 84.70 lakh loss. In the September 2025 half, current tax was Rs 1.69 lakh and deferred tax was negative Rs 9 lakh, contributing to a final Rs 14.04 lakh profit.
Got a follow-up? Ask IRIS
How did 3C IT Solutions’ balance sheet change by September?
3C IT Solutions’ total assets increased to Rs 39.8988 crore at September 30, 2026 from Rs 38.5687 crore at March 31, 2026. Current assets rose to Rs 39.4021 crore from Rs 37.9276 crore, while non-current assets declined to Rs 49.67 lakh from Rs 64.12 lakh, primarily alongside lower property, plant and equipment.
Inventories increased to Rs 7.0839 crore from Rs 3.4235 crore during the six-month period. Trade receivables fell to Rs 29.2892 crore from Rs 32.9494 crore, while short-term loans and advances rose to Rs 2.1925 crore from Rs 97.20 lakh. Cash and cash equivalents increased to Rs 78.37 lakh from Rs 46.14 lakh.
Shareholders’ funds declined to Rs 12.4358 crore from Rs 13.2828 crore, matching the effect of the Rs 84.70 lakh reported loss on reserves and surplus. Share capital remained Rs 3.01 crore, while reserves and surplus decreased to Rs 9.4258 crore from Rs 10.2728 crore. Long-term borrowings increased to Rs 38.93 lakh from Rs 34.26 lakh, whereas short-term borrowings fell to nil from Rs 7.50 lakh.
Trade payables to micro and small enterprises increased to Rs 1.915 crore from Rs 4.90 lakh. Payables to creditors other than micro and small enterprises increased to Rs 24.7001 crore from Rs 24.2941 crore. Total current liabilities were Rs 27.0735 crore at September 30, compared with Rs 24.9433 crore at March 31.
What did 3C IT Solutions’ cash flow and auditor review show?
3C IT Solutions generated Rs 57.31 lakh of net cash from operating activities in the period ended September 30, 2026 despite its Rs 84.70 lakh net loss. Under the indirect cash-flow method, operating profit before working-capital changes was a negative Rs 54.76 lakh. A Rs 3.6602 crore reduction in trade receivables and a Rs 2.272 crore increase in trade payables supported operating cash generation.
Those movements were partly offset by a Rs 3.6603 crore increase in inventories and a Rs 1.2206 crore increase in short-term loans and advances. Investing activities used Rs 5.10 lakh, including Rs 8.08 lakh spent on fixed assets, partly offset by Rs 2.92 lakh from deletion of fixed assets. Financing activities used Rs 19.96 lakh, including Rs 17.13 lakh in finance-cost payments and Rs 7.50 lakh in net repayment of short-term borrowings.
Net cash increased by Rs 32.24 lakh in the half year, taking cash and cash equivalents to Rs 78.37 lakh at September 30, 2026. In comparison, the full year ended March 31, 2026 recorded a net cash decrease of Rs 28.36 lakh. The cash-flow statement was prepared under Accounting Standard 3, which sets out the indirect method used in the filing.
CMRS and Associates LLP stated in its November 14, 2026 limited-review report that nothing had come to its attention to indicate that the unaudited results were materially misstated under the applicable accounting framework. However, the auditor said management had not provided a statement for a bank balance of Rs 53,159 as at September 30, 2026, and it was therefore unable to verify that balance. The board approved the results on November 14, 2026.
Conclusion
3C IT Solutions paired a doubling of first-half revenue with a reversal from an Rs 14.04 lakh profit to an Rs 84.70 lakh loss. The reported cost increase was concentrated in Rs 43.7326 crore of stock-in-trade purchases, alongside higher employee benefits, finance costs and other expenses, while working capital shifted through higher inventory and trade payables.
The unresolved matter disclosed in the filing is the auditor’s inability to verify the Rs 53,159 bank balance because the related statement was not supplied by management. The next reported balance-sheet changes in inventories of Rs 7.0839 crore, receivables of Rs 29.2892 crore and trade payables of Rs 26.6151 crore will also show how the first-half working-capital movements develop.