










Aditya Infotech Limited raises FY27 outlook, retains margin goal
Key highlights
- Aditya Infotech raised FY2027 revenue guidance to Rs 6,500 crore-Rs 6,800 crore from Rs 6,000 crore-Rs 6,500 crore.
- Aditya Infotech reported H1 FY2027 revenue of Rs 3,148 crore, up 89.7% year-on-year, with a 16.3% EBITDA margin.
- Aditya Infotech retained 14%-15% FY2027 EBITDA-margin guidance despite a 17.6% Q2 margin.
- Aditya Infotech expects FY2027 market share of 43%-45%, compared with about 42% in the 12 months to September 2026.
powered by IRIS
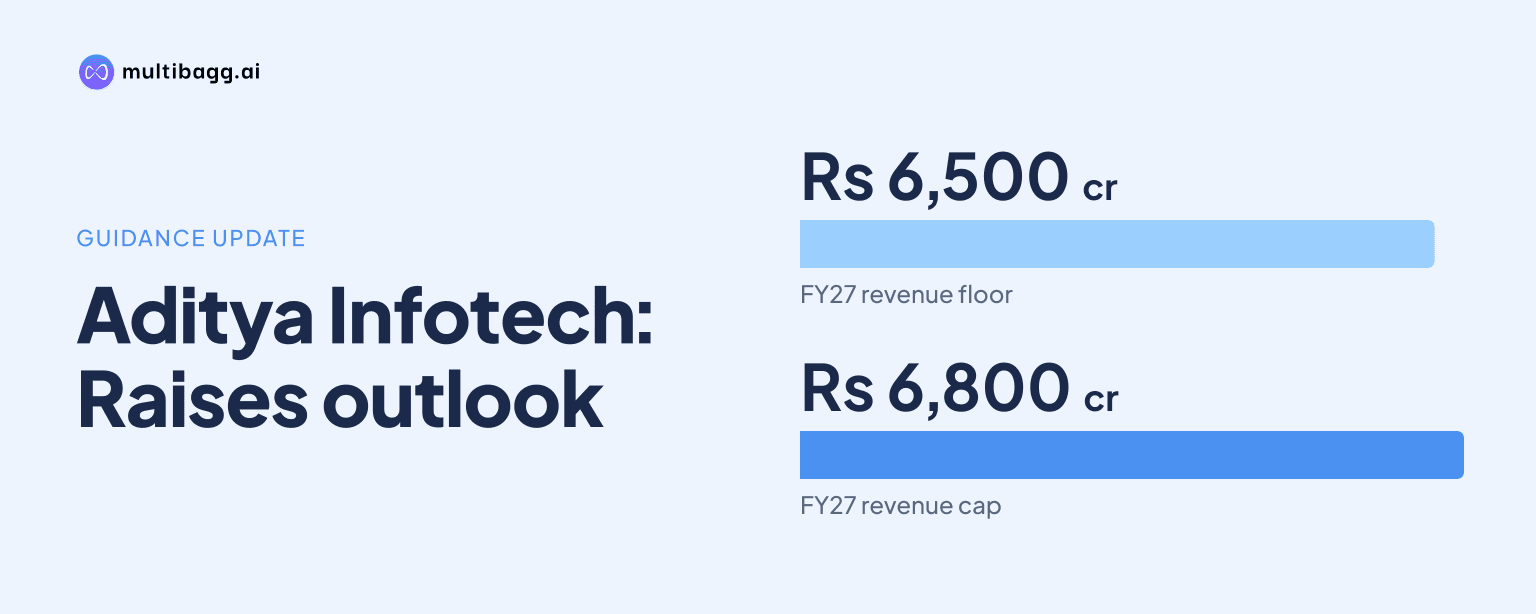
Aditya Infotech Limited raised FY2027 revenue guidance to Rs 6,500 crore-Rs 6,800 crore after H1 revenue increased 89.7% year-on-year to Rs 3,148 crore, while retaining its 14%-15% earnings before interest, tax, depreciation and amortisation (EBITDA) margin target because higher semiconductor costs and measured price increases are expected to reduce second-half margins from Q2 levels.
Know Aditya Infotech inside out
Results, valuation, peers and who's buying, in one view.
Why did Aditya Infotech raise FY27 revenue guidance?
Aditya Infotech raised its FY2027 revenue outlook because H1 sales growth surpassed the pace implied by its earlier forecast. Management lifted the guidance range to Rs 6,500 crore-Rs 6,800 crore from Rs 6,000 crore-Rs 6,500 crore, implying annual revenue growth of 54%-61%. The new lower end equals the upper end of the earlier range, while the upper end is Rs 300 crore higher.
H1 revenue reached Rs 3,148 crore, up 89.7% year-on-year, and EBITDA was Rs 515 crore, producing a 16.3% margin. Q2 revenue was Rs 1,746 crore, up 89.9% year-on-year and 24.5% sequentially from Q1. Q2 EBITDA rose 177% year-on-year to Rs 307 crore, while the margin increased to 17.6% from 14.8% in Q1.
Management said the nearly 90% H1 revenue growth was partly aided by a soft base in the previous year, when STQC certification backlogs constrained supply across the industry. It said the second half of the previous year had a normal base, so revenue growth should moderate from H1 levels even as Aditya Infotech pursues the revised full-year range.
Why is Aditya Infotech retaining its EBITDA-margin target?
Aditya Infotech retained its 14%-15% FY2027 EBITDA-margin target because management expects H2 margins to be below Q2's 17.6%. The company reported a 16.3% H1 margin, but management said Q2 should not be read as the full-year run rate amid a volatile environment for system-on-chip, or SOC, memory and flash components.
H1 gross margin was 30.4%, up 374 basis points year-on-year, supported by a richer product and brand mix, localisation and operating leverage. Q2 gross margin was 30.0%, flat year-on-year and below Q1's 30.8%, as Aditya Infotech started absorbing part of the higher input cost for SOC and memory components.
The company built strategic inventory of SOC and memory components to protect supply and margins in H1. Management expects the effect of higher component costs to become more visible as lower-cost inventory is consumed. It also plans to stagger price increases rather than pass through all cost inflation immediately, in order to preserve room for market-share expansion.
An analyst calculated that the annual guidance could imply H2 EBITDA margin of about 13%. Management did not confirm that calculation, saying it was maintaining a cushion for execution and market-share strategy. It added that benefits from backward integration should principally accrue in the next financial year because the housing facility and cable venture are scheduled to begin operations in Q4 FY2027.
Got a follow-up? Ask IRIS
How is Aditya Infotech seeking further market-share growth?
Aditya Infotech expects to reach a 43%-45% market share by the end of FY2027, compared with about 42% in the 12 months to September 2026 and 30% at the time of its initial public offering. Management linked this expansion to trusted supply-chain requirements, manufacturing scale, research and development, and national distribution reach.
CP PLUS was the principal revenue contributor, accounting for about 88% of Q2 revenue compared with 86% a year earlier. Within CP PLUS, internet protocol products represented about 79% of the portfolio, up from 71%. This shift toward IP products accompanied Q2 revenue of Rs 1,746 crore and EBITDA of Rs 307 crore.
The company is using a multi-brand strategy across price segments. CP PLUS remains the flagship mainstream brand, while CP PLUS PRO is planned for a premium-enterprise rollout in Q4 FY2027. Management said NEXIVUE, introduced around April, had shown initial movement, while EYRA's first products were expected to reach the market by the end of November or in December.
Management said the online portal listed more than 40 STQC-certified brands, but it had not observed significant new competitive traction or consistent supply on the ground. Its pricing plan is to retain a competitive cushion by moderating and staggering increases, rather than indicating that demand had already weakened following price rises.
What capacity, localisation and technology plans support Aditya Infotech?
Aditya Infotech plans to more than double its Kadapa manufacturing capacity of 2.5 million units a month through Kadapa Phase 3 and a new Greater Noida facility. The company completed a Rs 1,500 crore qualified institutions placement in September, with proceeds earmarked for debt repayment, capacity expansion through AIL Dixon, acquisitions and general corporate purposes.
At September 30, cash and cash equivalents stood at Rs 1,434 crore against borrowings of Rs 363 crore. Management said it repaid all borrowings in October and became debt free. It expects lower finance costs to be visible in H2 after finance cost declined 41% year-on-year during H1.
Localisation projects are intended to improve supply security, quality and margins over time, rather than offset H2 component inflation immediately. The planned Greater Noida lens plant will have capacity of 2 million lenses a month. The Kadapa housing and enclosures facility was due to begin trials in the current quarter and commercial production in the following quarter, while the cable plant was scheduled to go live in Q4 FY2027.
Aditya Infotech also signed agreements to invest Rs 45.4 crore for a 30% fully diluted stake in BLUE KGraph AI Solutions, subject to customary conditions. Management said BLUE's compression technology can reduce storage and bandwidth by up to 90%, requires no graphics processing unit and works with installed cameras. It described the investment as a technology capability build for cloud storage and analytics, rather than a near-term standalone revenue contributor.
Conclusion
The revised Rs 6,500 crore-Rs 6,800 crore revenue target reflects the scale of H1 sales growth, CP PLUS's 88% contribution to Q2 revenue and management's aim to reach 43%-45% market share by FY2027 end. Retaining the 14%-15% EBITDA-margin target shows that management expects input-cost pressures and deliberate price moderation to outweigh the 16.3% margin achieved in H1.
The next disclosures to watch are the Q4 FY2027 launch of CP PLUS PRO, the cable plant's planned Q4 start and commercial production at the housing and enclosures facility in the following quarter. Management also expects working capital to decline as strategic component inventory is used; receivable days had already fallen to 87 in Q2 from 93 in Q1 and 105 a year earlier.