










Aditya Infotech raises FY27 outlook as Q2 revenue jumps
Key highlights
- Aditya Infotech reported Q2 FY27 revenue of Rs 1,746.0 crore, up 89.9% year on year.
- Q2 FY27 EBITDA was Rs 307.4 crore, up 176.7%, and EBITDA margin increased 552 basis points to 17.6%.
- Aditya Infotech raised FY27 revenue guidance to Rs 6,500-6,800 crore.
- Net cash was Rs 1,071.2 crore at September 30, 2026, and all borrowings were repaid in October 2026.
powered by IRIS
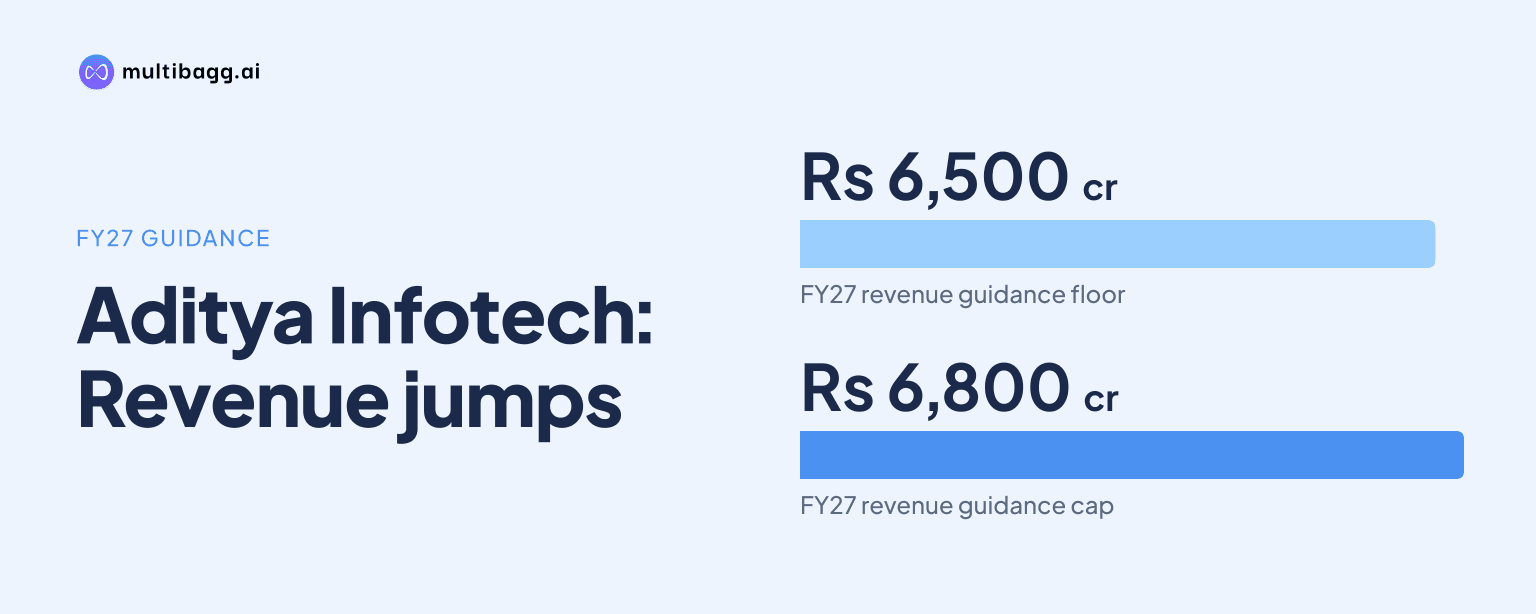
Aditya Infotech Limited raised its FY27 revenue guidance to Rs 6,500-6,800 crore after Q2 FY27 revenue rose 89.9% year on year to Rs 1,746.0 crore and EBITDA margin reached 17.6%. The company reported EBITDA growth of 176.7% and attributed the margin increase to product mix, localisation and operating leverage.
Know Aditya Infotech inside out
Results, valuation, peers and who's buying, in one view.
What did Aditya Infotech report for Q2 FY27?
Aditya Infotech reported Q2 FY27 revenue of Rs 1,746.0 crore, up 89.9% year on year, while earnings before interest, tax, depreciation and amortisation (EBITDA) rose 176.7% to Rs 307.4 crore. EBITDA margin expanded by 552 basis points to 17.6% for the quarter ended September 30, 2026. Profit after tax (PAT) before exceptional item increased 214.2% year on year to Rs 219.9 crore, with a 12.6% margin, up 499 basis points.
Profit growth exceeded revenue growth in Q2 FY27, with revenue up 89.9%, EBITDA up 176.7% and PAT before exceptional item up 214.2%. Aditya Infotech attributed the result to favourable product and brand mix, operating efficiencies and a 14% year-on-year reduction in finance cost. Gross margin was 30.0%, 24 basis points higher than in Q2 FY26.
How did Aditya Infotech perform in H1 FY27?
Aditya Infotech generated H1 FY27 revenue of Rs 3,148.4 crore, up 89.7% year on year, and EBITDA of Rs 515.2 crore, up 192.7%. H1 EBITDA margin was 16.3%, up 576 basis points from the prior-year period. PAT before exceptional item rose 252.0% to Rs 362.1 crore, while its margin increased 530 basis points to 11.5%.
H1 FY27 gross margin was 30.4%, 374 basis points above the previous year and 0.4 percentage points above the 30.0% recorded in Q2 FY27. In contrast, the 16.3% H1 EBITDA margin was 1.3 percentage points below Q2's 17.6%. Aditya Infotech said the H1 result reflected a 41.1% year-on-year reduction in finance cost and cost efficiencies.
What drove Aditya Infotech's Q2 revenue mix and margins?
Aditya Infotech said its CP PLUS brand contributed about 88% of overall Q2 FY27 revenue, compared with about 86% in Q2 FY26. Internet protocol (IP) products accounted for about 79% of the CP PLUS portfolio, compared with about 71% a year earlier. The company linked the greater IP-product share and CP PLUS contribution to the favourable mix supporting its 17.6% Q2 EBITDA margin.
The company also cited increased localisation and operating leverage in explaining the 552-basis-point EBITDA-margin increase. Its stated offering includes video-security and surveillance products, technologies and solutions for enterprise and consumer customers under CP PLUS, alongside integrated security systems and Security-as-a-Service. The release did not disclose separate quarterly revenue or margin figures for those services in the period ended September 30, 2026.
Aditya Infotech estimated its share of India's video-surveillance market at about 42% in the 12 months to September 2026, compared with 30% at its initial public offering. This 12-percentage-point change is a company estimate. Management said capacity expansion, research and development investment, and distribution growth supported CP PLUS's premium positioning.
Got a follow-up? Ask IRIS
What is Aditya Infotech's revised FY27 guidance?
Aditya Infotech revised FY27 guidance upwards to revenue of Rs 6,500-6,800 crore, an EBITDA margin of 14.0-15.0%, and a PAT margin of 9.0-10.0%. Managing Director Aditya Khemka said the revision was supported by favourable industry dynamics and continued business momentum. The November 5, 2026 release did not disclose the earlier revenue or margin guidance.
The guided EBITDA-margin range of 14.0-15.0% is below the 16.3% delivered in H1 FY27 and the 17.6% reported for Q2 FY27. The 9.0-10.0% PAT-margin range is also below the reported PAT-before-exceptional-item margins of 11.5% for H1 and 12.6% for Q2. These are management targets rather than reported financial results.
Aditya Infotech reported net cash of Rs 1,071.2 crore as at September 30, 2026, following a Rs 1,500 crore qualified institutional placement (QIP). The company said all borrowings were repaid in October 2026. It intends to use QIP proceeds for debt repayment, capital expenditure, inorganic growth through acquisitions and general corporate purposes.
How is Aditya Infotech expanding capacity and technology capabilities?
Aditya Infotech has manufacturing capacity of 2.5 million units a month and plans to more than double it through Kadapa Phase III and a new Greater Noida facility. The company said these projects will be funded from QIP proceeds. The release did not specify commissioning dates or the capacity contribution of either project.
On November 5, 2026, Aditya Infotech signed definitive agreements to invest Rs 45.4 crore for a 30% fully diluted stake in BLUE, also known as KGraph AI Solutions Pvt Ltd. BLUE is a video-compression technology company. Completion remains subject to customary conditions, and Aditya Infotech expects to receive one board seat and one observer seat.
The company also rolled out a CP PLUS advertising campaign featuring Ranveer Singh during the festive season and expanded branding across Indian cricket and major Indian airports. Management said the campaign was intended to broaden brand reach and build awareness of intelligent security. The release gave no marketing expenditure or campaign-return figures.
Conclusion
Aditya Infotech reported sharply faster growth in EBITDA and PAT before exceptional item than in revenue during Q2 FY27, alongside a 17.6% EBITDA margin and higher CP PLUS and IP-product contributions. Its H1 results showed revenue of Rs 3,148.4 crore and EBITDA of Rs 515.2 crore, while management raised FY27 revenue guidance to Rs 6,500-6,800 crore.
The next disclosed matters to watch are progress on more than doubling the 2.5 million-unit monthly manufacturing capacity through Kadapa Phase III and Greater Noida, and completion of the Rs 45.4 crore BLUE transaction. Management's FY27 targets of 14.0-15.0% EBITDA margin and 9.0-10.0% PAT margin remain forward-looking targets.