










Aether lifts Baker Hughes opportunity to Rs 750-800 crore
Key highlights
- Aether raised its stated Baker Hughes opportunity to Rs 750-800 crore from the original Rs 400 crore pour-point-depressant programme.
- Aether said it had begun shipping additional mature oilfield chemicals for Baker Hughes in Q2.
- Aether said the added Baker Hughes products use a modified Strata line and require no capital expenditure beyond the original site outlay.
- Management expects Strata asset turns of 3-3.5 times at maturity.
powered by IRIS
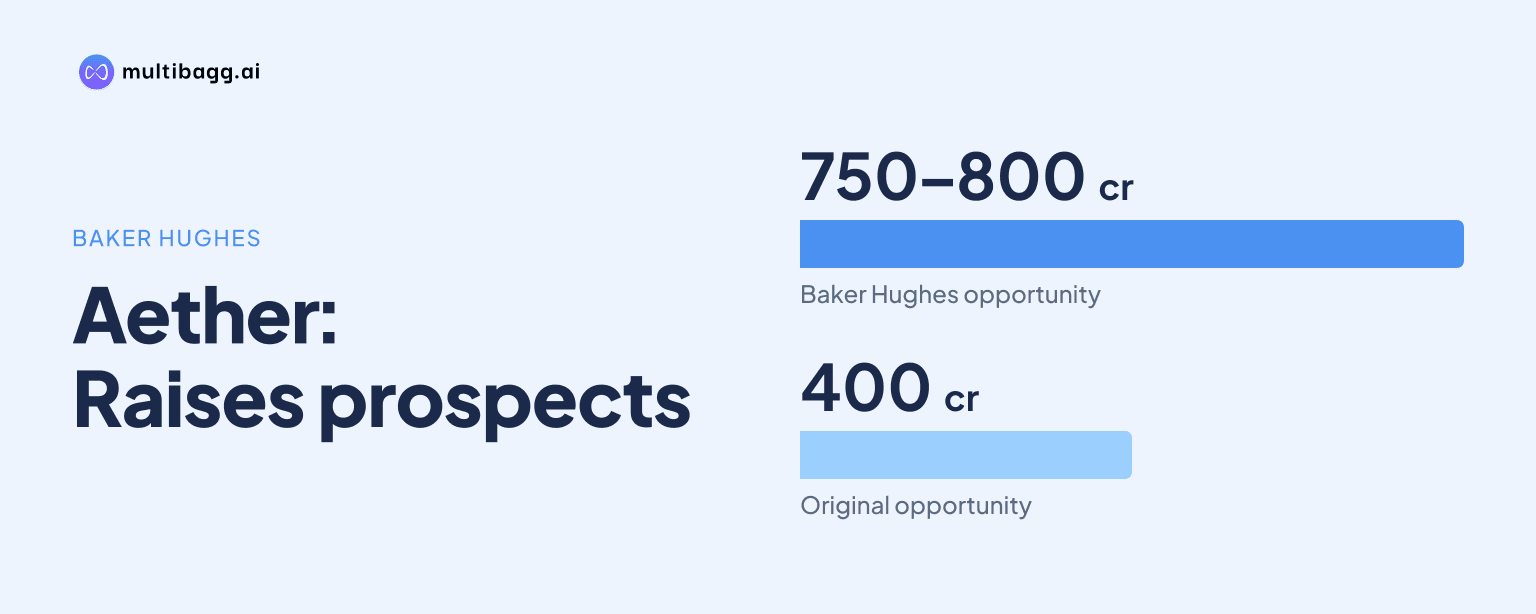
Aether Industries Limited said on October 30, 2026, that its Baker Hughes opportunity had risen to Rs 750-800 crore from the original Rs 400 crore pour-point-depressant programme, after it began shipping additional oilfield-chemical products from a modified Strata production line without additional capital expenditure.
Know Aether Industries inside out
Results, valuation, peers and who's buying, in one view.
How much has Aether’s Baker Hughes opportunity increased?
Aether said the Baker Hughes opportunity is now Rs 750-800 crore, compared with the original Rs 400 crore opportunity for pour point depressants. Management said the newly introduced products represent another potential market of about Rs 400 crore, expanding the relationship through a second product stream.
The figures are market-potential estimates rather than a disclosed sales forecast or order book. Management said the original Rs 400 crore opportunity covered pour point depressants, while the added products take the combined opportunity to Rs 750-800 crore as of the October 30, 2026 call.
Management also said it was working towards more than Rs 1,000 crore of business with Baker Hughes in the near future. That figure was presented as a relationship target, not as contracted annual revenue, and Aether did not disclose a timetable, product volumes or current revenue from Baker Hughes.
What are the additional Baker Hughes products?
Aether said the additional products are mature oilfield chemicals that Baker Hughes had sourced from Singapore and that Aether is now manufacturing in India for the first time. Management said it had already started shipping the products in Q2, moving the programme from development into supply.
Aether did not name the new products or identify the precise Baker Hughes facility being replaced. It said the opportunity is linked to drilling activity in the oil-and-gas sector through the Baker Hughes ecosystem, while the original programme remains focused on pour point depressants.
The distinction between the two product sets explains the expansion from Rs 400 crore to Rs 750-800 crore. The original product stream and the newly shipped products serve the same strategic customer, but management described them as separate opportunities rather than a revision to the initial pour-point-depressant estimate.
Does Aether need new Strata capex for Baker Hughes?
Aether said no new capital expenditure is required for the additional Baker Hughes products because they are covered by the original Strata-site outlay. The company said it modified one production line at Site 4, called Strata, instead of building a new dedicated production block.
This approach differs from the capacity projects under discussion at Site Magnum, where management described several prospective dedicated blocks. At Strata, the mechanism is a production-line modification within existing capacity, and the additional products have already begun shipping from that site.
The absence of incremental disclosed capex is central to management’s explanation of the larger Rs 750-800 crore opportunity. Aether did not disclose the cost of the line modification, the original Strata capital base, or the share of Strata capacity assigned to Baker Hughes.
Got a follow-up? Ask IRIS
What asset turns does Aether expect at Strata?
Aether said it expects Strata to reach asset turns of 3-3.5 times at maturity, above an analyst’s estimate of 2.5-3 times. Management linked that range to production streams maturing at the site, including the expanded Baker Hughes product portfolio.
The call did not provide current Strata utilisation, current asset turns, annual product volumes or a date for achieving the 3-3.5-times range. The metric is therefore a management expectation for a mature production configuration, rather than a reported operating result for Q2.
Aether’s wider capex outlook provides context for using already planned capacity. Management said FY27 capital expenditure should be about Rs 350-370 crore, as substantial civil work had already been completed on several blocks, including at Site Magnum.
How does Baker Hughes fit into Aether’s wider plan?
Aether identified Baker Hughes as a strategic partner alongside Milliken and said it had 10 other such relationships. Management said it screens opportunities for fit with its core chemistries and technologies, while excluding hydrogen fluoride, fluorine and hydrogen sulphide chemistry from its operating scope.
At Site Magnum, management described two pharmaceutical advanced-intermediate plants, one semiconductor plant, one agrochemical-innovator plant and a 1,000-tonnes-a-year material-sciences plant under discussion. These projects are separate from the Strata line modified for Baker Hughes, so the Baker Hughes expansion does not require a newly disclosed Magnum block.
Management said semiconductor products could generate Rs 300-400 crore of revenue at maturity in the next two to 2.5 years, which it described as 2029. That timeline contrasts with Baker Hughes, where Aether said shipments of the added products had already started from Strata in Q2.
Conclusion
The Baker Hughes expansion increases Aether’s stated opportunity from Rs 400 crore for pour point depressants to Rs 750-800 crore by adding a second set of mature oilfield chemicals. Management’s central point is that these products are being supplied through a modified Strata line using the site’s original capital expenditure, rather than through a new dedicated block.
Investors can next watch the shipment ramp from the modified Strata line and progress towards management’s stated target of more than Rs 1,000 crore of Baker Hughes business. Other disclosed milestones include FY27 capex of about Rs 350-370 crore and management’s expectation that approximately Rs 400 crore of Site 5 construction-in-progress will be capitalised by the end of the financial year.