










Akiko Q2 revenue rises 138% to ₹83.22 crore, margin 15.34%
Key highlights
- Akiko reported Q2 FY27 revenue of ₹83.22 crore, up 138.1% year on year.
- Q2 FY27 EBITDA rose 156.3% to ₹12.77 crore and EBITDA margin reached 15.34%.
- Q2 FY27 PAT increased 101.8% to ₹8.41 crore, while PAT margin was 10.10%.
- H1 FY27 revenue was ₹151.34 crore and PAT was ₹15.42 crore for the six months ended 30 September 2026.
powered by IRIS
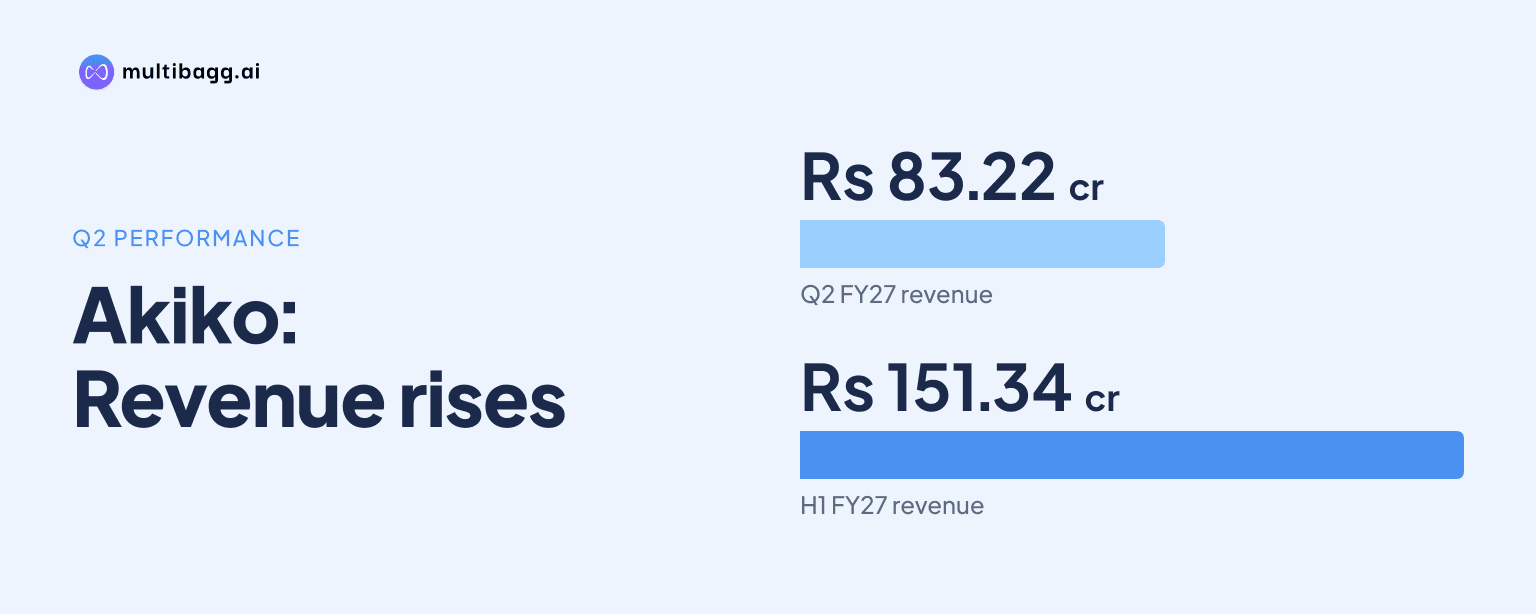
Akiko Global Services Limited reported Q2 FY27 revenue of ₹83.22 crore, up 138.1% year on year, while earnings before interest, tax, depreciation and amortisation (EBITDA) rose 156.3% to ₹12.77 crore and EBITDA margin reached 15.34%. Profit after tax (PAT) increased 101.8% to ₹8.41 crore, as finance costs and tax expense rose faster than revenue.
Know Akiko Global Services inside out
Results, valuation, peers and who's buying, in one view.
How did Akiko’s Q2 FY27 revenue and profit change?
Akiko’s Q2 FY27 revenue from operations was ₹83.22 crore, compared with ₹34.96 crore in Q2 FY26 and ₹68.12 crore in Q1 FY27. Revenue increased 138.1% year on year and rose ₹15.10 crore from Q1 FY27. The company’s Q2 revenue was therefore above both the comparable prior-year quarter and the immediately preceding quarter.
EBITDA increased to ₹12.77 crore from ₹4.98 crore in Q2 FY26 and ₹10.10 crore in Q1 FY27. PAT rose to ₹8.41 crore from ₹4.17 crore a year earlier and ₹7.02 crore in Q1 FY27. EBITDA’s ₹7.79 crore year-on-year increase was larger than PAT’s ₹4.24 crore increase, reflecting movements in costs outside the operating-profit measure.
Profit before tax reached ₹11.27 crore in Q2 FY27, up 156.9% from ₹4.39 crore in Q2 FY26. PAT attributable to owners rose 112.5% to ₹8.22 crore from ₹3.87 crore. Earnings per share (EPS) was ₹7.63, compared with ₹3.59 in Q2 FY26 and ₹6.40 in Q1 FY27.
Why did Akiko’s EBITDA margin improve in Q2 FY27?
Akiko’s EBITDA margin improved to 15.34% in Q2 FY27 from 14.25% in Q2 FY26 and 14.82% in Q1 FY27. The year-on-year improvement was 1.09 percentage points, while the sequential improvement was 0.52 percentage points. EBITDA grew 156.3% year on year, ahead of the 138.1% increase in revenue.
PAT margin declined despite the operating-margin increase. It was 10.10% in Q2 FY27, compared with 11.92% in Q2 FY26 and 10.30% in Q1 FY27. Akiko said that higher finance costs and a higher tax rate than in Q2 FY26 moderated the PAT margin.
Finance costs were ₹1.30 crore in Q2 FY27, up from ₹0.25 crore in Q2 FY26 and ₹0.46 crore in Q1 FY27. The effective tax rate was 25.37%, against 4.99% a year earlier, though below 26.90% in Q1 FY27. Tax expense reached ₹2.86 crore, compared with ₹0.22 crore in Q2 FY26 and ₹2.58 crore in Q1 FY27.
Got a follow-up? Ask IRIS
What do Akiko’s H1 FY27 results show?
Akiko reported revenue of ₹151.34 crore in H1 FY27, the six months ended 30 September 2026, up 134.7% from ₹64.49 crore in H1 FY26. EBITDA rose 151.0% to ₹22.86 crore from ₹9.11 crore, and PAT increased 149.4% to ₹15.42 crore from ₹6.18 crore. Both profit measures grew faster than revenue year on year.
The H1 FY27 result also approached the full-year FY26 base. H1 FY27 revenue was ₹21.39 crore below FY26 revenue of ₹172.73 crore, while EBITDA was ₹2.21 crore below FY26 EBITDA of ₹25.07 crore. PAT of ₹15.42 crore was ₹2.00 crore below the FY26 PAT of ₹17.42 crore.
H1 FY27 finance costs were ₹1.77 crore, up 481.4% from ₹0.30 crore in H1 FY26 and above ₹1.08 crore for all of FY26. Tax expense increased 189.8% to ₹5.44 crore from ₹1.88 crore. PAT attributable to owners rose 175.1% to ₹15.12 crore, while EPS increased to ₹14.04 from ₹5.10.
What changed in Akiko’s balance sheet and what is planned next?
Akiko’s total assets increased to ₹190.12 crore at 30 September 2026 from ₹107.54 crore at 31 March 2026. Trade receivables rose to ₹114.69 crore from ₹63.24 crore, while cash and bank balances increased to ₹19.81 crore from ₹3.29 crore. Total current assets reached ₹171.15 crore, compared with ₹96.40 crore at the March year-end.
Funding also increased during the period. Short-term borrowings rose to ₹64.53 crore at 30 September from ₹12.40 crore at 31 March, and long-term borrowings increased to ₹3.58 crore from ₹2.49 crore. Total shareholders’ funds rose to ₹75.24 crore from ₹59.98 crore, including reserves and surplus of ₹64.47 crore versus ₹48.78 crore.
Management expects required third-party application provider (TPAP) approval in early December 2026. After approval and integration, Akiko plans to roll out UPI Scan & Pay. Its stated next-phase priorities include completing verification, optimising onboarding, building repeat app usage and increasing productivity across credit cards, loans and financial partners.
Conclusion
Akiko’s Q2 FY27 results combined revenue growth to ₹83.22 crore with faster EBITDA growth and an EBITDA margin of 15.34%. The operating result did not translate into a comparable improvement in net margin: PAT margin was 10.10%, as Q2 finance costs reached ₹1.30 crore and the effective tax rate was 25.37%.
The next disclosed milestone is management’s expectation of TPAP approval in early December 2026, followed by UPI Scan & Pay integration and rollout. Investors can also monitor the development of short-term borrowings of ₹64.53 crore and trade receivables of ₹114.69 crore alongside Akiko’s payments, customer-activation and distribution priorities.