










Alkem chronic portfolio outpaced Indian pharma market by 640 basis points
Key highlights
- Alkem’s chronic portfolio grew 22.4% in Q2 FY27 versus 16.0% for the Indian pharmaceutical market.
- Alkem’s reported India sales rose 9.5% year on year to Rs 3,027.5 crore in Q2 FY27.
- Alkem launched 26 products in H1 FY27 and had about 14,500 medical representatives.
- Alkem had one brand family above Rs 1,500 crore in MAT September 2026, versus none five years earlier.
powered by IRIS
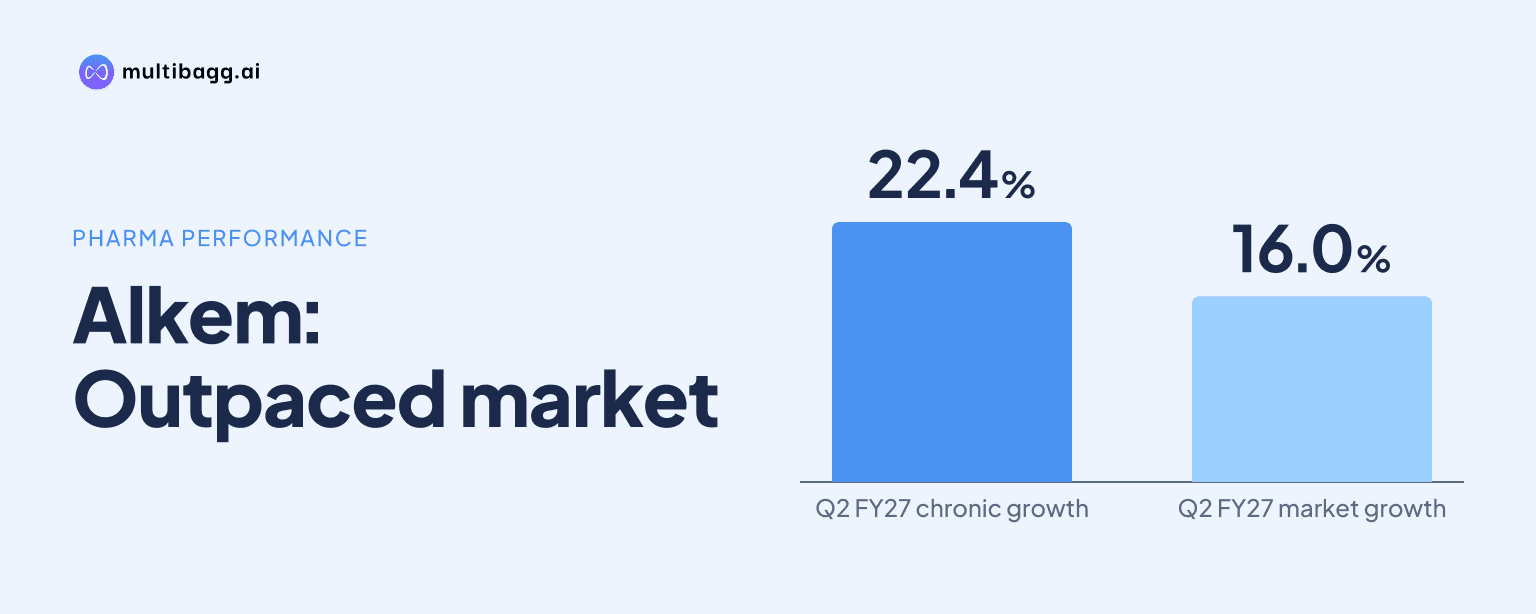
Alkem’s chronic portfolio grew 22.4% year on year in Q2 FY27, exceeding the Indian pharmaceutical market’s 16.0% growth by 640 basis points. Domestic sales rose 9.5% to Rs 3,027.5 crore, while Alkem’s overall IQVIA-measured growth of 13.8% matched the Indian pharmaceutical market, or IPM.
Know Alkem Laboratories inside out
Results, valuation, peers and who's buying, in one view.
How fast did Alkem’s domestic business grow in Q2 FY27?
Alkem’s domestic sales grew 9.5% year on year to Rs 3,027.5 crore in Q2 FY27 from Rs 2,766 crore in Q2 FY26. India accounted for about 68% of Q2 FY27 sales, compared with 17% from the US and 15% from non-US international markets.
Alkem’s domestic sales increased in each of the five comparable second quarters shown in the presentation, rising from Rs 2,216.1 crore in Q2 FY23 to Rs 3,027.5 crore in Q2 FY27. The Q2 FY27 increase included 12.1% growth in branded business, while trade generics grew at a mid-single-digit rate.
Alkem registered 13.8% year-on-year growth in IQVIA sales in Q2 FY27, matching IPM growth of 13.8%. This differs from the 9.5% reported domestic-sales increase because Alkem’s India sales include branded prescription products, trade generics, biotech and MedTech sales, while the market comparison uses IQVIA data.
Why did Alkem’s chronic portfolio grow faster than the market?
Alkem’s chronic portfolio grew 22.4% in Q2 FY27 versus IPM growth of 16.0%, creating a 640-basis-point difference. Alkem described its chronic growth as 1.4 times the market rate, while acute therapies grew 12.1% against IPM growth of 12.3%.
Alkem reported faster growth than the IPM in eight key therapies during Q2 FY27. Anti-diabetic sales grew 27.2% against 17.7% for the IPM, pain and analgesics grew 23.9% against 15.4%, and dermatology grew 21.6% against 13.5%.
Alkem’s vitamin, mineral and nutrient, or VMN, business grew 20.8% against IPM growth of 17.8%, while neuro and central nervous system sales rose 16.1% against 14.4%. Alkem also said it was the volume leader in the semaglutide glucagon-like peptide-1, or GLP-1, parenteral market in Q2 FY27.
Got a follow-up? Ask IRIS
How is Alkem expanding access and building brands?
Alkem launched 26 products across therapy areas in H1 FY27 and had a domestic sales force of about 14,500 medical representatives. The reported India business, which reached Rs 3,027.5 crore in Q2 FY27, includes branded prescription products, trade generics, biotech and MedTech sales.
Alkem expanded its number of larger brand families over the five years to moving annual total, or MAT, September 2026. It had one family above Rs 1,500 crore in MAT September 2026, compared with none in MAT September 2021, while families above Rs 500 crore increased to two from one.
The number of Alkem brand families above Rs 150 crore rose to 11 in MAT September 2026 from seven in MAT September 2021, and families above Rs 50 crore rose to 17 from 13. PAN was Alkem’s number-two brand family in the IPM and its only family above Rs 1,500 crore.
Alkem had 15 brands in the IPM Top 300 and 31 brands ranked in the top three of their covered market, or CVM, among brands above Rs 25 crore. CLAVAM and ALZ were the two brand families above Rs 500 crore in MAT September 2026.
What does Q2 FY27 show about Alkem’s business mix?
Alkem reported revenue from operations of Rs 4,552 crore in Q2 FY27, up 13.8% year on year, and earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 1,025.2 crore, up 11.3%. EBITDA margin was 22.5%, down 50 basis points from 23.0% in Q2 FY26, which Alkem attributed to Enzene contract development and manufacturing organisation operating costs and the Occlutech acquisition.
India sales of Rs 3,027.5 crore exceeded US sales of Rs 783 crore and non-US international sales of Rs 671 crore in Q2 FY27. US sales rose 2.4% year on year, led largely by volume growth, although Alkem cited mid-teen price erosion from additional competition in select products.
Non-US international sales increased 58% year on year to Rs 671 crore in Q2 FY27, or 29% excluding Occlutech, which was integrated from Q2 FY27. Alkem said double-digit growth in Latin American markets contributed to the non-US result, while the segment’s sales contribution rose to 15% from 14% in Q2 FY26.
Profit after tax declined 11.7% year on year to Rs 675.3 crore in Q2 FY27, mainly due to a higher effective tax rate, according to Alkem. Research and development expenditure rose to Rs 195.3 crore from Rs 130.2 crore in Q2 FY26, reaching 4.3% of revenue from 3.3%, while net cash stood at Rs 4,905.4 crore at September 30, 2026.
Conclusion
Alkem’s Q2 FY27 domestic results showed chronic therapies growing faster than the IPM even as its 13.8% overall IQVIA-measured growth matched the market. Chronic growth of 22.4% versus 16.0% for the IPM was supported by faster expansion in anti-diabetic, pain, dermatology, VMN and neuro categories, alongside 11 brand families above Rs 150 crore in MAT September 2026.
The next disclosed markers are the pace of launches after 26 products in H1 FY27, the scaling of brand families led by PAN, and progress on remediation at the Daman formulations facility. Alkem said it had submitted a response after the facility received an Official Action Indicated classification, and remediation was in progress as of Q2 FY27.