










Amber Enterprises India Ltd rally follows 60% Q2 revenue growth
Key highlights
- Amber Enterprises closed 7.27% higher at Rs 6,760 on November 13.
- Q2 FY27 revenue from operations rose 60% year on year to Rs 2,627 crore.
- Electronics revenue grew 94% year on year in the September quarter.
- Consolidated net loss widened to Rs 80.16 crore from Rs 32.86 crore a year earlier.
powered by IRIS
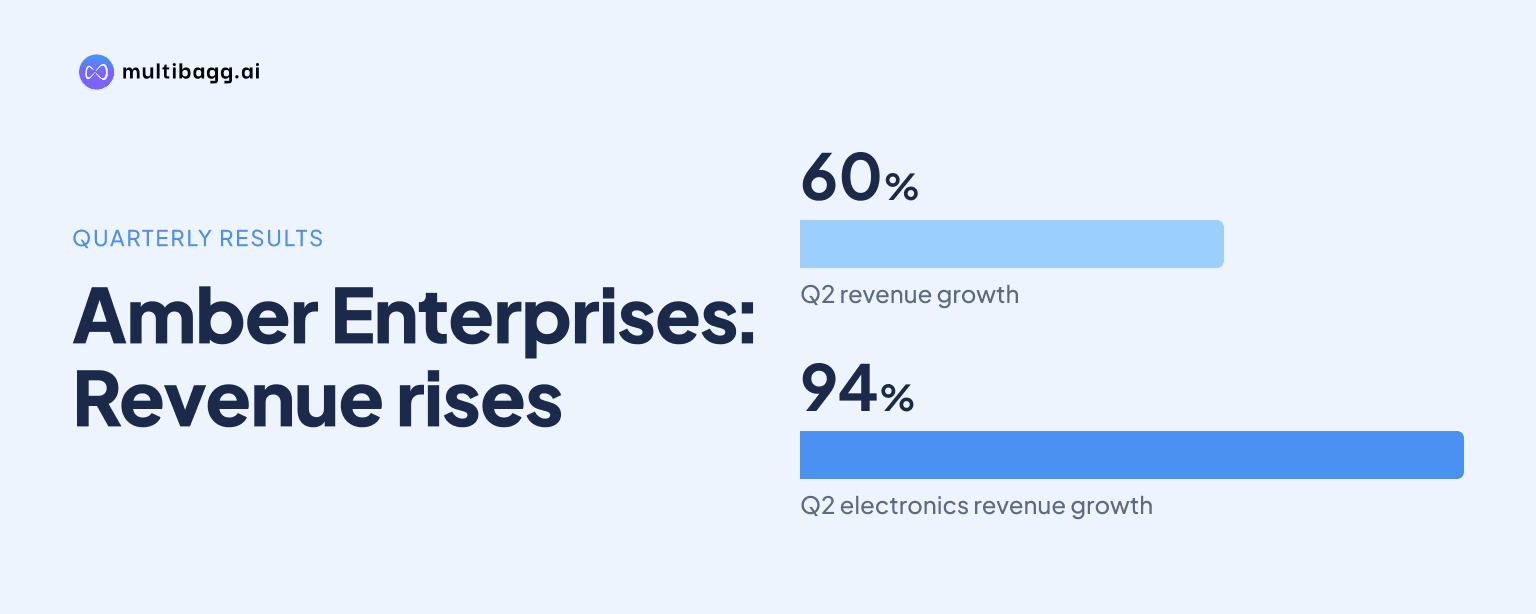
Amber Enterprises India Ltd rallied 7.27% on November 13 to close at Rs 6,760 after its Q2 FY27 revenue from operations rose 60% year on year to Rs 2,627 crore, far ahead of market expectations, even as the consolidated net loss widened to Rs 80.16 crore.
Why did Amber Enterprises shares rally after Q2 FY27 results?
Amber Enterprises rallied because investors focused on the scale of its revenue growth, led by the electronics business. The stock rose as much as 12% during the session to Rs 6,980, a near two-month high, while one market update described an intraday gain of up to 14% after the results announcement.
Revenue from operations reached Rs 2,627 crore in the September quarter, compared with Rs 1,647 crore a year earlier. This 60% increase was substantially above the cited analyst estimate of Rs 2,072 crore. The electronics division was the principal growth driver, with reported revenue growth of 94%, while consumer durables revenue rose 41% year on year.
What did Amber Enterprises report on profitability?
Amber Enterprises reported that strong revenue did not translate into stronger quarterly profitability. Operating EBITDA rose 30% year on year to Rs 127 crore, but operating EBITDA margin contracted by 110 basis points to 4.8%, reflecting pressure on the earnings quality behind the sales growth.
The company posted a consolidated net loss of Rs 80.16 crore, compared with a Rs 32.86 crore loss in the corresponding quarter a year earlier. The reported loss was also above the cited estimate of Rs 26.69 crore. Separate market commentary referred to an adjusted loss after tax of Rs 57 crore, while highlighting the same broad concern: margins and losses remained under pressure despite the revenue beat.
Which business segments shaped Amber Enterprises' quarter?
Amber Enterprises' electronics business shaped the quarter by delivering the fastest reported expansion and driving the top-line beat. Electronics revenue rose 94% year on year, against an expectation of 30% growth cited in market commentary, indicating that the division was the main contributor to the September-quarter sales momentum.
The consumer durables business was a counterweight to that growth. Its revenue increased 41% year on year and exceeded one brokerage's estimate, but the division reported an EBITDA loss of Rs 13.9 crore versus an expected EBITDA profit of Rs 35.6 crore. Weakness in this business was cited as a reason for lower-than-expected consolidated margins.
Got a follow-up? Ask IRIS
Could Amber Enterprises face profit booking after the rally?
Amber Enterprises could face profit booking if investors place greater weight on the margin contraction and wider loss after the sharp post-results move. The rally occurred even as the broader Sensex declined 0.33% on November 13, with Amber Enterprises outperforming its sector by 7.67 percentage points according to the supplied market update.
That does not establish the stock's next direction, but it highlights a clear split in the result: revenue was materially ahead of expectations while profitability lagged. UBS retained a Neutral rating and a 12-month target price of Rs 7,600, based on a November 12 closing price of Rs 6,215. Investors will likely assess whether sales growth can be sustained without continued pressure from the consumer durables division and interest burden.
What is Amber Enterprises' FY27 outlook?
Amber Enterprises expects FY27 revenue growth of around 15% to 20%, with project delays expected to affect performance partly. The guidance provides a stated framework for judging whether the strong September-quarter revenue performance can continue through the rest of the financial year.
On profitability, the company expects margins to return to normalised levels in FY28, supported by completion and delivery of older projects. The outlook therefore places the near-term focus on project execution, facility stabilisation and operating-cost pressure rather than on revenue growth alone. Market commentary also identified the pace of new-facility stabilisation as important for profitability.
Conclusion
Amber Enterprises' November 13 share rally reflected a decisive revenue beat, with Q2 FY27 sales rising 60% to Rs 2,627 crore on electronics-led growth. Yet the wider consolidated loss and lower operating margin show that the quarter did not resolve profitability concerns, particularly in consumer durables.
The next key markers are the company's 15% to 20% FY27 revenue-growth expectation, the impact of project delays, and progress toward the margin normalisation it expects in FY28 after older projects are completed and delivered. These factors will determine whether the revenue momentum is followed by a sustained improvement in earnings quality.