










Apeejay Surrendra Park Hotels Q2 PAT fell 9.9% on costs
Key highlights
- ASPH's Q2-FY27 PAT declined 9.9% year on year to Rs 14.6 crore.
- ASPH's Q2-FY27 operating EBITDA increased 11.0% to Rs 54.4 crore and margin rose 100 basis points to 30.27%.
- ASPH's Q2-FY27 depreciation rose 30.1% to Rs 22.9 crore, while interest was Rs 10.8 crore versus Rs 4.6 crore a year earlier.
- ASPH's H1-FY27 PAT fell 11.8% to Rs 26.1 crore despite operating EBITDA growth of 7.2% to Rs 101.2 crore.
powered by IRIS
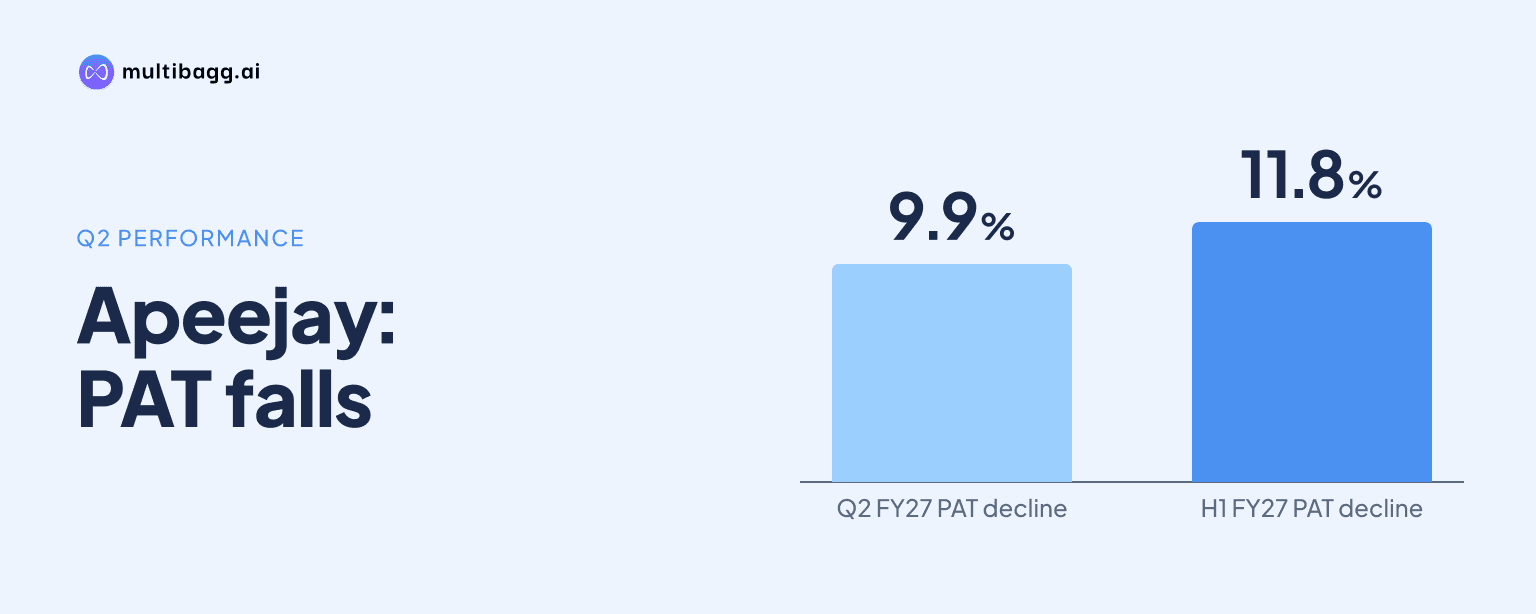
Apeejay Surrendra Park Hotels reported Q2-FY27 profit after tax of Rs 14.6 crore, down 9.9% year on year, because depreciation rose 30.1% to Rs 22.9 crore and interest reached Rs 10.8 crore, outweighing 11.0% growth in operating EBITDA to Rs 54.4 crore and a 100-basis-point margin increase.
Know Apeejay Surrendra Park Hotels inside out
Results, valuation, peers and who's buying, in one view.
Why did ASPH's Q2-FY27 profit decline?
ASPH's Q2-FY27 profit declined because higher depreciation and interest more than offset the increase in earnings before interest, tax, depreciation and amortisation, or EBITDA. EBITDA rose by Rs 5.5 crore year on year to Rs 55.7 crore, while depreciation increased by Rs 5.3 crore to Rs 22.9 crore and interest rose to Rs 10.8 crore from Rs 4.6 crore in Q2-FY26. Profit before tax therefore declined to Rs 22.0 crore from Rs 27.8 crore.
The lower tax charge reduced, but did not eliminate, the effect on net profit. Tax fell by Rs 4.2 crore to Rs 7.4 crore, while profit after tax, or PAT, decreased to Rs 14.6 crore from Rs 16.2 crore. PAT margin narrowed to 8.07% from 9.61%, a decline of 154 basis points, where one basis point equals one-hundredth of a percentage point.
Total comprehensive income fell 17.7% to Rs 14.9 crore in Q2-FY27 from Rs 18.1 crore in Q2-FY26. Other comprehensive income was Rs 0.3 crore, compared with Rs 1.9 crore a year earlier, contributing to the larger percentage decline in comprehensive income than in PAT. Diluted earnings per share declined 9.2% to Rs 0.69 from Rs 0.76.
How did ASPH's operating performance change in Q2-FY27?
ASPH increased operating EBITDA faster than operating revenue in Q2-FY27, lifting operating EBITDA margin to 30.27% from 29.27% in Q2-FY26. Operating revenue grew 7.3% to Rs 179.7 crore, while operating expenses rose 5.8% to Rs 125.3 crore. The difference resulted in operating EBITDA of Rs 54.4 crore, up from Rs 49.0 crore.
The quarter also improved from Q1-FY27. Operating revenue increased 7.7% from Rs 166.8 crore, operating EBITDA rose 16.0% from Rs 46.9 crore, and operating EBITDA margin expanded by 215 basis points from 28.12%. PAT increased 27.0% sequentially from Rs 11.5 crore, while profit before tax rose 8.9% from Rs 20.2 crore.
Other income was Rs 1.3 crore in Q2-FY27, compared with Rs 1.2 crore in Q2-FY26 and Rs 4.8 crore in Q1-FY27. ASPH defines operating EBITDA as EBITDA excluding other income. Including other income, EBITDA margin was 30.77% in Q2-FY27, against 29.77% a year earlier and 30.13% in the preceding quarter.
What do ASPH's H1-FY27 results show?
ASPH's H1-FY27 PAT fell 11.8% to Rs 26.1 crore despite a 7.2% increase in operating EBITDA to Rs 101.2 crore. Operating revenue rose 7.1% to Rs 346.5 crore and total revenue increased 7.8% to Rs 352.6 crore. Operating expenses increased 7.1% to Rs 245.3 crore, leaving operating EBITDA margin nearly unchanged at 29.21%, compared with 29.18% in H1-FY26.
The first-half profit movement reflected the same costs seen in Q2-FY27. EBITDA increased 9.6% to Rs 107.3 crore, but depreciation rose 23.2% to Rs 44.0 crore and interest increased 90.1% to Rs 21.1 crore. Profit before tax fell 15.9% to Rs 42.2 crore from Rs 50.2 crore, while PAT margin declined 165 basis points to 7.40% from 9.05%.
H1-FY27 other income was Rs 6.1 crore, compared with Rs 3.5 crore in H1-FY26, helping total EBITDA grow faster than operating EBITDA. Total comprehensive income nevertheless decreased 14.7% to Rs 26.6 crore from Rs 31.2 crore. Diluted earnings per share fell 12.2% to Rs 1.22 from Rs 1.39 for the six-month period.
Got a follow-up? Ask IRIS
What changed in ASPH's balance sheet by H1-FY27?
ASPH reported total assets of Rs 2,172.3 crore at H1-FY27, compared with Rs 2,054.3 crore at FY26, while total equity increased to Rs 1,352.4 crore from Rs 1,342.1 crore. Property, plant and equipment was Rs 1,243.2 crore, compared with Rs 1,238.5 crore at FY26. Capital work-in-progress increased to Rs 89.9 crore from Rs 80.4 crore, and right-of-use assets rose to Rs 315.3 crore from Rs 286.2 crore.
Non-current borrowings increased to Rs 242.5 crore at H1-FY27 from Rs 202.0 crore at FY26, while current borrowings rose to Rs 58.9 crore from Rs 55.3 crore. Non-current lease liabilities increased to Rs 117.9 crore from Rs 91.1 crore, and current lease liabilities rose to Rs 30.2 crore from Rs 24.5 crore. The presentation reports these changes but does not identify a specific balance-sheet item as the cause of the Q2-FY27 interest increase.
Current assets increased to Rs 376.4 crore from Rs 316.6 crore at FY26. Cash and cash equivalents rose to Rs 45.4 crore from Rs 24.2 crore, investments increased to Rs 85.6 crore from Rs 77.2 crore, and trade receivables were Rs 44.6 crore compared with Rs 41.4 crore. Total current liabilities rose to Rs 292.8 crore from Rs 257.9 crore, including trade payables of Rs 68.1 crore.
What is ASPH's disclosed FLURYS expansion plan?
ASPH's disclosed FLURYS plan targets about 140 stores in FY27 and about 300 stores by FY30, following 110 stores in FY26. The presentation also describes FLURYS as having 112 stores currently, with the format positioned for expansion through asset-light bakery cafés, kiosks and cafés in malls and airports.
The company presents the expansion as a shift from a regional brand and physical retail towards a national consumer brand with omnichannel and e-commerce sales. Its stated mechanisms for value creation include greater presence in high-footfall locations, more customer occasions and a larger revenue base. The source does not provide revenue, capital expenditure or profitability targets for the planned FLURYS store additions.
Conclusion
ASPH's Q2-FY27 operating performance improved, with operating revenue up 7.3%, operating EBITDA up 11.0% and operating EBITDA margin up 100 basis points to 30.27%. However, depreciation of Rs 22.9 crore and interest of Rs 10.8 crore reduced profit before tax by 20.9%, resulting in a 9.9% year-on-year decline in PAT to Rs 14.6 crore. The H1-FY27 figures show the same pattern, with operating EBITDA rising 7.2% while PAT fell 11.8%.
The next disclosed operating plan to watch is FLURYS' target of about 140 stores in FY27 and about 300 by FY30, from 110 stores in FY26. Future results can show whether the stated store expansion, omnichannel development and e-commerce growth affect revenue growth, operating margins, depreciation, interest and PAT margin differently from the Q2-FY27 and H1-FY27 outcomes.