










Aptech September results include GST, labour and tax effects
Key highlights
- Aptech reported Rs 66.9734 crore of revenue from operations for the quarter ended September 30, 2026.
- Aptech disclosed a Rs 17.25 lakh payment after a GST investigation-team visit in September 2026.
- Profit after tax was Rs 6.77 crore for the September 2026 quarter and Rs 14.3419 crore for the first half.
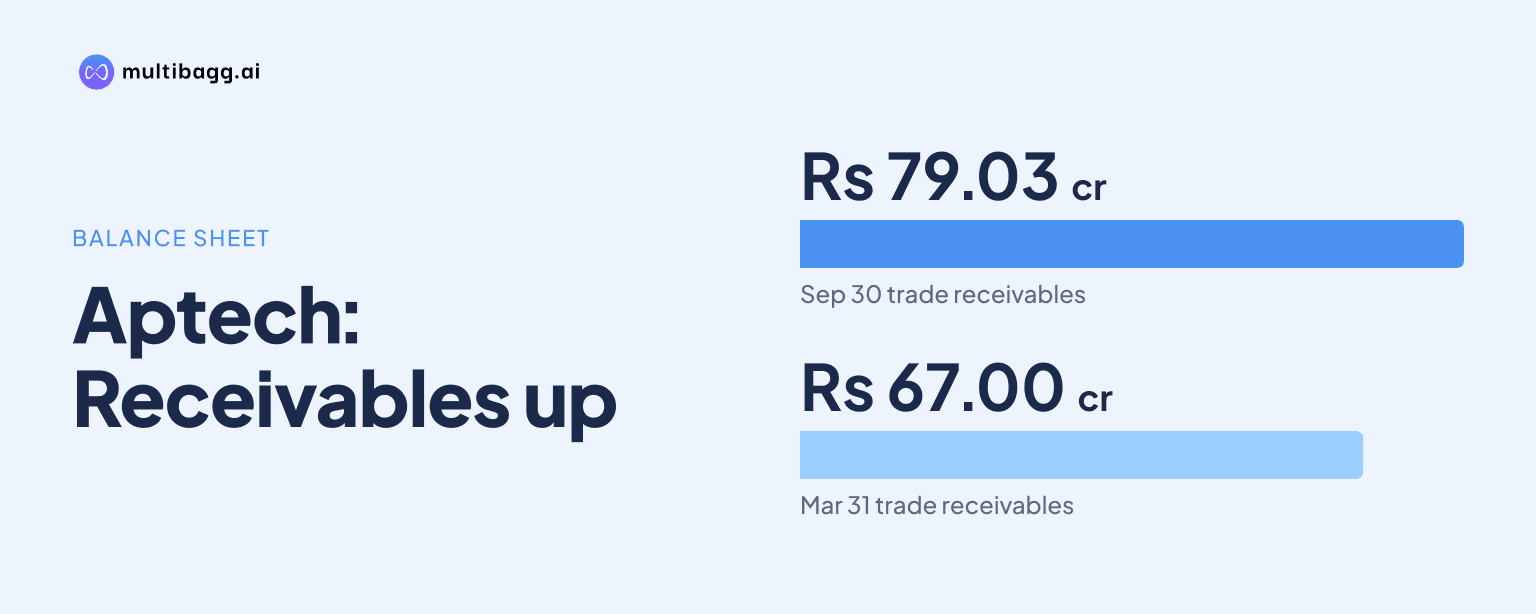
- Consolidated trade receivables rose to Rs 79.028 crore at September 30, 2026 from Rs 67.0037 crore at March 31, 2026.
powered by IRIS
Aptech Limited reported Rs 66.9734 crore of revenue from operations and Rs 6.77 crore of profit after tax for the quarter ended September 30, 2026, while its filing also disclosed a Rs 17.25 lakh GST payment, immediate labour-code past-service-cost recognition and deferred-tax remeasurement after a tax-regime decision.
Know Aptech inside out
Results, valuation, peers and who's buying, in one view.
What did Aptech report for the September 2026 quarter?
Aptech reported revenue from operations of Rs 66.9734 crore for the quarter ended September 30, 2026, while profit after tax was Rs 6.77 crore. For the six months from April 1, 2026 to September 30, 2026, revenue from operations was Rs 137.5363 crore and profit after tax was Rs 14.3419 crore.
The half-year revenue was Rs 3.5895 crore higher than twice the September-quarter revenue, while half-year profit after tax was Rs 0.8019 crore above twice the quarterly amount. The disclosed six-month figures therefore incorporate a June 2026 quarter with higher implied revenue and profit than the September quarter.
Aptech’s September filing was reviewed by its auditor under the Standard on Review Engagement 2410, rather than audited as a full-year financial statement. The auditor dated its review report November 4, 2026 and stated that nothing had come to its attention to indicate that the consolidated statement contained a material misstatement.
What was Aptech’s GST payment in September 2026?
Aptech disclosed a Rs 17.25 lakh payment after a GST investigation team visited its office premises during September 2026 and after discussions with GST authorities. GST means goods and services tax, and the payment was identified in the notes accompanying the September-quarter results.
The filing does not clearly reproduce the full accounting description of the payment in the supplied extract. It therefore does not establish whether the matter has been fully concluded, whether any amount is recoverable, or whether the payment relates to a specified earlier financial period.
The Rs 17.25 lakh payment was disclosed alongside quarterly revenue of Rs 66.9734 crore, but it remains below Rs 1 crore and is therefore stated in lakh. Aptech did not provide a comparable GST-investigation payment for the quarter ended September 30, 2025 in the supplied material.
How did the New Labour Codes affect Aptech’s accounts?
Aptech said legislative amendments through four labour codes, collectively called the New Labour Codes, changed employee-benefit plans and required immediate recognition of past service cost in the current reporting period. The company said the treatment followed Indian Accounting Standard 19, or Ind AS 19, which treats changes arising from legislative amendments as a plan amendment.
Immediate recognition means the past-service-cost effect was recorded in the statement of profit and loss for the September 2026 reporting period rather than spread across later periods. The supplied extract explains the accounting mechanism but does not clearly show the rupee value of the resulting charge.
Aptech said it continued to monitor the finalisation of rules and government clarifications on other aspects of the New Labour Codes. The company said it would finalise the financial-statement impact once those rules and clarifications are available, but did not disclose a timetable or an estimate for any further amount.
Got a follow-up? Ask IRIS
Why did Aptech remeasure deferred taxes?
Aptech said it decided to opt for a concessional tax regime under the Income-tax Act, 2025, as applicable to the company, and consequently remeasured deferred tax assets and deferred tax liabilities. Deferred tax reflects accounting tax effects of temporary differences that may reverse in later periods, rather than only tax currently payable.
The remeasurement could affect the tax expense included in the Rs 6.77 crore profit after tax for the September 2026 quarter. However, the supplied filing extract does not clearly state the amount of any charge or credit arising from the regime transition, so it does not support allocating the reported profit effect to that decision.
Net deferred tax assets on Aptech’s consolidated balance sheet were Rs 31.4794 crore at September 30, 2026, compared with Rs 32.822 crore at March 31, 2026. The Rs 1.3426 crore decline occurred in the same six-month period as the tax-regime decision, although the filing does not attribute the whole movement to the remeasurement.
What changed in Aptech’s cash and balance-sheet position?
Aptech’s consolidated total assets were Rs 415.4664 crore at September 30, 2026, down from Rs 427.7521 crore at March 31, 2026, while total equity fell to Rs 239.2838 crore from Rs 248.6165 crore. Total liabilities declined to Rs 176.1826 crore from Rs 179.1356 crore over the same six-month period.
Trade receivables increased to Rs 79.028 crore at September 30, 2026 from Rs 67.0037 crore at March 31, 2026, while cash and cash equivalents declined to Rs 13.6766 crore from Rs 27.0982 crore. The balance sheet therefore showed Rs 12.0243 crore more in receivables and Rs 13.4216 crore less in cash over the period.
The cash-flow statement recorded Rs 9.0664 crore of cash used in operating activities for the period ended September 30, 2026, compared with Rs 1.9359 crore generated in the period ended September 30, 2025. It also recorded net bank borrowings of Rs 13.3564 crore during the 2026 period, while the March 31, 2026 balance sheet showed no borrowings.
Conclusion
Aptech’s September 2026 results combine Rs 66.9734 crore of quarterly revenue and Rs 6.77 crore of profit after tax with three separately disclosed reporting matters: a Rs 17.25 lakh GST payment, immediate labour-code past-service-cost recognition and deferred-tax remeasurement following a concessional tax-regime decision. The filing does not quantify the labour-code or tax-regime effects in the supplied extract.
The next disclosed matter to watch is Aptech’s final assessment of the New Labour Codes once government rules and clarifications are finalised. Later disclosures may also provide more detail on the GST payment, the deferred-tax remeasurement, and whether trade receivables of Rs 79.028 crore convert into cash after September 30, 2026.