










Arabian Petroleum H1 FY27 Profit Rises 142% to ₹14.5 Crore
Key highlights
- Arabian Petroleum reported H1 FY27 consolidated revenue of ₹342.0 crore, up 88.3% year on year.
- Arabian Petroleum's H1 FY27 consolidated net profit was ₹14.5 crore, up 141.7% from ₹6.0 crore.
- H1 FY27 net profit of ₹14.5 crore exceeded Arabian Petroleum's ₹11.2 crore profit for FY26.
- Arabian Petroleum reported total borrowings of ₹57.5 crore in September 2026, versus ₹47.7 crore in March 2026.
powered by IRIS
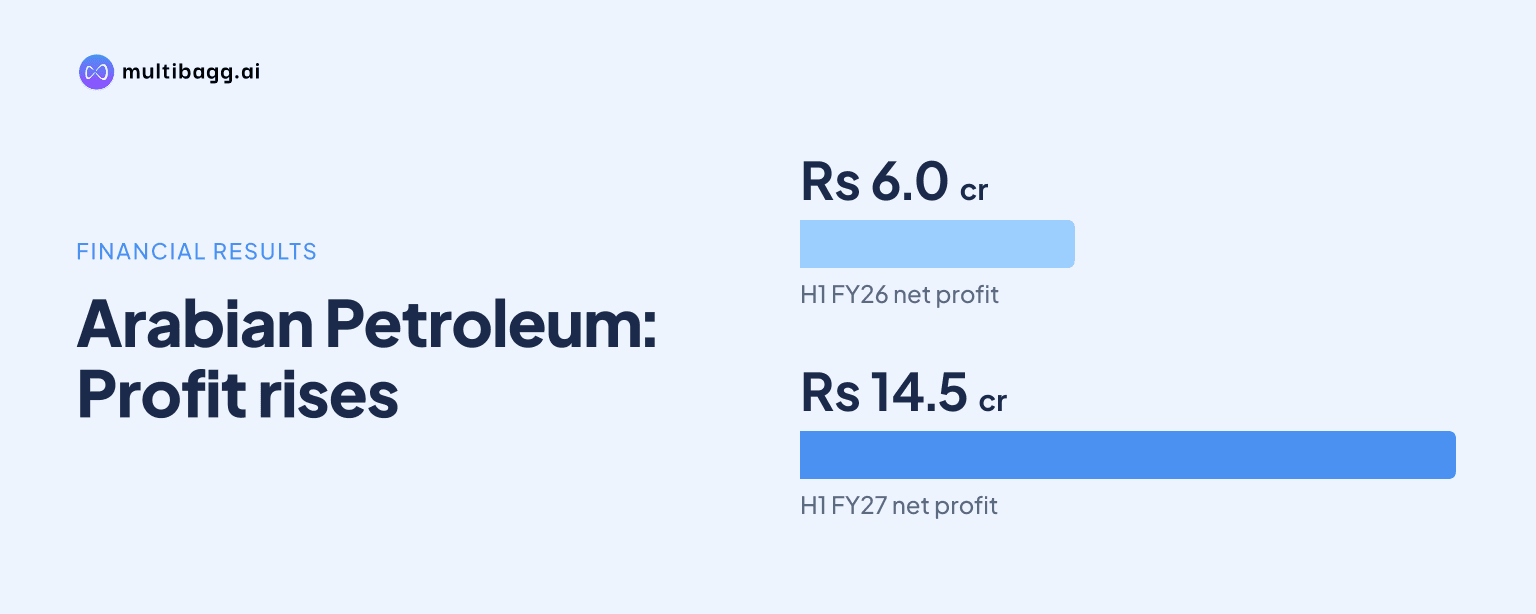
Arabian Petroleum Limited reported H1 FY27 consolidated net profit of ₹14.5 crore, up 141.7% year on year, while revenue from operations increased 88.3% to ₹342.0 crore for the half year ended September 30, 2026. The profit for the first half also exceeded the company's ₹11.2 crore profit reported for full-year FY26.
Know Arabian Petroleum inside out
Results, valuation, peers and who's buying, in one view.
What did Arabian Petroleum report for H1 FY27?
Arabian Petroleum reported consolidated revenue from operations of ₹342.0 crore in H1 FY27, compared with ₹181.6 crore in H1 FY26. Total income rose to ₹343.2 crore from ₹182.7 crore over the same period, including other income of ₹1.2 crore.
Consolidated net profit rose to ₹14.5 crore from ₹6.0 crore a year earlier. Profit before tax and before exceptional items and tax were each reported at ₹19.0 crore, against ₹7.9 crore in H1 FY26. The results were approved for the half year ended September 30, 2026, at the board meeting scheduled on November 14, 2026.
The filing also showed that H1 FY27 revenue was higher than the ₹231.7 crore reported in H2 FY26. Net profit was also above the ₹5.3 crore reported in H2 FY26. The company has not published an earnings-call transcript for the period, so the reported figures do not include management guidance.
How did Arabian Petroleum's operating performance change?
Arabian Petroleum's reported operating profit increased 161.8% year on year and 206.9% compared with the preceding half year. The results summary placed the H1 FY27 operating margin at 5.5%, compared with 4.3% in H1 FY26 and 3.1% in H2 FY26.
A separate filing summary showed operating profit of ₹21.0 crore for the September 2026 half year, compared with ₹9.0 crore in September 2025 and March 2026. That summary put operating profit margin at 6.1%, versus 4.9% a year earlier and 3.9% in the preceding half year. The company disclosed both sets of reported metrics, without an earnings-call explanation of the differing margin presentation.
For the quarter ended September 30, 2026, Arabian Petroleum reported EBITDA of ₹21.4 crore, up 81.8% year on year from ₹11.8 crore. Quarterly profit after tax was ₹14.5 crore, up 143.2% year on year, according to the figures in the results statement.
What are the key H1 FY27 financial figures?
Arabian Petroleum's half-year results show higher sales, income and profit compared with both the year-earlier period and the preceding half year. The rise in net profit was faster than the increase in revenue, while other income remained broadly stable.
The company also reported H1 FY27 earnings per share of ₹13.29 in one consolidated results summary, compared with ₹5.46 in H1 FY26. Its standalone business reported revenue from operations of ₹273.2 crore and profit after tax of ₹13.0 crore for the half year.
Got a follow-up? Ask IRIS
Why does the H1 result matter for Arabian Petroleum investors?
Arabian Petroleum's H1 FY27 net profit of ₹14.5 crore was above its consolidated FY26 profit of ₹11.2 crore. Consolidated FY26 revenue from operations was ₹413.3 crore, up 44.9% from ₹285.3 crore in FY25, providing context for the sharper revenue growth recorded in the first half of FY27.
The result also follows a weaker margin profile in H2 FY26. In that period, revenue from operations was ₹231.7 crore and EBITDA was ₹10.0 crore, resulting in an EBITDA margin of 4.31%, compared with 5.98% in H2 FY25. H2 FY26 profit after tax was ₹5.3 crore, while its PAT margin was 2.27%.
The latest filing indicates that the company expanded sales and increased reported profits during H1 FY27. However, the source does not provide management commentary or guidance explaining the drivers of sales growth, customer demand, pricing, product mix or the expected pace of future performance.
What balance-sheet and cash-flow factors were disclosed?
Arabian Petroleum's disclosed balance-sheet data showed higher borrowings, receivables and inventories as of September 2026. Total borrowings were ₹57.5 crore, compared with ₹47.7 crore in March 2026, while receivables stood at ₹103.6 crore and inventories at ₹78.3 crore.
The same source reported operating cash flow of ₹1.3 crore after working-capital absorption of ₹36.4 crore in H1 FY27. Fixed assets plus capital work in progress were reported at ₹14.8 crore in September 2026, compared with ₹12.3 crore in March 2026. These disclosures place the growth in revenue alongside a larger investment in working capital and assets.
Higher receivables and inventories can affect the cash conversion cycle even when reported sales and profit rise. The filing identifies the movement in these balance-sheet items but does not include management guidance on collections, inventory normalisation, financing plans or future capital expenditure.
Conclusion
Arabian Petroleum's H1 FY27 filing shows consolidated revenue growth of 88.3% to ₹342.0 crore and net-profit growth of 141.7% to ₹14.5 crore. The half-year profit was higher than the full-year FY26 reported profit, while the disclosed results also showed an improvement in operating-margin measures compared with the prior periods.
Investors will next watch the company's subsequent financial disclosures for revenue growth, margin trends, receivable and inventory levels, borrowings and operating cash flow. No earnings-call transcript or management guidance for the reported period was available in the source material.