










Archean cuts FY27 SOP expectation to about 4,500 tonnes
Key highlights
- Archean cut FY27 SOP output expectation to about 4,500 tonnes from 9,000-10,000 tonnes.
- Archean produced 2,396 tonnes of SOP in FY27 H1, including 444 tonnes in Q2.
- Archean reported SOP value of Rs 2.18 crore in FY27 Q2 on 444 tonnes.
- Archean expects its first 4,000-hectare brine-field expansion phase to operate by the current quarter-end or early next quarter.
powered by IRIS
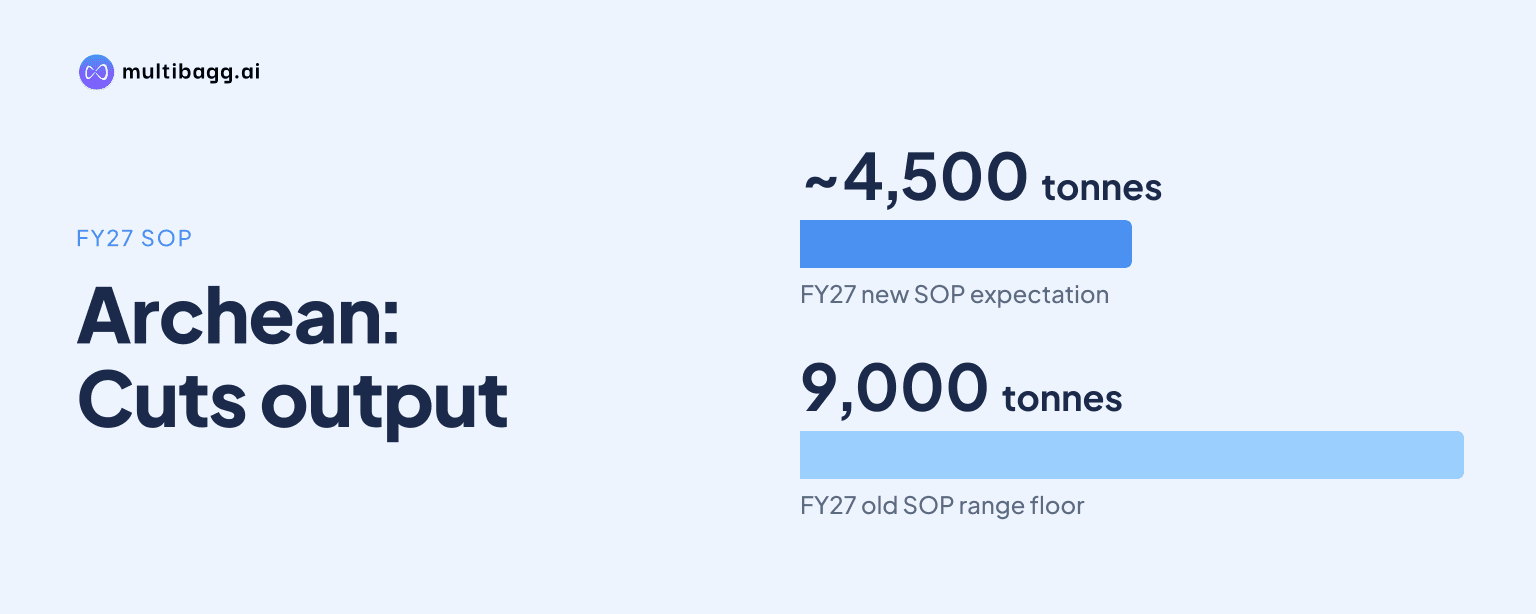
Archean Chemical has cut its FY27 sulphate of potash, or SOP, output expectation to about 4,500 tonnes from 9,000-10,000 tonnes, following a one-quarter delay in trials and feedstock throughput that remained behind plan. Archean reported 2,396 tonnes in FY27 H1, including 444 tonnes in Q2.
Know Archean Chemical Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Archean cut FY27 SOP output expectations?
Archean cut its FY27 SOP expectation because trials were delayed by one quarter and KTMS production was lower than planned in the first half. Management said the delay reduced available production time, while lower KTMS output and feedstock throughput limited the material available for SOP production.
The latest expectation of about 4,500 tonnes is 4,500 tonnes below the lower end of the previous 9,000-10,000-tonne range and 5,500 tonnes below its upper end. This represents a 50% to 55% reduction from the earlier guidance range, based on management's disclosed figures.
Management initially referred during the call to potential FY27 output of around 3,500 tonnes, then cited a range of 3,500-4,000 tonnes before stating that Archean should reach the 4,500-tonne level “as we stand now.” The 4,500-tonne figure is therefore the latest expectation, although it remains dependent on second-half feedstock operations.
How much SOP has Archean produced in FY27 so far?
Archean produced 2,396 tonnes of SOP in FY27 H1, comprising 1,952 tonnes in Q1 and 444 tonnes in Q2. Management first described H1 output as around 2,000 tonnes, but subsequently provided the quarterly figures that total 2,396 tonnes.
Q2 output was 1,508 tonnes below Q1, based on the reported 1,952 tonnes in Q1 and 444 tonnes in Q2. The decline means Archean has not yet established a steadily rising production run rate during FY27 H1.
To meet the 4,500-tonne expectation, Archean would need to produce another 2,104 tonnes in the second half, or about 1,052 tonnes per quarter. That implied H2 rate is above Q2 output of 444 tonnes but below the 1,952 tonnes reported in Q1.
What operational issues constrained Archean's SOP output?
Archean identified delayed trials and lower KTMS production as the immediate reasons for the FY27 SOP shortfall. Management said it had lost a quarter because of trials and that KTMS production had been lower during the first half of the year.
Feedstock capacity and throughput were also behind plan, according to management. Archean said it was working to ramp KTMS output in H2 and would need to realign feedstock operations after the trials were completed.
Management did not disclose a monthly feedstock target, an expected KTMS volume, or a date for the operational realignment. It also did not quantify how much of the reduction from 9,000-10,000 tonnes to 4,500 tonnes arose separately from trial delays, KTMS production, or broader feedstock throughput.
The Q1-to-Q2 comparison shows the scale of the disruption, with production falling from 1,952 tonnes to 444 tonnes. However, the transcript does not assign the 1,508-tonne quarterly decline to any single operating factor.
Got a follow-up? Ask IRIS
What did Archean report on SOP sales and pricing?
Archean reported SOP value of Rs 2.18 crore on 444 tonnes in FY27 Q2. Management described Q2 as an aberration while discussing pricing and said dependable production would be important for building customer relationships.
Management said SOP prices should generally be at least Rs 59,000 to Rs 60,000 per tonne, while also referring to a range of $600 to $700. This was management commentary on the market and not formal SOP revenue guidance for FY27 or FY28.
Archean said its prior production pattern had been episodic, making it a spot-market participant. Management's view was that more consistent production could enable the company to become a more dependable supplier and obtain better pricing with appropriate customer relationships.
Archean did not provide a separate SOP realization for Q2 beyond the disclosed Rs 2.18 crore value on 444 tonnes. The company also did not state whether the Q2 sales value represented all SOP produced in the quarter or a different dispatch volume.
What has Archean said about FY28 output and SOP projects?
Archean has not given a formal FY28 SOP volume target, but management said it expects next year's production to be significantly higher than FY27 guidance. In a separate response, management said it expected FY28 output to exceed the earlier FY27 guidance range of 9,000-10,000 tonnes.
Management declined to give a specific FY28 indication because half of FY27 remained. The comments signal an intended ramp after the current year's planning and feedstock issues, but they do not establish a binding FY28 output target.
Archean said its SOP plant modification should be up and running during the current financial year and should be capitalized by year-end. Of total capital work in progress, or CWIP, of about Rs 120 crore, management said roughly Rs 80 crore was in the chemicals business, mainly for brine-field expansion and SOP expansion.
The brine-field project is not described as an SOP-only project. Archean said its fully expanded brine field would cover 24,000 hectares, compared with 16,000 hectares already developed, with the remaining 8,000 hectares being developed in two 4,000-hectare phases.
Management said the first 4,000-hectare brine-field phase was more or less complete and should enter operation by the end of the current quarter or early in the next quarter. The company said the expansion would add salt and bromine volumes, while the transcript does not quantify any incremental SOP output from the brine field or the SOP modification.
Conclusion
Archean's FY27 SOP expectation of about 4,500 tonnes confirms a substantial reduction from its previous 9,000-10,000-tonne range. The 2,396 tonnes produced in H1, including 444 tonnes in Q2, reflect the effect of delayed trials, lower KTMS production and feedstock throughput that management said was behind plan.
The next factors to watch are H2 KTMS production, the planned realignment of feedstock operations and the SOP plant modification due to be operational during the current financial year. Management also expects the first 4,000-hectare brine-field phase to begin operations by the end of the current quarter or early in the next quarter, while withholding a formal FY28 SOP target.