










Associated Alcohols & Breweries Limited Q2 Revenue Rises 7% YoY
Key highlights
- ASALCBR reported Q2 FY27 net revenue of ₹271.6 crore, up 7% year-on-year.
- Q2 FY27 EBITDA was ₹17.7 crore, with EBITDA margin declining to 7% from 9% a year earlier.
- Alcohol segment revenue rose 14% year-on-year to ₹195.3 crore, while segment EBITDA was ₹16.8 crore.
- Earnings per share fell to ₹3.99 in Q2 FY27 from ₹7.69 in Q2 FY26.
powered by IRIS
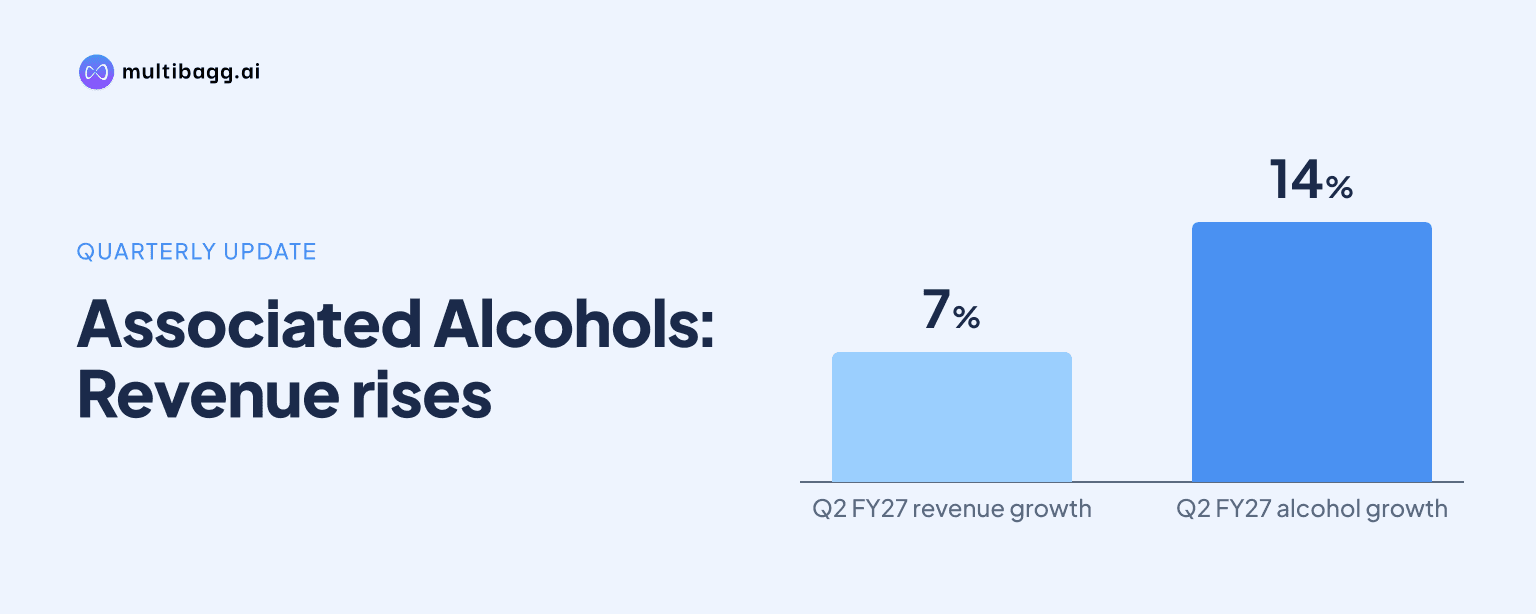
Associated Alcohols & Breweries Limited reported net revenue from operations of ₹271.6 crore in Q2 FY27, up 7% year-on-year, while EBITDA was ₹17.7 crore and profit after tax was ₹8 crore as higher grain, glass and PET bottle costs reduced margins.
Know Associated Alcohols & Breweries inside out
Results, valuation, peers and who's buying, in one view.
How did Associated Alcohols & Breweries Limited perform in Q2 FY27?
Associated Alcohols & Breweries Limited, referred to as ASALCBR, recorded 7% year-on-year growth in net revenue from operations to ₹271.6 crore for the quarter ended September 2026. EBITDA stood at ₹17.7 crore, translating to a 7% margin, while profit after tax was ₹8 crore and the PAT margin was 3%.
The quarterly numbers show that revenue growth did not translate into a comparable expansion in profitability. EBITDA declined from ₹24 crore in Q2 FY26 to ₹17.7 crore in Q2 FY27, and the EBITDA margin declined from 9% to 7%. Earnings per share fell to ₹3.99 from ₹7.69 in the previous-year quarter.
Management said volumes increased 28% year-on-year in Q2 and 34% in the first half of FY27. The Central Province series recorded volume growth of 56% during the quarter, supporting the company's focus on proprietary alcohol brands.
Which business segments drove ASALCBR's quarterly revenue?
ASALCBR's alcohol segment generated revenue of ₹195.3 crore in Q2 FY27, up 14% year-on-year, and reported EBITDA of ₹16.8 crore with a 9% margin. The segment was supported by its IMFL proprietary business, which delivered revenue of ₹57.7 crore, up 39% year-on-year.
IMFL proprietary revenue represented around 30% of alcohol segment revenue. Its EBITDA margin stood at 10%, below management's long-term target range of 15% to 17%. The company attributed the near-term margin pressure to higher raw-material and packaging costs.
Within the alcohol portfolio, IMFL licensing revenue was ₹16.3 crore and was affected by a change in the arrangement with InBev. Indian-made liquor revenue was ₹57.8 crore, up 3%, while extra neutral alcohol revenue rose 21% to ₹44.8 crore.
The ethanol segment contributed ₹76.3 crore in revenue but reported an EBITDA margin of 1%. This left the alcohol segment as the main contributor to consolidated operating profit during the quarter.
Why were ASALCBR's margins lower during the quarter?
ASALCBR said higher costs for grain, glass bottles and PET bottles weighed on quarterly margins. CFO Dilip Kumar Inani said a substantial share of volume comes from the popular category, where demand and profitability are closely linked to commodity prices.
This cost sensitivity is important because popular-category products may have less immediate flexibility to absorb higher input prices. The company's Q2 results reflect this pressure: volume growth was strong, but EBITDA margin was 7%, lower than the 9% margin reported in the comparable quarter last year.
Management said grain prices could ease within a month as FCI rice supply arrives. That statement was made on the earnings call and reflects management's assessment of input conditions rather than a reported improvement in the Q2 numbers.
ASALCBR is also undertaking backward integration through malt maturation. Management said this initiative adds about ₹3 crore per month to inventory, indicating a working-capital requirement associated with the project before its intended operational benefits are realised.
Got a follow-up? Ask IRIS
What is ASALCBR's plan for proprietary brands and new markets?
ASALCBR maintained its FY27 expectation of around 30% to 35% growth in proprietary-brand sales. The company plans strategic entries into Karnataka and Andhra Pradesh by the end of FY27, while it continues to expand the availability of Arcana tequila across additional states.
Management said it would use first-year tequila market share of 4% to 5% of the Indian market as an indicator that the brand is progressing as intended. It also stated that registrations in additional states were expected before the New Year, subject to the relevant process being completed.
The company expects Culture and tequila to contribute around ₹10 crore to revenue in FY28. It also indicated that premium-brand advertising and branding may require at least ₹3 crore to ₹4 crore, and that around 5% of IMFL segment revenue may be directed towards brand building and development in coming years.
Management expects IMFL proprietary EBITDA margin to return to around 13% to 14% from Q3 FY28. It also plans price increases where possible in certain states, mostly from April onwards, though implementation depends on state-level conditions and approvals.
What does the Q2 result mean for investors and operations?
The Q2 FY27 result shows an operating mix in which the faster-growing proprietary alcohol business and rising volumes supported revenue, while commodity-linked costs constrained profitability. For investors, the central data points are the 7% revenue increase, the 26% decline in EBITDA to ₹17.7 crore, and the fall in earnings per share to ₹3.99.
The alcohol segment remains the key earnings driver, producing ₹16.8 crore of EBITDA compared with a 1% EBITDA margin in ethanol. The difference highlights the significance of proprietary-brand growth, product mix, raw-material costs and potential price actions to ASALCBR's consolidated margin profile.
The company's plans involve expansion into new states, investment in brands and backward integration. These initiatives can affect distribution expenses, inventory and capital deployment before their contribution to revenue or margin becomes visible in reported financials. The disclosed targets therefore provide a framework for tracking execution rather than confirmed future outcomes.
Conclusion
ASALCBR delivered higher Q2 FY27 revenue and volume growth, led by the alcohol segment and IMFL proprietary brands, but elevated costs for grain and packaging reduced operating profitability. Revenue reached ₹271.6 crore, while EBITDA margin was 7% and PAT was ₹8 crore.
The next reported developments to watch are the expected easing in grain costs following FCI rice supply, planned price actions from April where feasible, entry into Karnataka and Andhra Pradesh by FY27-end, and the planned start of malt-plant utilisation from Q3 FY28.