










Atharva Polyplast net worth rises, operating cash flow turns negative
Key highlights
- Atharva Polyplast’s shareholders’ funds rose to Rs 46.06 crore at 30 September 2026 from Rs 19.58 crore at 31 March 2026.
- Atharva Polyplast’s debt-to-equity declined to 0.10x from 0.50x as total borrowings fell 53% to Rs 4.59 crore.
- Atharva Polyplast reported negative operating cash flow of Rs 13.63 crore in H1 FY27, versus negative Rs 1.75 crore in H1 FY26.
- Atharva Polyplast recorded a Rs 15.88 crore H1 FY27 cash outflow for other non-current assets.
powered by IRIS
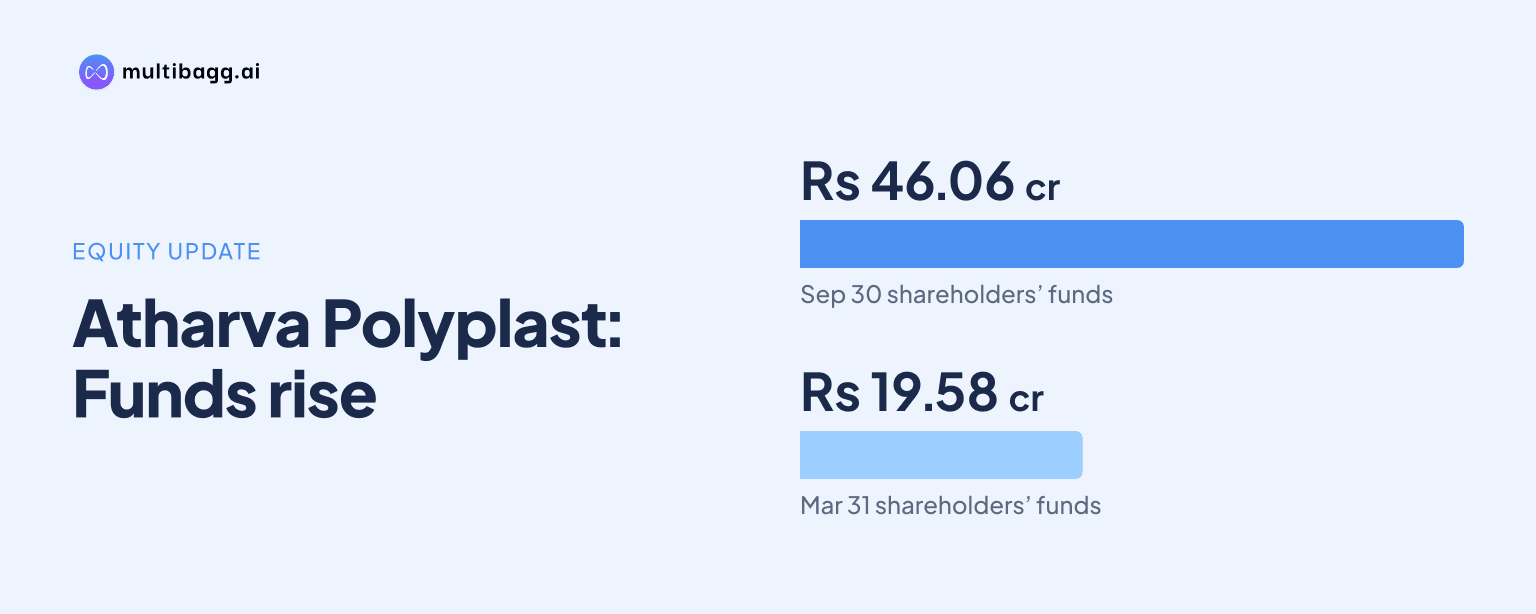
Atharva Polyplast Limited had net worth of Rs 46.06 crore at 30 September 2026 after its July 2026 IPO, while H1 FY27 net cash from operating activities was negative Rs 13.63 crore, alongside a Rs 15.88 crore outflow for other non-current assets. Debt-to-equity was 0.10x, down from 0.50x at 31 March 2026.
Know Atharva Poly-Plast inside out
Results, valuation, peers and who's buying, in one view.
How did the IPO change Atharva Polyplast’s balance sheet?
Atharva Polyplast’s shareholders’ funds rose to Rs 46.06 crore at 30 September 2026 from Rs 19.58 crore at 31 March 2026, an increase of Rs 26.48 crore. Share capital increased to Rs 16.85 crore from Rs 12.35 crore, while reserves and surplus rose to Rs 29.21 crore from Rs 7.23 crore.
The cash-flow statement records Rs 27 crore of equity issued, including premium, during H1 FY27 and Rs 4.71 crore of IPO expenses. Atharva Polyplast listed on BSE SME on 7 July 2026, and also reported profit after tax of Rs 4.38 crore for the half year.
Debt-to-equity fell to 0.10x from 0.50x, according to the presentation, as total borrowings declined 53%. Long-term borrowings were Rs 2.98 crore and short-term borrowings were Rs 1.61 crore at September 2026, compared with Rs 3.58 crore and Rs 6.18 crore respectively at March 2026.
Where did Atharva Polyplast’s capital appear on the asset side?
Atharva Polyplast’s largest asset movement was other non-current assets, which increased to Rs 17.34 crore at September 2026 from Rs 1.46 crore at March 2026. The Rs 15.88 crore increase matches the cash-flow statement’s outflow under the same line, although the presentation does not identify the assets’ composition.
Property, plant and equipment increased by Rs 0.73 crore to Rs 18.28 crore, while short-term loans and advances rose by Rs 2.96 crore to Rs 3.99 crore. Cash and bank balances on the balance sheet were Rs 5.43 crore at September 2026 versus Rs 2.71 crore at March 2026.
Inventories increased by Rs 0.15 crore to Rs 7.82 crore and trade receivables by Rs 0.32 crore to Rs 12.05 crore. On the funding side, trade payables declined by Rs 0.85 crore to Rs 8.88 crore, while other current liabilities increased by Rs 2.22 crore to Rs 4.63 crore.
Why was Atharva Polyplast’s operating cash flow negative in H1 FY27?
Atharva Polyplast reported operating profit before working capital of Rs 5.72 crore in H1 FY27, but working-capital and asset movements resulted in negative Rs 12.13 crore of cash generated from operations. After Rs 1.50 crore of income tax paid, net cash from operating activities was negative Rs 13.63 crore, compared with negative Rs 1.75 crore in H1 FY26.
The Rs 15.88 crore cash outflow for other non-current assets was the largest item and exceeded the Rs 5.72 crore operating profit before working capital. In H1 FY26, the corresponding outflow was Rs 1.23 crore, making the year-on-year increase in this cash use Rs 14.65 crore.
Short-term loans and advances consumed Rs 2.96 crore in H1 FY27, against Rs 0.32 crore a year earlier. Trade receivables used Rs 0.32 crore, inventories used Rs 0.14 crore and trade payables used Rs 0.85 crore, partly offset by a Rs 2.22 crore increase in other current liabilities.
Got a follow-up? Ask IRIS
Did Atharva Polyplast’s profits convert into operating cash?
No. Atharva Polyplast reported revenue from operations of Rs 36.69 crore and profit after tax of Rs 4.38 crore in H1 FY27, while net operating cash flow was negative Rs 13.63 crore. Revenue rose 77.5% from Rs 20.67 crore in H1 FY26, whereas profit after tax was lower than Rs 4.72 crore a year earlier.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 7.45 crore in H1 FY27, marginally above Rs 7.37 crore in H1 FY26. EBITDA margin was 20.3%, compared with 35.7% in H1 FY26 and 20.7% for FY26; the presentation attributes the year-on-year margin movement to raw-material intensity of about 75% of revenue versus about 54% in H1 FY26.
The half-year comparison differs from the sequential trend. Revenue rose from Rs 33.72 crore in H2 FY26 to Rs 36.69 crore in H1 FY27, EBITDA increased from Rs 3.88 crore to Rs 7.45 crore, and profit after tax rose from Rs 1.75 crore to Rs 4.38 crore, even as cash conversion remained negative.
How was Atharva Polyplast’s cash balance funded in H1 FY27?
Atharva Polyplast’s financing inflow of Rs 16.27 crore outweighed its operating cash outflow and produced a Rs 2.72 crore increase in cash and cash equivalents. Closing cash and cash equivalents were Rs 5.06 crore, compared with opening cash and cash equivalents of Rs 2.33 crore.
The financing statement includes the Rs 27 crore equity issue, Rs 4.57 crore reduction in short-term borrowings, Rs 0.60 crore reduction in long-term borrowings, Rs 0.86 crore interest paid and Rs 4.71 crore of IPO expenses. Net cash from investing activities was positive Rs 0.08 crore after Rs 1.64 crore of property, plant and equipment purchases, Rs 1.43 crore of capital-investment subsidy and Rs 0.30 crore of interest received.
Management reported 67% capacity utilisation in H1 FY27 and a 5.8x brownfield expansion runway on owned land. Its disclosed plans include targeting 15% to 20% of long-term revenue from engineering services and a Rs 201 crore chair-mechanism opportunity based on a 30% share of a Rs 670 crore market.
Conclusion
Atharva Polyplast entered the post-listing period with shareholders’ funds of Rs 46.06 crore, total borrowings of Rs 4.59 crore and debt-to-equity of 0.10x. However, the H1 FY27 cash-flow statement shows that reported revenue of Rs 36.69 crore and profit after tax of Rs 4.38 crore did not translate into operating cash, principally amid the Rs 15.88 crore other non-current-assets movement.
The next disclosure to watch is the composition and cash implications of the Rs 17.34 crore other non-current-assets balance at September 2026, which the presentation does not detail. Management’s stated mechanisms, engineering-services and co-design plans, including five years of assured business for the Toro programme, will also determine how the new equity base and 67% capacity utilisation are deployed.