










AXISCADES maps Rs 660-705 crore H2 revenue from order book
Key highlights
- AXISCADES mapped H2 revenue of Rs 660-705 crore from its current order book.
- AXISCADES placed Q3 revenue at Rs 285-300 crore and Q4 revenue at Rs 375-405 crore.
- Defence Research and Development Organisation work was targeted to contribute about Rs 270 crore in H2.
- AXISCADES identified supply-chain delays in strategic electronics as the main execution risk.
powered by IRIS
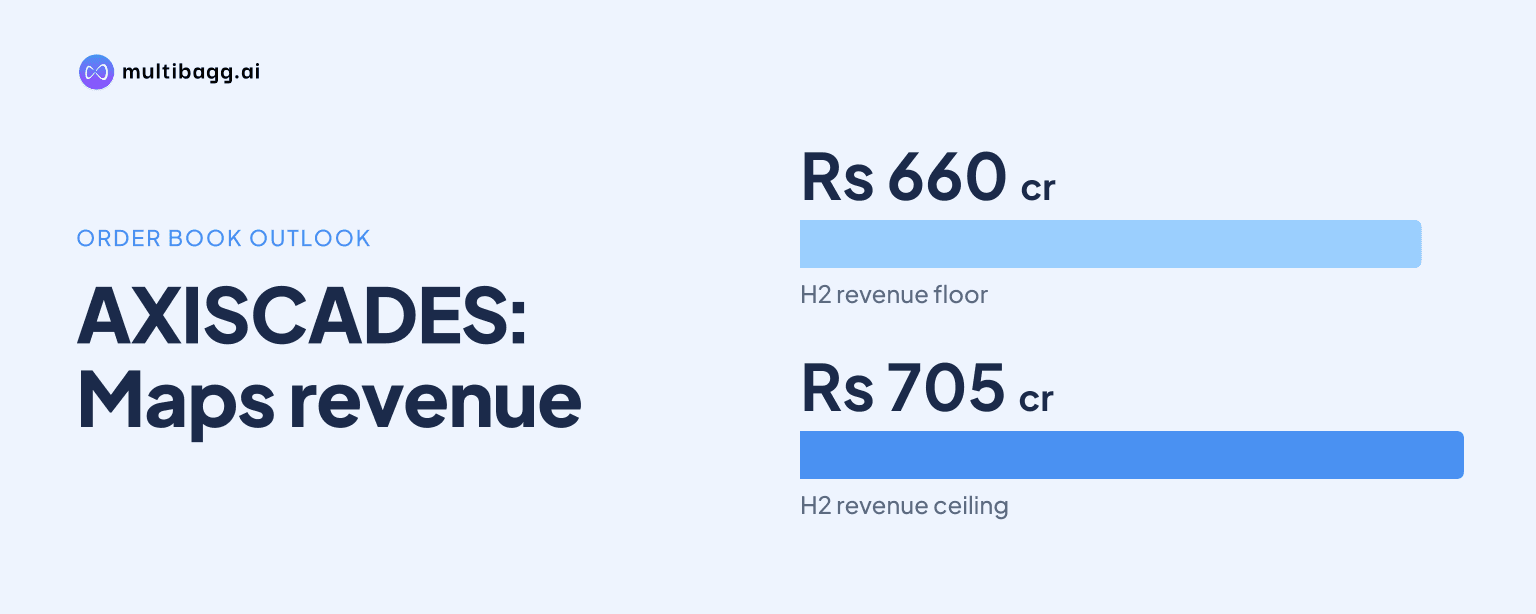
AXISCADES said its current order book supports an H2 revenue aim of Rs 660-705 crore, comprising Q3 revenue of Rs 285-300 crore and Q4 revenue of Rs 375-405 crore. Management said the estimate comes from existing Defence Research and Development Organisation, Ministry of Defence, XiDA and aerospace businesses, rather than future acquisitions.
Know AXISCADES Technologies inside out
Results, valuation, peers and who's buying, in one view.
What H2 revenue range did AXISCADES set out?
AXISCADES set out an order-book-based H2 range of Rs 660-705 crore, with a lower Q3 band of Rs 285-300 crore and a higher Q4 band of Rs 375-405 crore. Dr. Sampath Ravi Narayanan described these figures as the company’s “approximate thinking,” rather than delivery guidance, and said they were derived from the current order book.
The Q4 range of Rs 375-405 crore is Rs 90-105 crore above the Q3 range of Rs 285-300 crore at each respective endpoint. That sequential increase reflects management’s stated expectations for higher Defence Research and Development Organisation, Ministry of Defence, XiDA and aerospace revenue in Q4, although it also embeds a broader Rs 30 crore range than Q3’s Rs 15 crore range.
The company’s H2 framing came after an analyst said the remaining two quarters would require about Rs 500 crore of revenue. Management did not endorse that calculation in its response, instead providing the Rs 660-705 crore H2 range and saying its estimate was based on existing order-book visibility.
How is AXISCADES splitting H2 revenue by business?
AXISCADES said the largest disclosed H2 contribution should come from Defence Research and Development Organisation work, at about Rs 270 crore, followed by XiDA at roughly Rs 165-186 crore, aerospace at Rs 126 crore and direct Ministry of Defence business at Rs 105 crore. The component figures are management’s aims from the current order book, not formal guidance.
The disclosed vertical figures point to a Rs 666-687 crore aggregate, whereas the broader company range was Rs 660-705 crore. AXISCADES did not provide a reconciliation between those two calculations on the call, so the variance should not be treated as an additional revenue forecast or a change in the company’s stated Rs 660-705 crore H2 range.
Within the split, Defence Research and Development Organisation revenue is expected to rise by Rs 30 crore, from Rs 120 crore in Q3 to Rs 150 crore in Q4. Direct Ministry of Defence revenue is expected to increase by Rs 15 crore, from Rs 45 crore to Rs 60 crore, while aerospace is expected to rise by Rs 24 crore, from Rs 51 crore to Rs 75 crore.
Which AXISCADES businesses underpin the H2 plan?
AXISCADES said the H2 range is based on existing businesses and excludes revenue from anything it may acquire in the future. In response to a direct question, management confirmed that the revenue expectation rests on the current order book across defence, XiDA and aerospace operations.
The defence plan contains two separately identified channels: Rs 270 crore from Defence Research and Development Organisation work and Rs 105 crore from direct Ministry of Defence business. AXISCADES also said it has technology-transfer arrangements, or TOTs, for products including through-wall radar, ground penetration radar and direction finders, for which it said it has process, people, integration and testing capabilities.
For XiDA, management indicated a Q3 aim described as roughly Rs 75-81 crore and a Q4 range of Rs 90-105 crore. XiDA therefore carries one of the larger stated ranges within the H2 outlook, at about Rs 165-186 crore, and management linked its uncertainty to supply availability for strategic-electronics components.
Aerospace is the most tightly framed component of the disclosed split, at Rs 51 crore for Q3 and Rs 75 crore for Q4. Management said aerospace would be “more or less intact” and would not have much margin for error, unlike XiDA, where it explicitly provided a range rather than a fixed quarterly amount.
Got a follow-up? Ask IRIS
What could cause AXISCADES to miss the revenue or margin aims?
AXISCADES identified supply-chain delays, particularly for electronics and strategic-electronics components used in XiDA and defence, as the principal bottleneck. Management said it was seeking to stock components in advance and may sometimes pay a premium, which could affect cost of goods sold and margins; it described a possible margin effect of plus or minus 2%.
The company said it could control three operating components: cost of goods sold, employee cost and other costs. It said employee cost for the next two quarters was expected to be in the range management described as 48 to 54, while other costs linked to the Devanahalli facility were stabilising or expected to decline.
Management separately named transaction costs, legal costs, acquisition-related costs and employee stock option plan, or ESOP, costs as variables requiring attention. It said ESOP costs depend on matters including the number of shares, packaging and vesting conditions, while interest, depreciation and other below-EBITDA items meant it had not completed detailed work on profit after tax, or PAT.
On earnings before interest, tax, depreciation and amortisation, or EBITDA, AXISCADES said it was confident in its work toward the stated aim, but it declined to offer the same assurance for PAT. Management said a move to the new Devanahalli facility had introduced depreciation and other costs that still needed to be calculated, alongside interest costs.
How does the H2 outlook fit AXISCADES’ wider execution plans?
AXISCADES’ H2 revenue plan is focused on operations already in hand, while a separate aerospace engineering-services divestment was targeted for completion on or before February. Management said the timing moved from November because a new company structure, global entity set-up and certain Ministry of Defence clearances were required before employees, contracts and business could be transferred.
Management said Rs 1,395 crore of post-tax divestment consideration was guaranteed, representing 72% of total consideration, and listed receipts of Rs 121 crore in October, Rs 32 crore in November, Rs 504 crore in February, Rs 56 crore in July and Rs 682 crore in December. It also said it expected to record an extraordinary gain of Rs 1,100 crore, though those proceeds are distinct from the H2 operating-revenue outlook.
The divestment discussion also highlighted the distinction between revenue execution and financing. AXISCADES said net debt was around Rs 525 crore, largely following the Rs 200 crore borrowing for the Cloud Wave acquisition in September, of which Rs 85 crore had already been repaid; management said remaining debt would mostly be repaid from divestment consideration.
Conclusion
AXISCADES has provided an unusually detailed view of its H2 order-book expectations: Rs 660-705 crore overall, with the largest identified contribution from Defence Research and Development Organisation work at Rs 270 crore. The disclosed business figures imply rising revenue from Q3 to Q4, led by defence, XiDA and aerospace, but management consistently characterised the figures as aims rather than formal guidance.
The next issue to watch is whether component availability allows XiDA and defence deliveries to meet the stated Q3 and Q4 bands without a material cost premium. Investors can also watch the planned completion of the aerospace engineering-services divestment on or before February, including the Rs 504 crore payment management said was scheduled for that month.