










AXISCADES targets 20%-plus Q4 EBITDA margin after costs ease
Key highlights
- AXISCADES is targeting a 15-16% EBITDA margin in Q3 FY27 and more than 20% in Q4 FY27.
- Retained-business revenue was Rs 195.6 crore in Q2 FY27, up 30% year on year.
- Management expects ESOP expense to decline to about Rs 6 crore a quarter from Q3 FY27.
- Legal and professional costs are expected to normalise from Rs 14.5 crore to about Rs 4-5 crore a quarter.
powered by IRIS
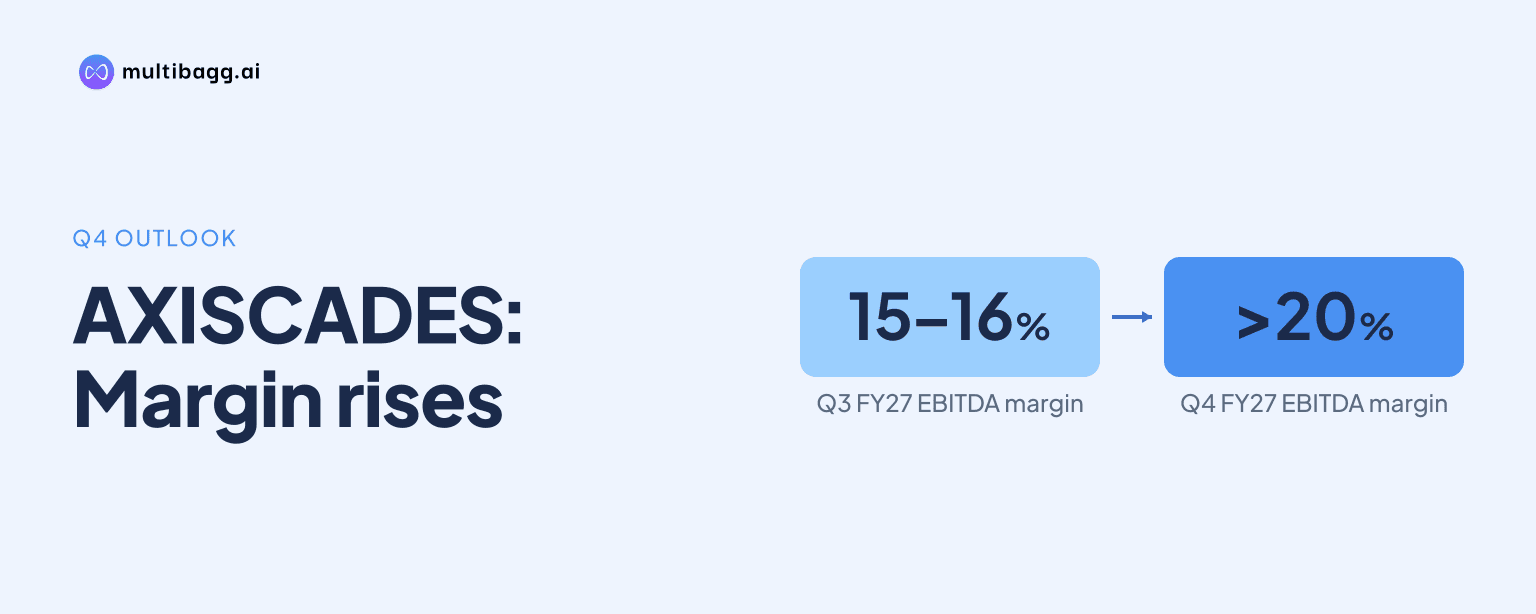
AXISCADES is targeting a 15-16% EBITDA margin in Q3 FY27 and more than 20% in Q4 FY27, after employee stock option plan charges and transaction costs decline while its core businesses are planned to grow sequentially. Management expects Q4 revenue to rise about 30% from Q3 and called that period a benchmark quarter.
Know AXISCADES Technologies inside out
Results, valuation, peers and who's buying, in one view.
What EBITDA margins is AXISCADES targeting in Q3 and Q4 FY27?
AXISCADES is aiming for an EBITDA margin of about 15-16% in Q3 FY27 and 20%-plus in Q4 FY27, with management indicating a potential variation of roughly 1% to 1.5%. Management described the targets as its current plan rather than formal guidance, and said the Q4 objective would be measured after ESOP charges.
Management expects Q3 revenue in its core businesses of defence, XiDA and aerospace to increase by at least 30% from Q2 FY27, with a possible range of 45-50%. It then expects Q4 revenue to rise about 30% from the Q3 base. The Chairman called Q3 AXISCADES’ first normal and profitable quarter after the transformation work and described Q4 as the benchmark for the reshaped company.
The near-term margin plan excludes a material contribution from space. AXISCADES said its space partnerships are in place but expects the business to begin generating revenue only in FY28 and to become EBITDA-positive thereafter. The Q3 and Q4 targets therefore depend on defence, XiDA and aerospace revenue, lower costs and a reduced ESOP burden.
Why did AXISCADES report a continuing-operations loss in Q2 FY27?
AXISCADES reported a Rs 48.1 crore loss from continuing operations in Q2 FY27 after recording a one-time, non-cash impairment of Rs 38.4 crore in goodwill and intangibles, mainly related to ADD Solutions. The company has offered ADD Solutions for solvent liquidation, and management said the impairment removed legacy carrying values from the accounts.
At the consolidated level, AXISCADES reported profit after tax of Rs 47.3 crore in Q2 FY27, compared with a Rs 14.8 crore loss in Q1 FY27 and profit of Rs 23.1 crore in Q2 FY26. Discontinued operations contributed Rs 95.4 crore after tax, including a pre-tax exceptional gain of Rs 129.3 crore after goodwill related to divested businesses was netted off.
Exceptional write-offs totalled Rs 58.3 crore, including Rs 19.9 crore of Epcogen goodwill recorded in discontinued operations. Management said these charges were non-cash, below EBITDA and unrelated to customer orders or cash flows. Reported EBITDA was Rs 11.4 crore, while EBITDA before the Rs 12 crore half-year ESOP charge was Rs 23.4 crore.
Got a follow-up? Ask IRIS
How is revenue growth expected to support AXISCADES’ margin recovery?
AXISCADES reported retained-business revenue of Rs 195.6 crore in Q2 FY27, up 30% year on year and 7% sequentially, including Rs 16.5 crore from Cloud Wave after its consolidation began on 10 September. Retained revenue represented 54% of group revenue in H1 FY27, compared with 45% a year earlier, following the divestment process.
Consolidated Q2 FY27 revenue was a record Rs 359.1 crore, up 20% year on year and 3.6% sequentially. Under Indian Accounting Standard 105, or Ind AS 105, Rs 163.5 crore was classified as discontinued operations and Rs 195.6 crore as retained business. For H1 FY27, consolidated revenue rose 30% to Rs 705.7 crore and retained revenue rose 55% to Rs 378.9 crore.
Defence reported a Q2 FY27 EBITDA margin of 17.6%, while XiDA reported a 27.6% EBITDA margin for H1 FY27. The Chairman said defence, public-sector undertaking business and XiDA together generated Rs 29 crore of EBITDA at a 23% margin in Q2. Management plans for XiDA, defence and aerospace each to operate at around a 20% EBITDA margin at the vertical level from Q3 FY27.
Cloud Wave was earnings-accretive in its first quarter within AXISCADES, and management expects its full-quarter revenue to contribute in Q3 and Q4. That contribution is relevant because Cloud Wave added Rs 16.5 crore to Q2 retained revenue despite being consolidated only from 10 September. Management’s sequential growth assumptions for Q3 and Q4 rely on this expanded aerospace revenue base alongside growth in defence and XiDA.
Which costs must decline for AXISCADES to meet its targets?
AXISCADES expects a cost reset before the second phase of the Akkodis divestment closes, taking corporate overhead to around Rs 12 crore a quarter from about Rs 15 crore in the listed parent’s retained business. Management said the corporate structure remains necessary to support the planned growth of the new portfolio, although retained-business revenue has not yet fully absorbed those costs.
Management expects the ESOP charge to run at about Rs 6 crore a quarter from Q3 FY27, roughly half the Q2 level cited in the call. The Chairman said ESOPs would continue as a recurring employee expense used to attract and retain talent, but the charge is planned to fall from about 50% of EBITDA in Q2 to roughly 20% in Q3 and a single-digit percentage in Q4.
Legal and professional expenses of Rs 14.5 crore are expected to normalise to about Rs 4-5 crore a quarter. Management attributed the elevated costs to the Akkodis sale, the ADD Solutions and Epcogen closures, and acquisition activity. It said transaction costs tied to the sale should end, although future acquisitions can still create legal and transaction expenses.
Conclusion
AXISCADES’ margin plan rests on a sequence of higher revenue in defence, XiDA and aerospace, lower corporate overhead, reduced legal costs and a smaller ESOP charge relative to EBITDA. Q2 FY27 illustrated the difference between vertical performance and the enterprise result: defence recorded a 17.6% EBITDA margin while the retained business also absorbed restructuring-related expenses and a Rs 38.4 crore non-cash impairment.
The next disclosed milestone is the planned Phase 2 closure of the Akkodis divestment in February or earlier, which AXISCADES expects to complete in Q4 FY27 after a three-month regulatory delay. Management expects a further Rs 1,100 crore one-time gain on that closing, while Q3 and Q4 results will show whether retained-business revenue can absorb the new corporate cost base and deliver the stated margin targets.