










AXISCADES Technologies Ltd Reports Record ₹359.1 Crore Revenue
Key highlights
- AXISCADES reported record Q2 FY2027 consolidated revenue of ₹359.1 crore, up 20% year-on-year.
- Retained business revenue rose 30% year-on-year to ₹195.6 crore in Q2 FY2027.
- Reported Q2 profit after tax was ₹47.3 crore, including a ₹95.4 crore post-tax contribution from discontinued operations.
- AXISCADES targets ₹600 crore to ₹720 crore of execution over the next two quarters, subject to component lead times of 12 to 18 months.
powered by IRIS
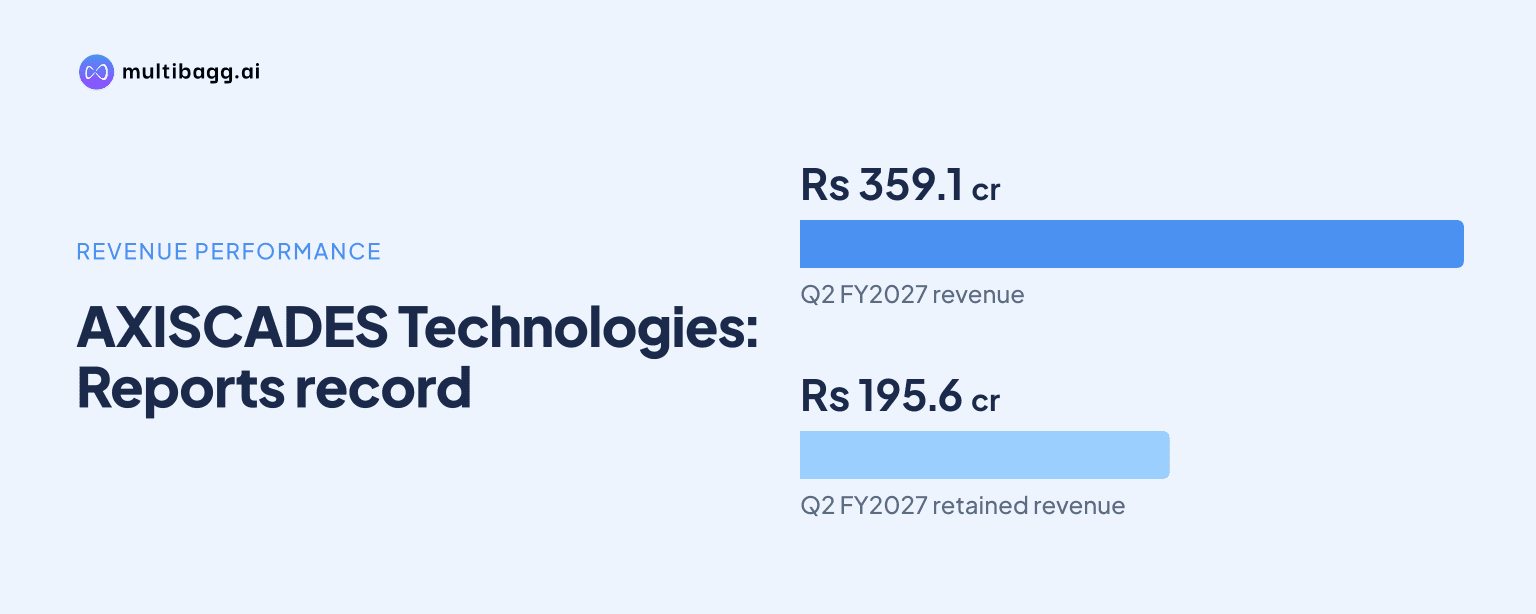
AXISCADES Technologies Ltd reported its highest-ever quarterly revenue of ₹359.1 crore in Q2 FY2027, up 20% year-on-year, although profitability in continuing operations was affected by non-cash impairment and other charges. Reported profit after tax was ₹47.3 crore, supported by a ₹95.4 crore post-tax contribution from discontinued operations.
Know AXISCADES Technologies inside out
Results, valuation, peers and who's buying, in one view.
What did AXISCADES report for Q2 FY2027?
AXISCADES reported consolidated revenue of ₹359.1 crore for Q2 FY2027, marking 20% year-on-year growth and 3.6% sequential growth. The quarter was the company's second consecutive record revenue period, according to management's earnings-call comments released on November 16, 2026.
Retained business revenue rose 30% year-on-year to ₹195.6 crore. For the first half of FY2027, consolidated revenue reached ₹705.7 crore, up 30% year-on-year, while retained revenue increased 55% to ₹378.9 crore. These figures show that the business retained after portfolio actions formed a growing part of the reported performance.
Reported EBITDA was ₹11.4 crore in the quarter and also ₹11.4 crore for the first half. Management also cited pre-ESOP EBITDA of ₹23.4 crore, with ESOP expense accounting for about half of that measure. The call materials separately noted pressure on continuing-operations earnings from impairment and other charges.
Why was reported profit higher despite pressure in continuing operations?
AXISCADES reported profit after tax of ₹47.3 crore in Q2 FY2027, compared with a loss of ₹14.8 crore in the preceding quarter and profit of ₹23.1 crore in Q2 FY2026. The reported result was principally supported by discontinued operations rather than by the underlying continuing business.
Discontinued operations contributed ₹95.4 crore after tax. This included a pre-tax exceptional gain of ₹129.3 crore after netting goodwill associated with divested businesses. The company said continuing operations posted a loss after non-cash impairment and other charges, making the distinction between reported profit and operating profitability important for investors assessing the quarter.
For the first half, profit before tax rose 10.1% to ₹70.8 crore and reported profit after tax stood at ₹32.5 crore. The first phase of the Akkodis divestment was completed during the quarter, which formed part of the corporate actions affecting the reported financial statements.
Which business actions shaped the quarter?
AXISCADES said Q2 FY2027 involved execution across divestment, acquisition and operational consolidation. Alongside closing the first phase of the Akkodis divestment, the company acquired and began consolidating Cloud Wave.
It also announced the acquisition of ITSJ under XIDA. These actions occurred while the company delivered record revenue, but they also mean that quarterly comparability should be read alongside changes in the group structure and the contribution from discontinued operations.
Management said the full-year target of about ₹1,150 crore includes prorated contributions from acquisitions. It also raised defence forecast visibility to about ₹5,000 crore and said XIDA could record triple-digit growth in the current quarter. These were management statements on demand visibility and business momentum, not reported revenue outcomes.
Got a follow-up? Ask IRIS
What is AXISCADES targeting for the next two quarters?
AXISCADES said it had executed about ₹379 crore so far and was targeting execution of ₹600 crore to ₹720 crore over the next two quarters. Management qualified this target by citing supply-chain constraints, particularly component lead times of 12 to 18 months.
The company described Q3 as potentially its first normal and profitable quarter after restructuring, while identifying Q4 as a benchmark period. It also indicated that the full-year revenue target is about ₹1,150 crore, including prorated acquisition contributions. These statements are management targets and remain dependent on operational execution and component availability.
The company cited total executable orders of about ₹1,000 crore, including the portion already executed. Strong defence demand was highlighted on the call, but component procurement timing remains a practical constraint for converting demand and orders into completed revenue.
How does the update matter for investors and the defence engineering sector?
The quarter gives investors two distinct data points. Revenue growth and retained-business growth were strong, while reported profit was materially aided by a divestment-related gain. The continuing-operations loss and the reported EBITDA of ₹11.4 crore indicate that recovery in the core operating result remains a central issue to monitor.
AXISCADES operates in defence, aerospace and deep-tech engineering areas, where order execution can be affected by specialised component availability. The disclosed 12- to 18-month component lead times show why order visibility does not automatically result in immediate revenue recognition. Management's execution range for the next two quarters is therefore tied to supply-chain delivery.
The company will be added to the MSCI India Domestic Small Cap Index effective November 30 and is already part of the Nifty India Defence Index. Index inclusion is a factual change in the company's market classification, while the earnings call focused on restructuring, acquisition integration and the return to normalised profitability as the nearer operating priorities.
Conclusion
AXISCADES delivered record Q2 FY2027 revenue of ₹359.1 crore and maintained strong growth in its retained business, but the reported ₹47.3 crore profit depended on a ₹95.4 crore post-tax contribution from discontinued operations. The result therefore combines expanding revenue with a continuing need to improve the profitability of ongoing operations.
Investors will next watch execution against the ₹600 crore to ₹720 crore target for the next two quarters, progress toward the approximately ₹1,150 crore full-year target, and the effect of 12- to 18-month component lead times. Management has also identified Q3 as a potential normal and profitable quarter and Q4 as a benchmark period.