










Balaji Amines core chemical ROCE reaches 13% during FY26
Key highlights
- Balaji Amines reported FY26 core chemical ROCE of 13%, up from 12% in FY25.
- Core chemical EBIT rose to Rs 227 crore in FY26 from Rs 207 crore in FY25.
- BSCL capital work in progress in the FY26 ROCE bridge was Rs 343 crore, compared with Rs 116 crore in FY25.
- Balaji Amines reported Rs 438.17 crore of BSCL work in progress at September 2026.
powered by IRIS
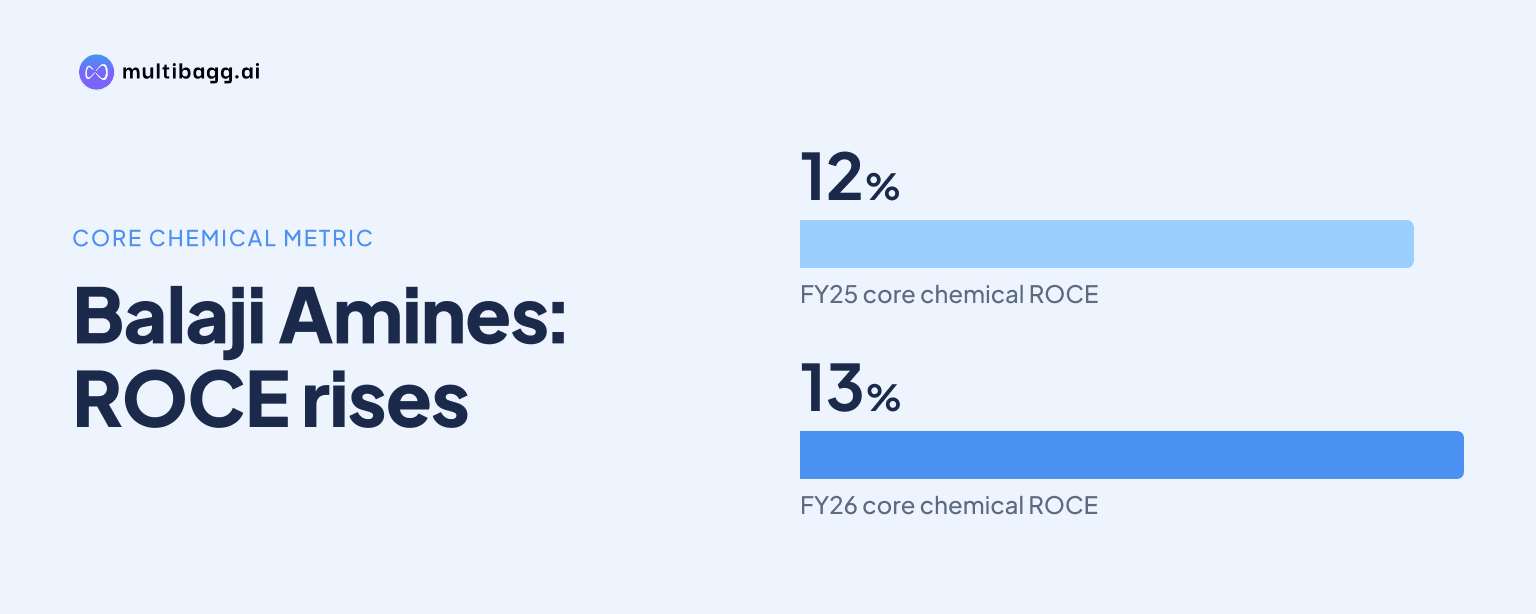
Balaji Amines Limited reported core chemical return on capital employed (ROCE) of 13% in FY26, up from 12% in FY25, after core chemical earnings before interest and tax (EBIT) rose to Rs 227 crore from Rs 207 crore while the defined capital base reached Rs 1,695 crore.
Know Balaji Amines inside out
Results, valuation, peers and who's buying, in one view.
How did Balaji Amines calculate its 13% core ROCE?
Balaji Amines calculated FY26 core chemical ROCE by dividing Rs 227 crore of core chemical EBIT by Rs 1,695 crore of core chemical capital employed. It began with total consolidated capital employed of Rs 2,285 crore, compared with Rs 2,029 crore in FY25, and made specified adjustments for hotel operations and capital work in progress.
The FY26 bridge deducted Rs 95 crore invested in Hotel Balaji Sarovar and other items, then added back Rs 35 crore of losses in those operations. It also deducted Rs 187 crore of capital work in progress at Greenfield Unit 4, Unit 3 and Unit 1, and Rs 343 crore of Balaji Speciality Chemicals Ltd (BSCL) capital work in progress.
The resulting core chemical capital base increased by Rs 29 crore from FY25, while core chemical EBIT increased by Rs 20 crore. Balaji Amines separately reported consolidated entity-level ROCE of 14% in FY26, versus 11% in FY25, alongside its 13% and 12% core chemical ROCE figures.
What changed in Balaji Amines' earnings and returns in FY26?
Balaji Amines' core chemical EBIT increased to Rs 227 crore in FY26 from Rs 207 crore in FY25, while the core capital base rose to Rs 1,695 crore from Rs 1,666 crore. The presentation consequently shows core chemical ROCE rising by 1 percentage point to 13%.
At the consolidated level, EBIT was Rs 238 crore in FY26 compared with Rs 217 crore in FY25. After deducting EBIT losses specific to Hotel Balaji Sarovar and other items of Rs 11 crore in FY26 and Rs 10 crore in FY25, Balaji Amines derived the core chemical EBIT figures used in the ROCE calculation.
The wider 2026 performance figures also improved from 2025, although they remained below 2024 levels. Revenue was Rs 1,454 crore in 2026, up from Rs 1,430 crore in 2025 but below Rs 1,671 crore in 2024; earnings before interest, tax, depreciation and amortisation (EBITDA) were Rs 294 crore, against Rs 265 crore and Rs 353 crore respectively.
Profit after tax was Rs 169 crore in 2026, compared with Rs 159 crore in 2025 and Rs 232 crore in 2024. EBITDA margin increased to 20.24% from 18.5%, profit-after-tax margin rose to 11.64% from 11.1%, and return on equity increased to 9.17% from 8.6%.
Got a follow-up? Ask IRIS
How much capital did Balaji Amines exclude from core ROCE?
Balaji Amines' FY26 capital bridge removed Rs 625 crore in hotel investments and project work in progress, before adding back Rs 35 crore of hotel and other losses. That left core chemical capital employed of Rs 1,695 crore, or Rs 590 crore below the Rs 2,285 crore consolidated capital employed figure.
The largest FY26 adjustment was Rs 343 crore of BSCL capital work in progress, followed by Rs 187 crore at the company's other units and Rs 95 crore of Hotel Balaji Sarovar and other investments. In FY25, the equivalent balances were Rs 116 crore at BSCL, Rs 173 crore at other units and Rs 117 crore in hotel and other investments.
BSCL work in progress in the ROCE bridge increased by Rs 227 crore between FY25 and FY26, whereas the other-unit work-in-progress balance rose by Rs 14 crore. Hotel and other investments declined by Rs 22 crore, while the loss add-back fell by Rs 8 crore from Rs 43 crore to Rs 35 crore.
The 13% measure is therefore Balaji Amines' return calculation for capital assigned to core chemicals, rather than a return calculated on all Rs 2,285 crore of consolidated capital employed. The presentation also provides the 14% consolidated ROCE measure for FY26 without applying the core-business capital classification.
Which projects account for the capital work in progress?
Balaji Amines said capital work in progress of Rs 78.54 crore across various units at the quarter and half year ended September 2026 mainly related to an N-Methyl Morpholine (NMM) plant under development. The presentation does not disclose a commissioning date, production capacity, revenue target or return target for the NMM plant.
BSCL had capital work in progress of Rs 438.17 crore at September 2026, allocated to greenfield and brownfield projects. The greenfield project is intended to manufacture hydrogen cyanide, sodium cyanide, ethylenediaminetetraacetic acid, its sodium salt and other advanced chemical products, while the brownfield work concerns ethylenediamine-based chemical production.
The September 2026 project balances are not directly reconciled to the FY26 ROCE bridge, which lists Rs 187 crore at the company's units and Rs 343 crore at BSCL. Balaji Amines identifies the projects behind the September balances, but does not explain the difference between the Rs 516 crore work-in-progress total in the FY26 bridge and the Rs 516.71 crore total reported for September 2026.
Hotel Balaji Sarovar is the other material non-core item in the calculation. The hotel commenced operations in October 2013 with Rs 110 crore invested through debt and equity, and its Q2 and H1 FY27 operating matrix reported 129 rooms, Rs 7.17 crore of revenue, 67% occupancy, an average daily rate of Rs 4,922 and revenue per available room of Rs 3,288.
Conclusion
Balaji Amines' FY26 presentation shows core chemical ROCE rising to 13% from 12% as core EBIT increased by Rs 20 crore and the defined core chemical capital base increased by Rs 29 crore. The calculation excludes specified hotel investments and unfinished projects, while the company separately reported consolidated ROCE of 14% for FY26.
The next item to watch is the conversion of Rs 78.54 crore of work in progress associated mainly with NMM and Rs 438.17 crore at BSCL into operating assets. Balaji Amines has identified BSCL's greenfield and brownfield product plans, but has not disclosed commissioning dates, sales targets, return targets or a reconciliation of the September 2026 balances to the FY26 ROCE bridge.