










Balaji Amines Limited H1 FY27 PAT nearly doubles, margin hits 24%
Key highlights
- Balaji Amines reported H1 FY27 consolidated PAT of Rs 146 crore, compared with Rs 74 crore in H1 FY26.
- H1 FY27 consolidated EBITDA margin increased to 24% from 18% a year earlier.
- H1 FY27 consolidated revenue rose to Rs 933 crore from Rs 715 crore.
- Q2 FY27 consolidated revenue was Rs 472 crore and EBITDA was Rs 106 crore.
powered by IRIS
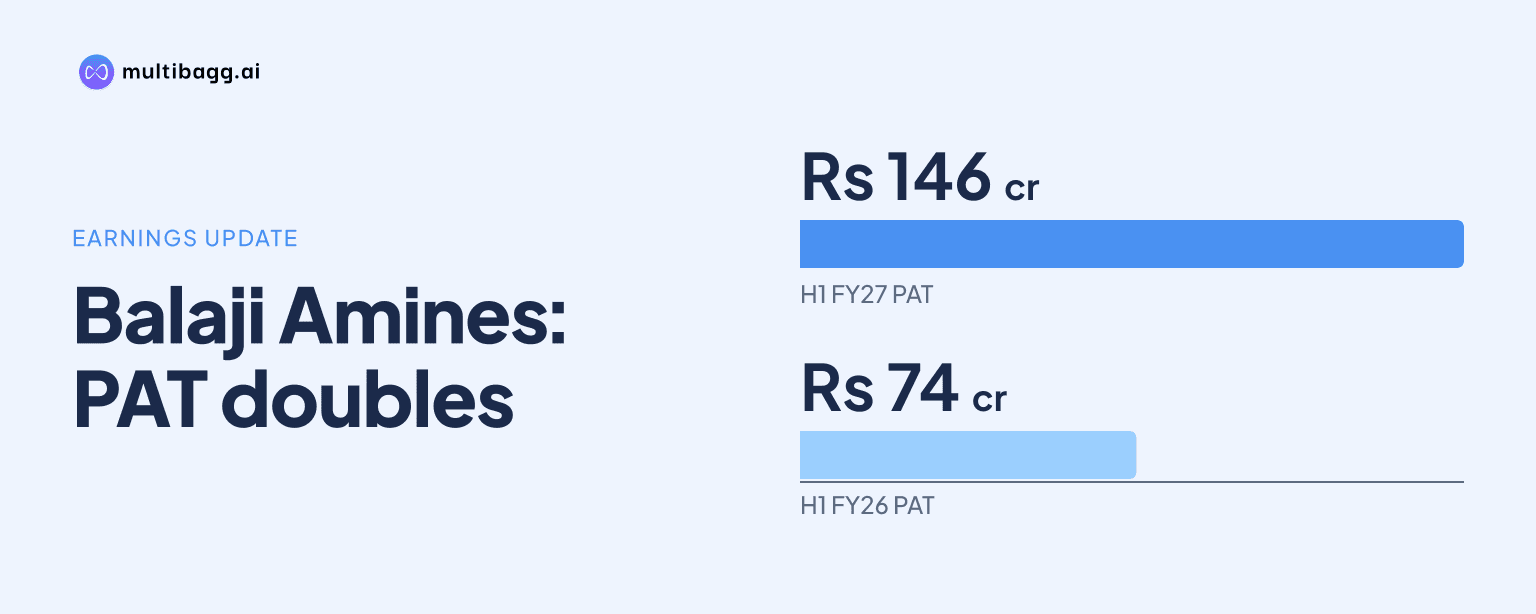
Balaji Amines Limited reported consolidated profit after tax (PAT) of Rs 146 crore in the first half of fiscal year 2027 (H1 FY27), up from Rs 74 crore in H1 FY26, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin rose to 24% from 18%. Consolidated revenue increased 30% to Rs 933 crore.
Know Balaji Amines inside out
Results, valuation, peers and who's buying, in one view.
How did Balaji Amines perform in H1 FY27?
Balaji Amines reported H1 FY27 consolidated revenue of Rs 933 crore, EBITDA of Rs 227 crore and PAT of Rs 146 crore, compared with Rs 715 crore, Rs 131 crore and Rs 74 crore respectively in H1 FY26. Earnings per share rose to Rs 43.89 from Rs 22.39 over the same periods.
Profit grew faster than revenue in the half year. EBITDA increased by Rs 96 crore, or 73%, while PAT rose by Rs 72 crore, or 97%, against a Rs 218 crore increase in revenue. Consolidated profit before tax reached Rs 196 crore from Rs 101 crore, while tax increased to Rs 50 crore from Rs 27 crore.
What changed in Balaji Amines’ H1 FY27 margins?
Balaji Amines’ consolidated EBITDA margin increased by 6 percentage points to 24% in H1 FY27 from 18% in H1 FY26, while PAT margin also increased by 6 percentage points to 16% from 10%. The margin change accompanied a rise in EBITDA to Rs 227 crore while revenue reached Rs 933 crore.
The income statement shows raw-material costs rose to Rs 518 crore from Rs 397 crore and employee expenses increased to Rs 52 crore from Rs 40 crore. Other expenses declined to Rs 136 crore from Rs 147 crore despite higher revenue, but the presentation does not provide a product-wise pricing, volume or cost bridge for the six-month margin movement.
The standalone business recorded a similar result, with revenue rising to Rs 863 crore from Rs 643 crore and EBITDA increasing to Rs 213 crore from Rs 121 crore. Standalone PAT was Rs 141 crore versus Rs 71 crore, and its EBITDA margin rose to 25% from 19%, one percentage point above the consolidated H1 FY27 margin.
How did Balaji Amines’ Q2 FY27 compare with Q1 FY27?
Balaji Amines reported Q2 FY27 consolidated revenue of Rs 472 crore, up 36% year on year from Rs 348 crore and 2% from Rs 461 crore in Q1 FY27. Q2 EBITDA was Rs 106 crore, up 58% from Rs 67 crore a year earlier but below Rs 121 crore in the preceding quarter.
Q2 EBITDA margin was 22%, compared with 19% in Q2 FY26 and 26% in Q1 FY27. PAT was Rs 67 crore, up 82% from Rs 37 crore in Q2 FY26 but down from Rs 78 crore in Q1 FY27; PAT margin was 14%, against 11% a year earlier and 17% sequentially.
The standalone operation showed the same sequential pattern. Q2 FY27 revenue was Rs 434 crore versus Rs 429 crore in Q1 FY27, while EBITDA declined to Rs 103 crore from Rs 110 crore and PAT fell to Rs 69 crore from Rs 72 crore. Standalone EBITDA margin moved to 24% from 26% over the two quarters.
Got a follow-up? Ask IRIS
What do Balaji Amines’ cash flow and balance sheet show?
Balaji Amines generated net cash from operating activities of Rs 54 crore in the half year ended September 2026, compared with Rs 22 crore in the half year ended September 2025. Cash generated from operations was Rs 80 crore versus Rs 38 crore, although changes in working capital absorbed Rs 143 crore, compared with Rs 85 crore in the prior-year period.
Investing cash outflow was Rs 67 crore in the half year ended September 2026, below Rs 115 crore a year earlier, while financing cash outflow was Rs 9 crore against Rs 17 crore. Cash and cash equivalents stood at Rs 53 crore on September 30, 2026, compared with an opening balance of Rs 74 crore in the cash-flow statement.
Property, plant and equipment was Rs 1,160 crore at September 2026, up from Rs 1,035 crore at March 2026, while capital work-in-progress was Rs 513 crore versus Rs 512 crore. Non-current borrowings increased to Rs 129 crore from Rs 65 crore, current borrowings declined to Rs 32 crore from Rs 68 crore, and total equity rose to Rs 2,262 crore from Rs 2,152 crore.
What expansion milestones has Balaji Amines disclosed?
Balaji Amines said commercial production has commenced at its upgraded acetonitrile facility. Management also said it is building a customer network following approval for dimethyl ether road-tanker valves, and identified N-Methyl Morpholine as its next product for commercialisation.
Management said the BSCI Unit-I brownfield expansion remains on track for commissioning by the end of FY27. It also said the BSCI Unit-II project is targeted for Q4 FY27; the presentation identifies HCN, NaCN and EDTA as part of that project but does not disclose capacity, capital cost or expected revenue contribution.
Management said raw-material availability and delayed supply chains dented volumes during Q2 FY27, although standalone volumes improved 11% over Q1 FY27. The presentation describes the portfolio as stable but does not quantify the volume impact by product or customer segment.
Conclusion
Balaji Amines’ H1 FY27 figures show earnings outpacing sales growth: consolidated revenue rose 30% to Rs 933 crore, EBITDA increased 73% to Rs 227 crore and PAT rose 97% to Rs 146 crore. The resulting 24% EBITDA margin and 16% PAT margin were both 6 percentage points above H1 FY26 levels.
The next disclosed milestones are the BSCI Unit-II project target for Q4 FY27 and BSCI Unit-I brownfield commissioning by the end of FY27. Readers can also watch whether the Q2 FY27 EBITDA margin of 22%, below Q1 FY27’s 26%, changes as the cited raw-material availability and supply-chain issues develop.