










Bandhan Bank Q2 FY27 Results: Key Numbers to Watch
Key highlights
- Bandhan Bank will consider unaudited Q2 FY27 and first-half results on October 28, 2026, followed by an earnings call.
- Loans and advances rose 13.1% year-on-year to ₹1,58,335 crore as of September 30, 2026, while deposits increased 9.2% to ₹1,72,689 crore.
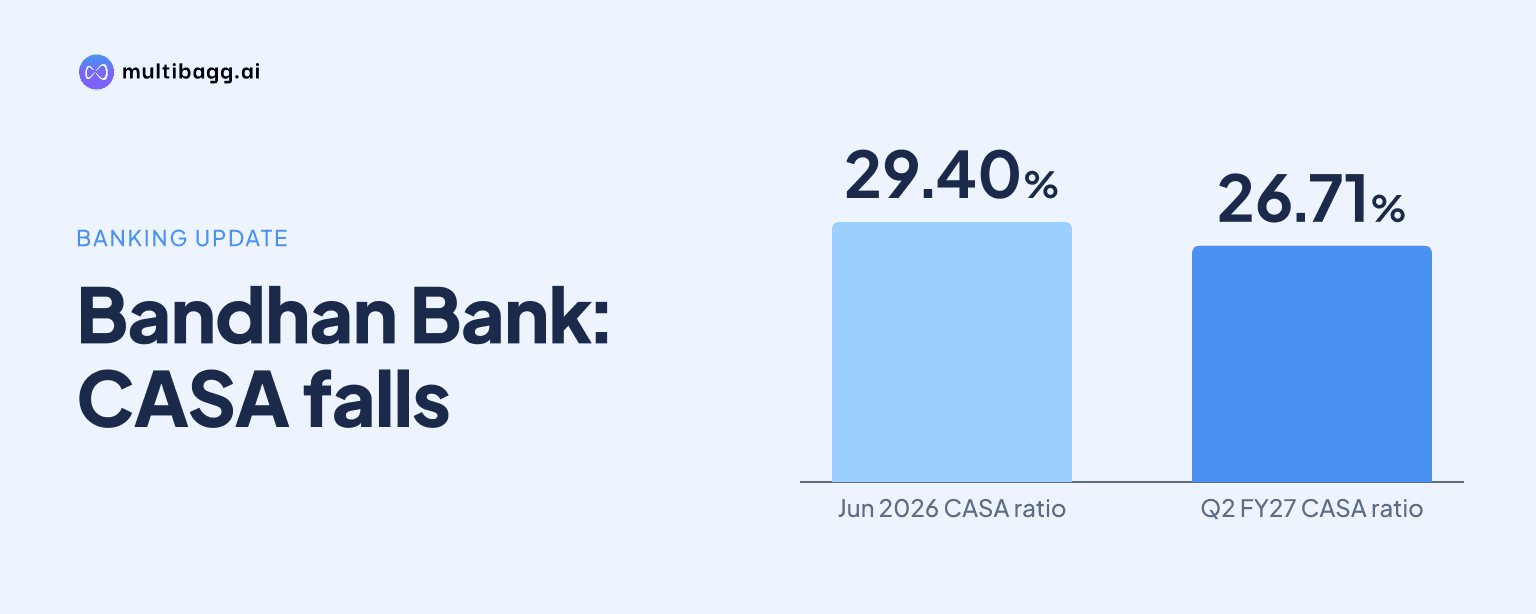
- CASA deposits fell 4.8% sequentially to ₹46,131 crore, reducing the CASA ratio to 26.71% from 29.40% in June 2026.
- Management retained FY27 credit-growth guidance of around 14% but lowered exit return-on-assets guidance to 1.2%-1.4% from 1.6%-1.8%.
powered by IRIS
Bandhan Bank is scheduled to consider and approve its unaudited financial results for the second quarter and first half of FY27 on October 28, 2026. The results will cover the quarter ended September 30, 2026. The lender has also planned an earnings call with analysts and investors on the same date. Investors will assess whether loan growth, funding costs and asset-quality trends remain aligned with management’s guidance.
Know Bandhan Bank inside out
Results, valuation, peers and who's buying, in one view.
Board meeting scheduled for October 28
Bandhan Bank informed exchanges that its board of directors would meet in Kolkata on October 28 to consider the Q2 FY27 and half-year financial statements. The board-meeting intimation was filed with BSE on October 15, 2026. The bank also stated that the results would be unaudited. Its trading window for insiders was closed from October 1 until 48 hours after the results announcement.
The scheduled announcement is important because it will provide the first full financial update after the bank released provisional business figures for the September quarter. Those operating figures showed continued expansion in loans and deposits, while the CASA mix weakened sequentially. The earnings call is expected to offer management’s explanation of these moving parts.
Loans and advances rise 13.1% year-on-year
Bandhan Bank’s loans and advances stood at ₹1,58,335 crore as of September 30, 2026, according to its provisional quarterly business update. This represented growth of 13.1% from a year earlier and 1.8% from the June 2026 quarter. The reported annual growth was broadly near management’s FY27 credit-growth guidance of around 14%.
The Q2 results will show how this balance-sheet expansion translated into interest income, margins and profitability. It will also provide more detail on the composition of lending growth. The bank’s Emerging Entrepreneurs Business, previously called the microfinance portfolio, remains a closely watched segment because management had cited lower slippages there while discussing improved asset quality in the June quarter.
Deposits grow, but CASA deposits decline
Total deposits rose 9.2% year-on-year and 4.7% quarter-on-quarter to ₹1,72,689 crore at the end of September. Deposit growth remains relevant for the bank because management has pointed to intense competition for deposits and higher funding costs as factors affecting profitability.
CASA deposits, comprising current and savings accounts, declined 4.8% from the June quarter to ₹46,131 crore. As a result, the CASA ratio fell to 26.71% from 29.40% at the end of June 2026. A lower CASA ratio can affect funding mix because CASA deposits are generally an important source of lower-cost deposits for banks.
June-quarter profitability provides the latest benchmark
In Q1 FY27, Bandhan Bank reported net profit of ₹501.7 crore, up 34.8% from ₹372 crore in the corresponding quarter of the previous year. Net interest income rose 5.9% year-on-year to ₹2,921 crore from ₹2,757 crore. Net interest margin was stable at 6.2%.
The Q1 performance followed Q4 FY26, when net interest income was ₹2,795 crore, up 1.4% year-on-year and 4.0% sequentially. Net profit for Q4 FY26 was ₹534 crore, representing year-on-year growth of 67.9%. These figures provide the immediate base for evaluating the September-quarter result.
Zee Business estimates point to higher profit
Zee Business estimates indicated that Bandhan Bank’s Q2 FY27 net profit could rise 385% year-on-year to ₹540 crore, compared with ₹112 crore in the year-ago quarter. The estimate projected net interest income of ₹2,930 crore, up 13% from ₹2,589 crore a year earlier.
The estimates also indicated a marginal 0.09 percentage-point decline in margin. Estimated provisions were ₹680 crore, lower than ₹1,150 crore in the comparable reference cited in the estimates. These are external estimates and not financial results reported by the bank, so the final outcome may differ.
Got a follow-up? Ask IRIS
Asset quality remains a central metric
Bandhan Bank said asset quality improved in the June quarter, aided by lower slippages in the Emerging Entrepreneurs Business. For Q2 FY27, Zee Business estimated that the gross non-performing asset ratio could improve to 3.0% from 3.3% in the preceding quarter. The net non-performing asset ratio was estimated to remain unchanged sequentially at 0.9%.
The final results will clarify the level of fresh slippages, recoveries, upgrades and provisioning during the September quarter. These data points are important because the bank has retained FY27 credit-cost guidance of 1.6% to 1.8%. Credit costs represent the impact of provisions and credit losses on earnings.
Management has retained credit-growth guidance
Management retained its FY27 credit-growth guidance at around 14%. The September-quarter loan-growth figure of 13.1% year-on-year places the bank close to that stated target, although full-year performance will depend on lending trends in the second half.
At the same time, the bank lowered its FY27 exit return on assets guidance to 1.2% to 1.4%, from an earlier target range of 1.6% to 1.8%. Management attributed the revision to higher funding costs, competition for deposits, a challenging operating environment and elevated operating expenses. The revised profitability target makes margin trends, deposit composition and cost control key areas for investors to monitor.
Key reported figures and estimates
What the market will assess
The principal issue for investors is whether the bank can preserve earnings momentum while managing the pressure on its deposit mix. Loan growth has remained healthy, but the quarterly fall in CASA deposits and the decline in the CASA ratio highlight the funding challenge identified by management. The reported result and earnings-call commentary will provide clearer information on the impact of funding costs on margins.
Investors will also compare actual credit costs and asset-quality indicators with guidance and external estimates. Performance in the Emerging Entrepreneurs Business will remain relevant given the bank’s comments on lower slippages in the June quarter. Any update on operating expenses and the revised return-on-assets objective will add context to the bank’s FY27 profitability outlook.
Conclusion
Bandhan Bank’s October 28 board meeting is scheduled to approve the unaudited Q2 FY27 and first-half FY27 results. The reported numbers will be assessed against the bank’s loan-growth target, credit-cost guidance and revised return-on-assets outlook. The same-day earnings call is expected to provide management commentary on deposits, margins, asset quality and the second-half operating environment.