










BEML auditor says Rs 81.13 crore recovery timing uncertain
Key highlights
- BEML’s standalone review cited Rs 81.13 crore of MAMC-related amounts at September 30, 2026.
- The amount includes a Rs 74.89 crore MAMC Consortium outlay and a Rs 6.24 crore advance to MAMC Industries Ltd.
- The reviewer said asset-realisation value and timing were not ascertainable on November 5, 2026.
- BEML reported standalone total assets of Rs 7,201.06 crore at September 30, 2026.
powered by IRIS
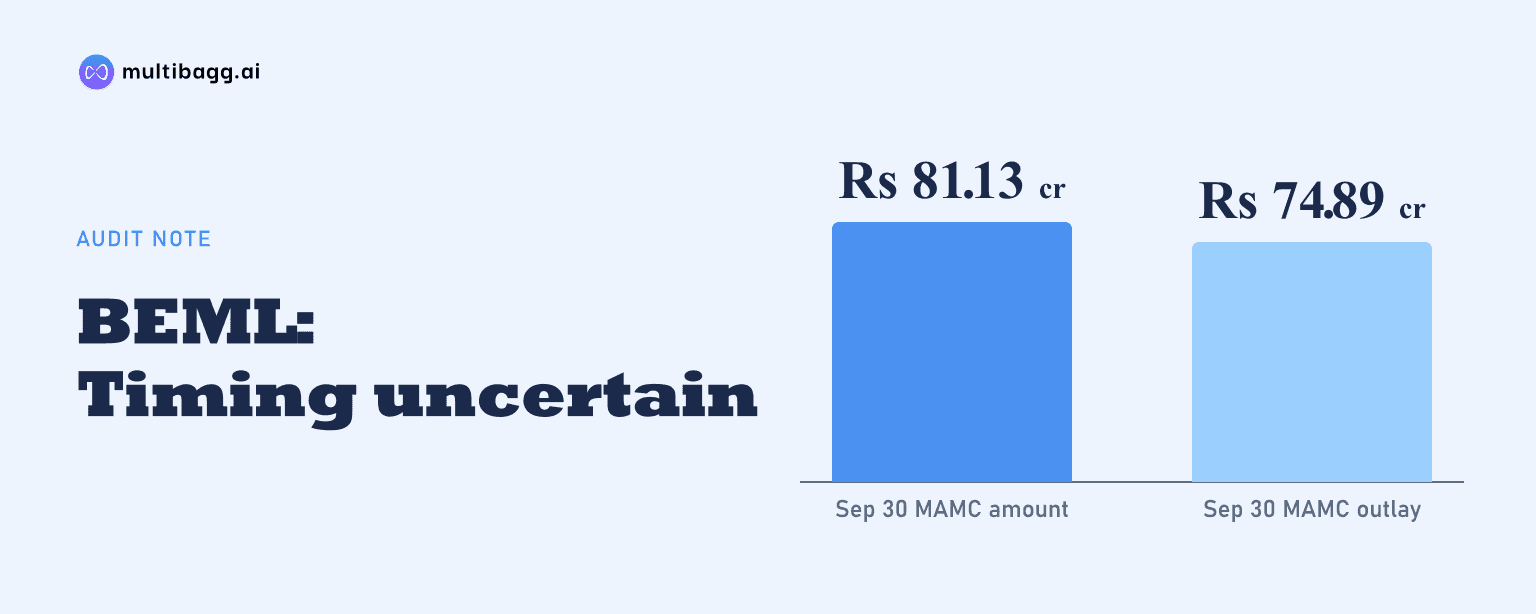
BEML Limited’s reviewer said on November 5, 2026 that recovery of Rs 81.13 crore of MAMC-related standalone amounts depends on asset realisations whose value and timing are presently not ascertainable. The amount comprises a Rs 74.89 crore MAMC Consortium outlay and a Rs 6.24 crore advance to MAMC Industries Ltd.
Know BEML inside out
Results, valuation, peers and who's buying, in one view.
What did BEML’s reviewer flag in the September 2026 results?
BEML’s reviewer drew attention to uncertainty around the recoverability of amounts tied to Mining & Allied Machinery Corporation Ltd., or MAMC, which is under liquidation. The standalone limited-review report for the quarter and six months ended September 30, 2026 identifies Rs 74.89 crore spent through the MAMC Consortium and a related Rs 6.24 crore advance to MAMC Industries Ltd.
Recovery depends on the sale or realisation of assets acquired from MAMC, according to the November 5, 2026 report. Vaithisvaran & Co LLP said the value and timing of those realisations were not ascertainable, so the filing provides neither an expected recovery date nor an estimated amount from asset sales.
Management has considered the MAMC-related amounts recoverable based on factors set out in Note No. 5 to the financial statements. The reviewer’s conclusion was not modified in respect of the matter, while the report said nothing had come to its attention to suggest the standalone results for the six months ended September 30, 2026 contained a material misstatement.
How is BEML’s Rs 81.13 crore MAMC exposure composed?
BEML’s Rs 81.13 crore standalone amount consists of the Rs 74.89 crore MAMC Consortium outlay plus the Rs 6.24 crore advance to MAMC Industries Ltd. Both components appear in the standalone emphasis-of-matter paragraph, which links their recoverability to assets acquired from MAMC.
The consolidated review cites only the Rs 74.89 crore MAMC Consortium outlay. It repeats that recoverability depends on asset sale or realisation values and timing, but does not separately mention the Rs 6.24 crore advance that appears in the standalone review.
The Rs 6.24 crore difference reflects the related advance cited in the standalone wording but not separately cited in the consolidated emphasis-of-matter paragraph. The supplied filing does not state that either amount had been written off, repaid or realised as of September 30, 2026.
How does the MAMC amount compare with BEML’s financial position?
BEML reported standalone total assets of Rs 7,201.06 crore at September 30, 2026, compared with Rs 5,904.66 crore at September 30, 2025. The Rs 81.13 crore MAMC-related amount is a specifically identified recovery matter within that reported asset base, although the filing does not disclose its exact balance-sheet classification.
Standalone current assets rose to Rs 5,746.53 crore at September 30, 2026 from Rs 4,927.29 crore a year earlier. Within current assets, trade receivables increased to Rs 1,938.20 crore from Rs 1,439.16 crore, but the review report does not connect that movement to the MAMC Consortium outlay or the MAMC Industries advance.
BEML’s consolidated total assets were Rs 7,226.14 crore at September 30, 2026, up from Rs 5,935.49 crore a year earlier. The consolidated report says the two subsidiaries’ interim information included total assets of Rs 33.8985 crore, revenue of Rs 87.79 lakh and profit of Rs 65.76 lakh for the period ended September 30, 2026.
Got a follow-up? Ask IRIS
What do BEML’s September 2026 results show alongside the review matter?
BEML reported standalone profit before tax of Rs 13.33 crore for the six months ended September 30, 2026, compared with a loss before tax of Rs 20.01 crore in the corresponding 2025 period. The emphasis-of-matter paragraph does not identify a provision, impairment, gain, loss or cash recovery from the MAMC-related amounts in that six-month result.
Standalone revenue from operations was Rs 2,011.23 crore for the half year ended September 30, 2026, while the quarter ended September 30, 2026 generated Rs 1,191.61 crore. The financial-results extract reports these figures, but does not state that revenue performance changes the value or timing of asset realisations tied to MAMC.
Standalone net cash flow from operating activities was Rs 257.02 crore for the half year ended September 30, 2026, compared with net cash used in operating activities of Rs 235.45 crore in the year-earlier half. That period-on-period reversal does not settle the MAMC question because the reviewer identified future asset realisations, rather than operating cash flow, as the recovery mechanism.
What does BEML’s limited-review conclusion mean?
BEML received a limited-review conclusion rather than an audit opinion for the September 30, 2026 results. Under Standard on Review Engagements 2410, or SRE 2410, the reviewer said procedures principally involve inquiries and analytical work and are substantially narrower than an audit under the Standards on Auditing.
The standalone reviewer said nothing had come to its attention indicating that BEML’s results had failed to disclose required information or contained a material misstatement. The consolidated reviewer reached the same conclusion and said its conclusion was not modified in respect of the Rs 74.89 crore MAMC Consortium matter.
The consolidated review also relied on reports furnished by other auditors for two subsidiaries, MAMC Industries Ltd. and Vignyan Industries Ltd., which is under liquidation. Those subsidiaries’ interim information showed Rs 33.8985 crore of total assets at September 30, 2026, but the review wording does not provide a separate recovery timetable for MAMC-related assets.
Conclusion
The September 2026 review places Rs 81.13 crore of BEML’s standalone MAMC-related amounts under explicit recovery uncertainty. Management has considered the Rs 74.89 crore consortium outlay and Rs 6.24 crore advance recoverable, but the reviewer says the value and timing of the asset sales or realisations needed for recovery cannot presently be ascertained.
The next point to watch is any BEML disclosure on the sale or realisation of assets acquired from MAMC, because the November 5, 2026 review identifies that process as the recovery mechanism. The filing sets out no sale timetable, expected realisation value, provision or write-off decision, leaving those matters unresolved.