










BirlaNu India EBITDA triples and Q2 margin reaches 6.8%
Key highlights
- BirlaNu's India revenue rose 17.3% year on year to Rs 588 crore in Q2 FY27.
- India EBITDA increased 3.3 times to Rs 40 crore, and EBITDA margin reached 6.8%.
- Roofs revenue grew 28% to Rs 244 crore, with EBITDA margin rising to 11.5% from 8.3%.
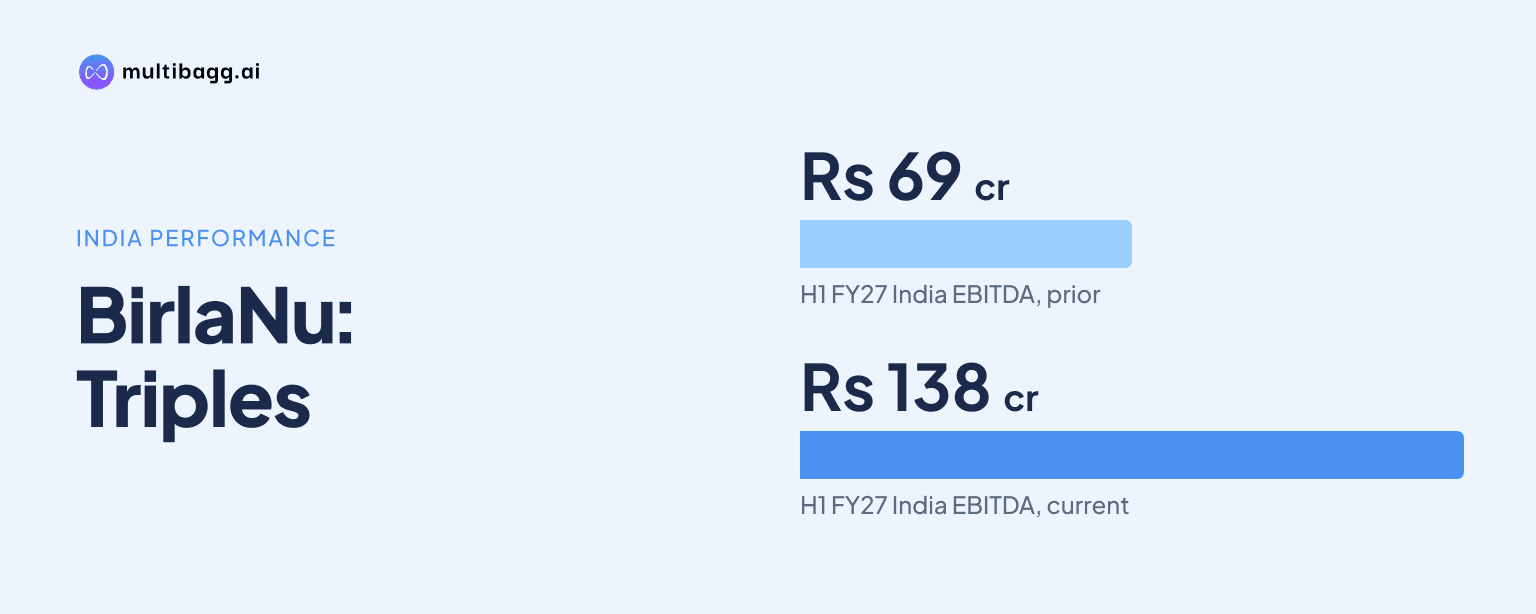
- H1 FY27 India EBITDA doubled to Rs 138 crore from Rs 69 crore, with margin at approximately 10%.
powered by IRIS
In Q2 FY27, BirlaNu Limited's India business lifted EBITDA 3.3 times year on year to Rs 40 crore and margin to 6.8%, as revenue rose 17.3% to Rs 588 crore. The fifth consecutive quarter of margin expansion reflected higher-value mix, operating leverage, better realisations and cost management, management said.
Know BirlaNu inside out
Results, valuation, peers and who's buying, in one view.
How did BirlaNu's India profitability change in Q2 FY27?
BirlaNu's India EBITDA increased from Rs 12 crore in Q2 FY26 to Rs 40 crore in Q2 FY27, while EBITDA margin expanded by more than 400 basis points to 6.8%. EBITDA, or earnings before interest, tax, depreciation and amortisation, rose faster than revenue, which increased 17.3% year on year to Rs 588 crore. Management said the India business includes BirlaNu's standalone operations and Clean Coats.
The quarter marked BirlaNu's fifth consecutive period of EBITDA-margin expansion. Management linked the progress to portfolio changes, including a greater share of higher-value offerings, sharper sales and operating execution, and brand investments. The improvement occurred while the company reported inflation in raw materials, energy, freight and currency.
Which businesses drove BirlaNu's Q2 margin expansion?
Roofs was the largest of the three India segments for which BirlaNu disclosed Q2 revenue, and it combined volume growth with margin improvement. Revenue rose 28% year on year to Rs 244 crore, volumes grew 21%, and the share of value-added products was 35% higher than a year earlier. Its EBITDA margin increased 320 basis points to 11.5% from 8.3%, supported by operating leverage and cost management.
Walls delivered slower revenue growth but a higher reported segment margin. Revenue increased 5.4% to Rs 164 crore, while EBITDA margin rose 120 basis points year on year to 12.3%. Management attributed the increase to better realisations, an improved mix and tighter cost management, alongside a wider retail presence beyond the segment's traditional institutional channels.
Pipes recovered after a challenging first quarter for the industry, when volatile resin prices led to degrowth. Q2 revenue rose 20% year on year to Rs 132 crore, while EBITDA margin improved 630 basis points from the corresponding quarter. Value-added products, including fittings, accounted for 47% of the Pipes portfolio, and management also cited focused market development and manufacturing as a service as margin-supporting measures.
What does BirlaNu's first-half performance show?
BirlaNu's India business reported H1 FY27 revenue of Rs 1,422 crore, up 13.8% year on year, while EBITDA doubled to Rs 138 crore from Rs 69 crore. Its H1 EBITDA margin was approximately 10%, more than 400 basis points above the corresponding prior-year period. The H1 margin exceeded the Q2 margin of 6.8%, although the call did not disclose the Q1 India margin or H1 segment-level figures.
The half-year result showed that the Q2 improvement extended the operating progress reported earlier in FY27. Management identified higher-value mix as a common factor across businesses: Roofs increased value-added sales, Pipes raised the share of value-added products including fittings to 47%, and Walls improved realisations and mix. Construction Chemicals grew about 35% despite raw-material cost and pricing pressure, while Clean Coats revenue increased about 50% from the same period a year earlier.
Got a follow-up? Ask IRIS
Why did consolidated profitability lag BirlaNu's India business?
BirlaNu's consolidated revenue increased 9.2% year on year to Rs 885 crore in Q2 FY27, compared with 17.3% growth in the India business, as Parador faced weak demand in key European markets. Parador revenue declined about 4.4% year on year in rupee terms, or 11% in local-currency terms, and lower volumes and cost pressures affected profitability. Management said this performance weighed on consolidated profitability despite India's margin expansion.
For H1 FY27, consolidated revenue reached Rs 2,059 crore, up 11% year on year, and consolidated EBITDA rose about 30% to Rs 82 crore from Rs 63 crore. That contrasted with India EBITDA doubling to Rs 138 crore over the same six months. BirlaNu has engaged BCG on a cost restructuring programme for Parador, and management said the work had identified an additional EBITDA value envelope of about EUR 9 million to EUR 14 million.
BirlaNu also recognised an additional Rs 90 crore provision for diminution in the value of its investment in BirlaNu International GmbH, taking cumulative provisions to Rs 164 crore as of September 30, 2026. Management said the assessment reflected prolonged weakness in European markets, geopolitical uncertainty and Parador's operating performance. The carrying value will be reassessed regularly based on Parador's financial performance.
What could sustain BirlaNu's India margin progress?
BirlaNu expects its Roofs value-enhancement programme to provide further support to profitability, with the full annual benefit expected from next year. Management said the programme was already generating savings through cost actions and was intended to make the segment's gains more structural. Roofs reported Q2 FY27 revenue of Rs 244 crore and an 11.5% EBITDA margin.
Capacity additions and new products form another part of management's FY27 plan. The greenfield Boards plant at Nellore is on track to begin commercial production in Q4 FY27, while BirlaNu expects to break ground on a second project in Hyderabad by December. In Q2, it launched Eco Roofs, QuikSeal and Poly Tech Waterproofing 2K across Roofs and Construction Chemicals, with further product launches planned for the second half.
BirlaNu also commissioned rooftop solar at its Golan and Chennai units during the quarter and approved solar capacity at two more manufacturing units. Management expects green power to exceed 20% to 25% of the energy mix within two years, which it said should reduce energy costs and carbon emissions. It nevertheless cited raw-material inflation, global supply disruption, tight liquidity and potential El Nino-related pressure on rural demand as risks.
Conclusion
BirlaNu's Q2 FY27 India result showed EBITDA rising faster than revenue, with EBITDA increasing 3.3 times to Rs 40 crore on revenue of Rs 588 crore and margin reaching 6.8%. Roofs, Walls and Pipes each reported margin progress through combinations of value-added mix, realisations, operating leverage and cost measures, while Parador's European demand and cost pressures constrained consolidated profitability.
The next disclosed milestones are the planned Q4 FY27 commercial start at the Nellore Boards plant, the expected Hyderabad project groundbreaking by December, and further second-half product launches. Management also expects the Roofs value-enhancement programme to deliver its full annual benefit from next year, while Parador's BCG-led cost restructuring and its regular investment-value reassessment remain unresolved items to watch.