










BirlaNu books Rs 90 crore Parador provision, targets positive H2
Key highlights
- BirlaNu recorded an additional Rs 90 crore Parador provision, taking cumulative provisions to Rs 164 crore as of September 30, 2026.
- Parador revenue declined 11% in local currency and 4% in Indian-rupee terms during the quarter ended September 30, 2026.
- BCG identified a €9 million to €14 million EBITDA value envelope from Parador cost restructuring.
- BirlaNu’s India-business EBITDA doubled to Rs 138 crore in H1 FY27 from Rs 69 crore a year earlier.
powered by IRIS
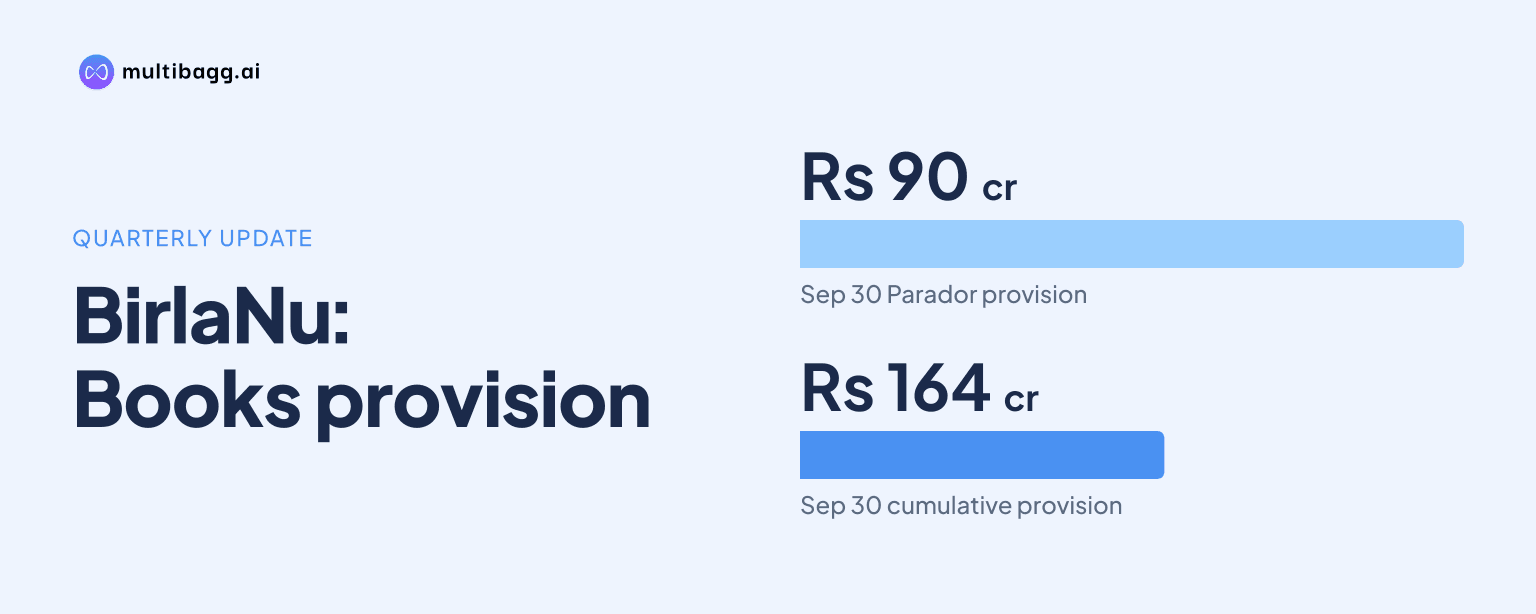
BirlaNu recorded an additional Rs 90 crore provision on its Parador investment for H1 FY27 ended September 30, 2026, lifting cumulative provisions to Rs 164 crore as Parador revenue fell 11% in local currency. Management now says its first milestone is to make the remaining H2 FY27 positive rather than reiterating full-year breakeven.
Know BirlaNu inside out
Results, valuation, peers and who's buying, in one view.
Why did BirlaNu record another Parador provision?
BirlaNu recorded the Rs 90 crore provision because Parador continued to incur operating losses amid weak demand in key European markets and elevated raw-material prices. The charge relates to diminution in the value of BirlaNu’s investment in BirlaNu International GmbH and was recognised as an exceptional item in the standalone financial statements. Cumulative provisions on the investment stood at Rs 164 crore as of September 30, 2026.
Parador’s revenue declined 11% in local-currency terms and 4% in Indian-rupee terms during the quarter ended September 30, 2026. Management said the combination of lower demand across its key European markets and cost pressure reduced profitability. BirlaNu said it would reassess the carrying value of its investment regularly, based on Parador’s financial performance.
The provision is separate from the company’s operating response to Parador’s losses. While the Rs 90 crore exceptional item reduces the stated value of BirlaNu’s investment, the restructuring programme is intended to lower Parador’s underlying cost base. Management did not disclose a revised carrying value or indicate whether another provision would be needed after the September 30 assessment.
What is BirlaNu’s BCG cost-restructuring plan for Parador?
BirlaNu said Boston Consulting Group, or BCG, identified an additional value envelope of €9 million to €14 million at Parador’s earnings before interest, tax, depreciation and amortisation, or EBITDA, line. Management described the exercise as a comprehensive cost restructuring across possible cost items, rather than a programme limited to procurement, manufacturing or any one business function.
The BCG engagement was in its third month when management spoke to investors, and the diagnostic and opportunity-identification stages had been completed. Management said the design phase was nearing completion and implementation had begun in parallel. The engagement will continue until the end of FY27 to support implementation, while initial evidence of how much of the €9 million to €14 million envelope translates on the ground should emerge within three to four months.
The plan is aimed at an operating improvement, not a guaranteed result. Management said the first ideas were already being implemented, but did not quantify savings already secured or set a quarterly EBITDA savings target. The eventual effect will depend on execution of the identified actions and on Parador’s market conditions during the remainder of FY27.
Can Parador become positive in H2 FY27?
BirlaNu did not reaffirm a full-year FY27 EBITDA-positive objective for Parador and instead set H2 FY27 positivity as its first milestone. Management said any H2 surplus would then be assessed against the losses already incurred in H1 FY27. It added that the outcome remains contingent on demand improving in Parador’s core European markets.
Management reported some positive rebound in revenue during October, after the summer months, but did not give an H2 revenue target or EBITDA forecast. An analyst referred to earlier breakeven revenue estimates and first-half performance figures, but management did not confirm those figures in its response. Its stated position was that it needed to see the effect of the restructuring and demand recovery before considering another decision or discussion on the business.
New markets are part of that recovery plan. Management said Parador had seen positive momentum in North America, the Middle East and India, and that United States revenue in the first six months was almost twice the full-year level of the preceding financial year. It said North America was on track to reach nearly four to five times the prior year’s performance in FY27, without providing an absolute revenue value.
Got a follow-up? Ask IRIS
How did BirlaNu’s India business compare with Parador?
BirlaNu’s India business performed better than Parador in both revenue growth and profitability during H1 FY27. India business, defined by management as BirlaNu standalone plus Clean Coats, reported revenue of Rs 1,422 crore, up 13.8% year on year, while EBITDA doubled to Rs 138 crore from Rs 69 crore. Its EBITDA margin expanded by more than 400 basis points to about 10%.
At the consolidated level, BirlaNu reported H1 FY27 revenue of Rs 2,059 crore, up 11% year on year, and EBITDA of Rs 82 crore, compared with Rs 63 crore a year earlier. The Rs 56 crore difference between India-business EBITDA of Rs 138 crore and consolidated EBITDA of Rs 82 crore illustrates the effect of businesses outside the India operation, including the pressure from Parador cited by management.
The quarterly domestic trend was broad-based. Roofs revenue rose 28% year on year to Rs 244 crore, with EBITDA margin increasing to 11.5% from 8.3%; Walls revenue increased 5.4% to Rs 164 crore, with margin at 12.3%; and Pipes revenue rose 20% to Rs 132 crore. Construction Chemicals grew 35%, although management said the business faced elevated raw-material costs and pricing pressure.
What other FY27 actions could affect BirlaNu’s results?
BirlaNu said the Nellore Boards plant is expected to begin operations in Q4 FY27, while the Nellore and Hyderabad projects remain on track within their planned investment outlay. Management expects the Nellore plant to support Walls revenue growth and profitability. Clean Coats integration is expected to be completed by the end of the year, subject to statutory approvals, with management expecting operational and procurement synergies.
Total debt stood at Rs 896 crore on September 30, 2026, compared with Rs 852 crore on March 31, 2026. Management attributed the Rs 44 crore increase to greenfield projects and other capacity expansions. It said working capital had improved against both the previous year and the corresponding earlier period, but did not provide a working-capital balance or debt-reduction timetable.
The company also commissioned rooftop solar at Golan and Chennai during the quarter and approved solar capacity at two additional manufacturing sites. Management expects green power to exceed 20% to 25% of the energy mix within two years. It estimated annual savings of Rs 4 crore to Rs 5 crore from projects across the existing footprint, with implementation across locations expected over six to nine months.
Conclusion
BirlaNu’s additional Rs 90 crore Parador provision makes the European subsidiary the principal constraint on its H1 FY27 results, even as India-business EBITDA doubled to Rs 138 crore. The company’s response combines a €9 million to €14 million BCG-led cost-restructuring opportunity with expansion in North America, the Middle East and India, but neither initiative yet establishes a full-year turnaround outcome.
The next disclosed milestones are the expected visibility on BCG implementation within three to four months, the effort to make Parador positive in H2 FY27, and restructuring support through the end of FY27. Investors can also watch for the expected Q4 FY27 Nellore Boards commissioning, Clean Coats integration by the end of the year subject to approvals, and the rollout of solar projects over six to nine months.