










BirlaNu EBITDA triples, ₹90 crore provision drives loss
Key highlights
- BirlaNu’s Q2 FY27 standalone EBITDA rose 226% to ₹39 crore from ₹12 crore.
- A ₹90 crore provision on BirlaNu International GmbH resulted in a ₹84 crore Q2 FY27 standalone PAT loss.
- BirlaNu’s H1 FY27 standalone EBITDA rose 97% to ₹137 crore on revenue of ₹1,405 crore.
- Floors Q2 FY27 PBT loss widened to ₹58 crore from ₹29 crore as revenue fell 4% to ₹297 crore.
powered by IRIS
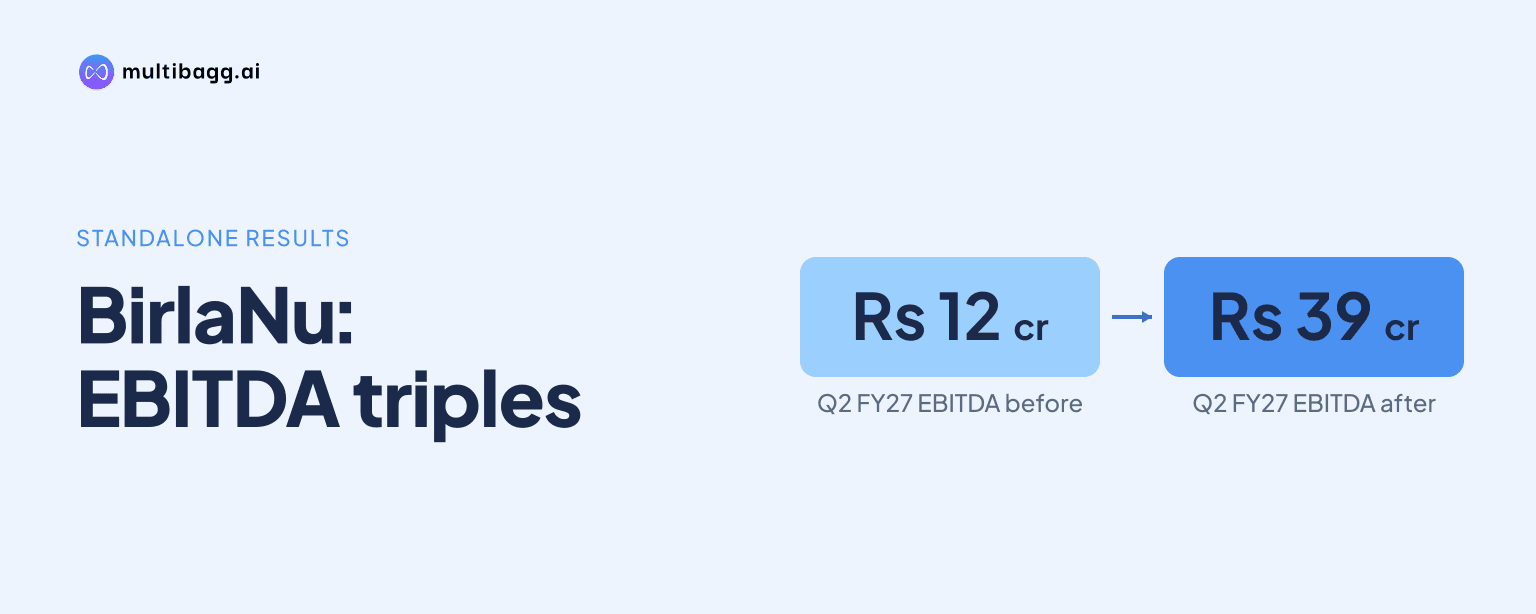
BirlaNu reported Q2 FY27 standalone earnings before interest, tax, depreciation and amortisation (EBITDA) of ₹39 crore, up 226% year on year, but a ₹90 crore provision for diminution in its BirlaNu International GmbH investment resulted in a ₹84 crore profit after tax (PAT) loss. The figures separate improved operating performance from an exceptional investment-value charge.
Know BirlaNu inside out
Results, valuation, peers and who's buying, in one view.
Why did BirlaNu report a Q2 FY27 standalone loss?
BirlaNu reported a Q2 FY27 standalone loss because it recognised a ₹90 crore exceptional provision towards diminution in the value of its investment in subsidiary BirlaNu International GmbH. The provision took reported profit before tax (PBT) to a loss of ₹82 crore, compared with PBT of ₹8 crore before the exceptional item. Reported PAT was a ₹84 crore loss, against a ₹12 crore loss in Q2 FY26.
The charge contrasted with the movement in operating and pre-exceptional profitability. Standalone PBT excluding the exceptional item moved from a ₹17 crore loss in Q2 FY26 to an ₹8 crore profit in Q2 FY27, a ₹25 crore improvement. The presentation identifies the ₹90 crore item as a provision on investment value, rather than as an operating cost of the quarterly businesses.
How did BirlaNu’s standalone operations perform in Q2 FY27?
BirlaNu’s standalone operations improved in Q2 FY27, with revenue rising 16% to ₹581 crore and EBITDA increasing 226% to ₹39 crore. Revenue was ₹502 crore and EBITDA was ₹12 crore in Q2 FY26, meaning EBITDA was more than three times the prior-year level while revenue increased by ₹79 crore.
Management said its India business posted a third consecutive quarter of double-digit revenue growth and margins improved by more than 400 basis points across most categories despite cost pressure. It separately reported India-business revenue of ₹588.4 crore, up 17.3%, and EBITDA of about ₹40 crore. The presentation does not reconcile those measures with the ₹581 crore standalone revenue and ₹39 crore EBITDA figures.
The reported PAT movement did not follow the direction of revenue, EBITDA or PBT before exceptional items. EBITDA rose by ₹27 crore and pre-exceptional PBT improved by ₹25 crore, while PAT moved ₹72 crore further into loss. The ₹90 crore provision exceeded the quarter’s ₹8 crore PBT before exceptional items, producing the reported loss.
Which segments drove BirlaNu’s India portfolio growth?
BirlaNu’s Roofs segment recorded the largest reported revenue increase among the India portfolio segments, with Q2 FY27 revenue rising ₹53 crore to ₹244 crore. Its PBT increased ₹10 crore to ₹23 crore from ₹13 crore, while management described revenue growth as 28.2% and said margins improved.
Walls delivered a smaller revenue increase but higher PBT. Revenue rose 5% to ₹164 crore from ₹155 crore, while PBT increased 23% to ₹13 crore from ₹10 crore. Management described Walls as recording a marked profitability step-up, and the segment table shows a ₹3 crore year-on-year PBT increase.
Pipes and Construction Chemicals together grew revenue 16% to ₹179 crore from ₹155 crore and narrowed their PBT loss to ₹5 crore from ₹13 crore. Management said Pipes grew 19.7% year on year and 19.4% quarter on quarter, with margins improving by 630 basis points from the prior year. It said Construction Chemicals grew 35.3% despite cost and pricing pressure linked to the geopolitical situation.
The positive India trends contrasted with Floors. Floors revenue declined 4% to ₹297 crore from ₹309 crore, while its PBT loss widened to ₹58 crore from ₹29 crore. Management said Parador revenue declined 4.4% because of weak demand in key European markets and global sluggishness, alongside profitability pressure from costs.
Got a follow-up? Ask IRIS
How did BirlaNu’s H1 FY27 standalone results compare?
BirlaNu’s H1 FY27 standalone revenue rose 12% to ₹1,405 crore and EBITDA increased 97% to ₹137 crore. In H1 FY26, revenue was ₹1,251 crore and EBITDA was ₹69 crore. The half-year EBITDA increase was ₹68 crore, while revenue increased by ₹154 crore.
PBT excluding exceptional items rose to ₹76 crore in H1 FY27 from ₹10 crore a year earlier, which the presentation reports as 669% growth. The same ₹90 crore provision towards diminution in the BirlaNu International GmbH investment was recognised in H1 FY27. Reported H1 PBT was therefore a ₹14 crore loss and PAT was a ₹34 crore loss, compared with a ₹7 crore PAT profit in H1 FY26.
The gap between ₹76 crore of H1 PBT before exceptional items and a ₹14 crore reported PBT loss quantifies the provision’s effect on reported earnings. The presentation presents the provision once in the H1 FY27 results, rather than describing an additional ₹90 crore charge for each quarter.
Why did BirlaNu’s consolidated earnings lag standalone operations?
BirlaNu’s consolidated Q2 FY27 EBITDA fell 59% to ₹2 crore, even as standalone EBITDA rose to ₹39 crore. Consolidated revenue increased 9% to ₹885 crore from ₹810 crore, but consolidated PBT was a ₹54 crore loss and PAT was a ₹57 crore loss. Management said weaker Parador performance affected overall consolidated profitability.
The segment data show the contrast underlying that result. Roofs, Walls, and Pipes and Construction Chemicals reported revenue growth or better PBT trends, whereas Floors revenue fell ₹12 crore and its PBT loss widened ₹29 crore. Management said a BCG-led cost-out programme and other measures were intended to support Parador’s recovery, alongside expansion into the US, India and commercial customers and a focus on European do-it-yourself and retail channels.
For H1 FY27, consolidated revenue rose 11% to ₹2,059 crore and EBITDA increased 30% to ₹82 crore, compared with ₹1,862 crore and ₹63 crore in H1 FY26. Consolidated PBT remained a ₹28 crore loss and PAT a ₹48 crore loss. The presentation therefore shows improved India operating measures alongside continuing pressure from the European business.
Conclusion
BirlaNu’s Q2 FY27 results show a divergence between operations and reported profit: standalone EBITDA rose from ₹12 crore to ₹39 crore, and PBT before exceptional items returned to an ₹8 crore profit, but the ₹90 crore investment-value provision produced a ₹84 crore PAT loss. Consolidated earnings also remained affected by the loss-making Floors business.
The next disclosed milestones are commercial production at the Nellore greenfield board plant in Q4 FY27 and ground-breaking for the Hyderabad board plant by December 2026. Management also plans further Roofs and Construction Chemicals launches in H2 FY27, while citing raw-material, energy, freight and currency inflation, tight liquidity and potential demand pressure as risks.