










Bonfiglioli Transmissions Limited targets 20% CY26 revenue growth
Key highlights
- Bonfiglioli India’s Q3 CY2026 revenue rose 30.2% year on year to Rs 660.2 crore.
- Off-highway mobility grew 54.9% in Q3 CY2026, ahead of Industry and Automation Solutions at 30.5% and wind at 8%.
- Exports grew 40.4% in the first nine months of CY2026 and accounted for 30.6% of revenue.
- Bonfiglioli India plans capital expenditure of about Rs 100 crore in CY2026 and Rs 150 crore in CY2027.
powered by IRIS
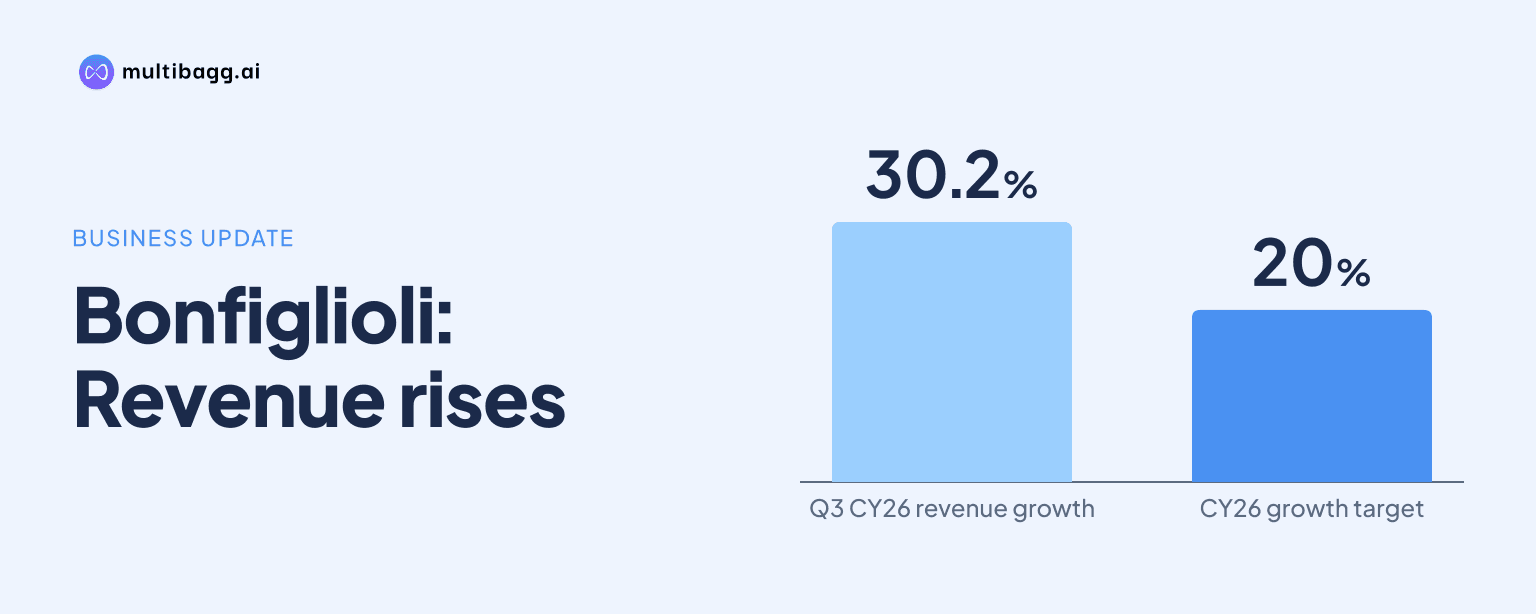
Bonfiglioli India expects about 20% revenue growth in CY26 after Q3 CY2026 revenue from operations rose 30.2% year on year to Rs 660.2 crore, with record quarterly sales in industrial automation, off-highway mobility and wind. Management said customer schedules and a high Q4 CY2025 base could moderate growth in the final quarter.
Know Bonfiglioli Transmissions inside out
Results, valuation, peers and who's buying, in one view.
Why did Bonfiglioli India report record quarterly sales?
Bonfiglioli India reported record quarterly revenue across its three divisions because domestic sales and exports both expanded in Q3 CY2026. Revenue from operations reached Rs 660.2 crore, while domestic-market revenue grew 23.8% year on year and export revenue increased 46.2%. Management said industrial automation, off-highway mobility and wind each recorded their highest quarterly revenue.
The Q3 growth rate of 30.2% exceeded the 22.8% growth reported for the first nine months of CY2026. Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 38% to Rs 128.9 crore in Q3, while profit after tax, or PAT, rose 38.2% to Rs 87.1 crore. EBITDA margin was 19.5% and PAT margin was 13.1% in the quarter.
Management attributed the profit increase to efficiencies, localisation, pricing, foreign-exchange savings, value analysis and value engineering initiatives, and inventory-lag effects. Nine-month EBITDA margin was 19.7%, 0.2 percentage points above Q3, while PAT margin remained 13.1% in both periods. The comparison indicates that revenue growth accelerated in Q3 even as the EBITDA margin was slightly below the year-to-date level.
Which businesses and markets drove Bonfiglioli India growth?
Off-highway mobility was Bonfiglioli India’s fastest-growing business in Q3 CY2026, rising 54.9% year on year, ahead of Industry and Automation Solutions at 30.5% and wind at 8%. Management said mobility benefited from programme wins secured in the prior year that began generating deliveries in CY2026.
Industry and Automation Solutions benefited from what management described as a broad recovery in Indian manufacturing. The business accounts for 42% of revenue, compared with 29.4% for off-highway mobility and 26.8% for wind. Management said it serves 22 industries, including material handling, mining, food and beverage, factory automation, biogas and wastewater, providing exposure to multiple applications rather than one sector.
Exports were another contributor across the three businesses. Export revenue grew 40.4% in the first nine months of CY2026 and represented 30.6% of total revenue for that period. Management said exports include both direct customer sales and sales to group entities, with exports to group entities at around 21% and total exports at 30.6%.
Wind trailed the other two businesses in Q3, but management cited divergent customer performance. GE, identified as the largest wind customer in 2025, recorded a 30% decline through the first nine months of CY2026, while other wind customers grew 22%. Management said this customer diversification allowed the wind business to remain in growth despite the decline at its largest 2025 customer.
Got a follow-up? Ask IRIS
Why is Bonfiglioli India retaining its 20% CY26 growth target?
Bonfiglioli India is retaining its approximately 20% CY26 revenue-growth expectation because management does not regard the record Q3 as a run rate for Q4. Management said customer delivery schedules can move between quarters and noted that Q4 CY2025 was the strongest quarter of that year, creating a higher comparison base for Q4 CY2026.
The 20% full-year expectation is below the 22.8% growth achieved in the first nine months of CY2026, implying a slower final-quarter growth rate if the target is met. Management contrasted the current year with growth below 10% in each of the preceding three years and a long-term average growth rate of about 14.5% from 2009 to 2025.
For CY2026 to CY2028, management aims for revenue compound annual growth of 15% and an EBITDA margin in the vicinity of 18.5%. It described both as goals for the period as a whole rather than quarterly or annual guidance. Management identified new-product market-share gains, mobility and wind exports, demand expansion and eventual heavy-duty gearbox sales as the main drivers.
New products are already a material source of revenue, according to management. About 35% of first-half CY2026 business came from products introduced during the preceding three years. Around half of Bonfiglioli India’s business is co-engineered, principally in mobility and wind, where product-development and validation cycles run from one to three years before integration into customer platforms.
What do margins and investment plans indicate for Bonfiglioli India?
Bonfiglioli India said its 19.7% EBITDA margin for the first nine months of CY2026 included benefits that may not recur at the same level, which is why management cited 18.5% as its CY2026-CY2028 objective. Management said price actions were reflected in sales, while commodity costs had not yet been fully reflected in material costs because inventory effects and supplier negotiations were continuing.
Foreign-exchange gains were another reason for management’s caution on margins. Exports represented 30.6% of nine-month revenue and increased 40.4%, making foreign exchange a significant part of the margin upside, management said. It also said EBITDA margin rose from 15.5% in 2023 to 18.4% in 2025 through localisation, productivity, scale efficiency, design and product-mix changes.
The company plans capital expenditure of about Rs 100 crore in CY2026 and Rs 150 crore in CY2027, with internal accruals intended to fund the programme. Management said Rs 70 crore to Rs 80 crore of the CY2026 expenditure had been invested by September 2026, mainly on capacity debottlenecking. Fixed-asset turnover was 6.05 times as of September 30, 2026, or 8.06 times on an annualised basis.
The CY2027 plan includes regular capacity spending and the start of investment in heavy-duty gearboxes in the second quarter of CY2027. Management expects heavy-duty products to contribute meaningfully after CY2028. Bonfiglioli India currently operates mainly in light- and medium-duty gearboxes below 15 kilonewton-metres in industrial automation, while the heavy-duty entry is intended to extend its product coverage.
Conclusion
Bonfiglioli India’s CY26 outlook combines broad-based Q3 revenue expansion with management’s expectation that the final quarter will face a more demanding comparison. Mobility programme deliveries led quarterly segment growth, industrial automation benefited from manufacturing recovery, and exports increased faster than domestic sales. At the same time, management’s 18.5% CY2026-CY2028 EBITDA-margin objective reflects the potential unwinding of foreign-exchange and cost-timing benefits in the 19.7% nine-month result.
The next items to watch are Q4 CY2026 customer schedules and whether full-year revenue growth reaches management’s approximately 20% expectation. Management also said heavy-duty investment is planned to begin in the second quarter of CY2027 and that meaningful revenue contribution is expected after CY2028. In wind, management said GE was expected to provide its remaining schedules within a month, which could clarify the pace of that customer’s recovery.