










Bonfiglioli Q3 revenue rises 30%, profit increases 38%
Key highlights
- Bonfiglioli Q3CY26 revenue from operations rose 30.2% year on year to ₹660.2 crore.
- Bonfiglioli Q3CY26 EBITDA excluding other income rose 38.0% to ₹128.9 crore and margin increased to 19.5% from 18.4%.
- Bonfiglioli Q3CY26 profit after tax increased 38.2% to ₹87.1 crore, with margin rising to 13.1%.
- Bonfiglioli export revenue grew 46.2% to ₹213.9 crore in Q3CY26, compared with domestic revenue growth of 23.8%.
powered by IRIS
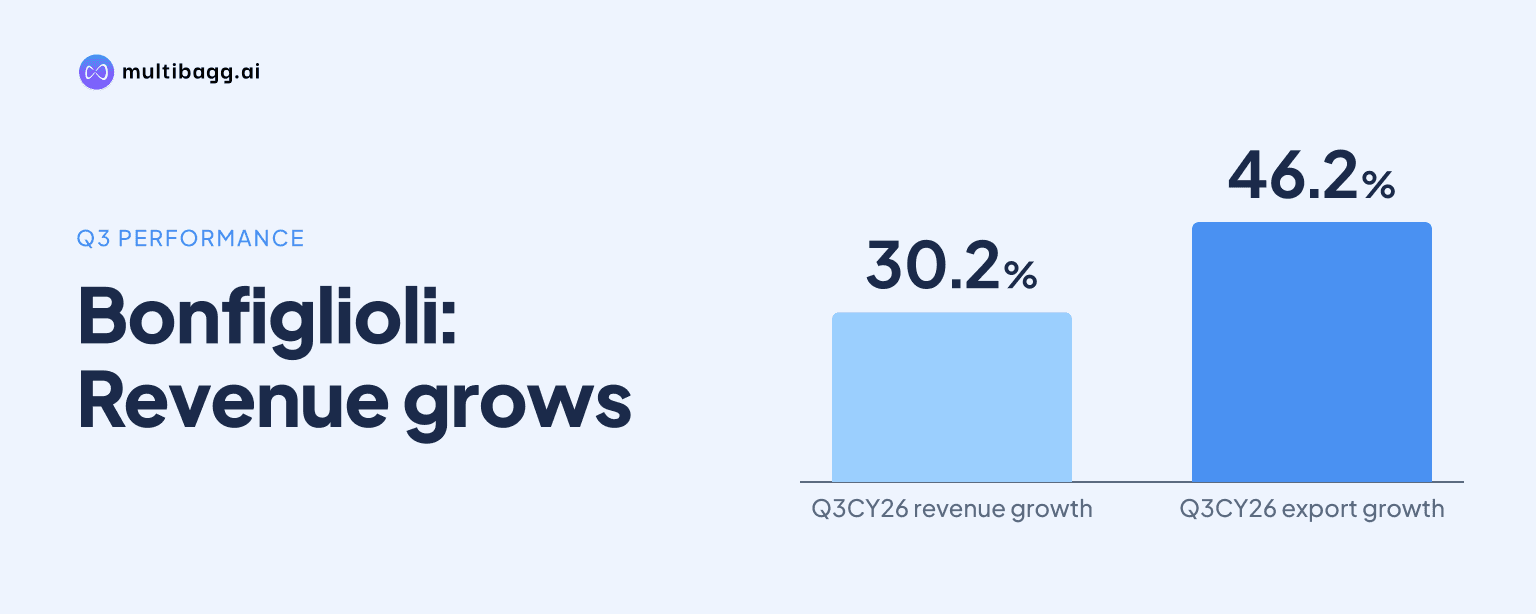
Bonfiglioli Transmissions Ltd. reported Q3CY26 revenue from operations of ₹660.2 crore, up 30.2% year on year, while profit after tax rose 38.2% to ₹87.1 crore in its first results as a listed company. EBITDA excluding other income increased 38.0% to ₹128.9 crore, lifting the margin to 19.5% from 18.4% a year earlier.
Know Bonfiglioli Transmissions inside out
Results, valuation, peers and who's buying, in one view.
What drove Bonfiglioli’s Q3CY26 revenue growth?
Bonfiglioli’s Q3CY26 revenue growth came from both domestic and export markets, with revenue from operations rising to ₹660.2 crore from ₹506.9 crore in Q3CY25. The company was officially listed on the National Stock Exchange and BSE on 23 October 2026, and management described Q3CY26 as its first results as a listed company.
Domestic revenue increased 23.8% to ₹446.3 crore from ₹360.6 crore, while export revenue rose 46.2% to ₹213.9 crore from ₹146.3 crore. Export growth was therefore faster than domestic growth, raising exports’ contribution to 32.4% from 28.9%; domestic revenue accounted for 67.6%, down from 71.1%.
Revenue also increased sequentially to ₹660.2 crore from ₹561.6 crore in Q2CY26 and ₹570.3 crore in Q1CY26. It exceeded the previous seven-quarter high of ₹546.3 crore in Q4CY25, while the reported series began at ₹470.7 crore in Q1CY25.
How did Bonfiglioli’s Q3CY26 profitability change?
Bonfiglioli expanded profitability in Q3CY26, as EBITDA excluding other income grew to ₹128.9 crore from ₹93.4 crore and the EBITDA margin rose by 1.1 percentage points to 19.5%. Earnings before interest and tax, or EBIT, increased 42.3% to ₹115.8 crore, and the EBIT margin moved to 17.5% from 16.1%.
Profit before tax from continuing operations rose 44.9% to ₹117.3 crore from ₹81.0 crore, while tax expense increased to ₹30.2 crore from ₹18.0 crore. Profit after tax reached ₹87.1 crore versus ₹63.0 crore, and its margin increased to 13.1% from 12.4%; basic and diluted earnings per share were each ₹4.63, compared with ₹3.35.
The nine-month comparison showed the same direction. Revenue in 9MCY26 rose 22.8% to ₹1,792 crore from ₹1,459.2 crore in 9MCY25, while EBITDA increased 37.2% to ₹353.4 crore and the margin rose to 19.7% from 17.6%.
Profit after tax for 9MCY26 increased 40.7% to ₹235.7 crore from ₹167.5 crore, with the margin rising to 13.1% from 11.4%. Q3CY26 EBITDA margin was marginally below the 19.7% recorded in Q2CY26 but above Q3CY25’s 18.4%; the presentation notes that Q2CY25 included ₹8 crore of one-off income related to a secondary adjustment and ₹4.3 crore from a warranty reversal.
Got a follow-up? Ask IRIS
Which Bonfiglioli segments and markets grew fastest?
Bonfiglioli’s Off-Highway Mobility Industry was the fastest-growing reported vertical in Q3CY26, with revenue increasing 54.9% to ₹205.8 crore from ₹132.9 crore. Its contribution to the disclosed vertical mix rose to 31.2% from 26.2%, compared with 41.2% for Industry & Automation Solutions and 25.7% for Wind Industry.
Industry & Automation Solutions revenue rose 30.5% to ₹271.7 crore from ₹208.1 crore, holding its revenue contribution broadly steady at 41.2% versus 41.1%. Wind Industry revenue increased 8.0% to ₹170.0 crore from ₹157.4 crore, but its contribution declined to 25.7% from 31.0%.
The disclosed vertical revenues do not add up to total revenue because the balance includes other operational revenue, including export incentives, scrap and component sales to vendors. Management cited automation initiatives, Industry 4.0 adoption, industrial and government capital expenditure, localisation and demand from global original equipment manufacturers, or OEMs, as end-market factors.
Over 9MCY26, Off-Highway Mobility revenue rose 43.0% to ₹526.2 crore from ₹367.9 crore, ahead of Industry & Automation Solutions’ 25.8% increase to ₹753.0 crore. Wind Industry grew 2.8% to ₹479.6 crore, while exports rose 40.4% to ₹549.0 crore, compared with a 16.4% rise in domestic revenue to ₹1,243 crore.
What targets has Bonfiglioli management set for CY26 to CY28?
Bonfiglioli management expects revenue growth of about 20% in CY26 and aims for revenue compound annual growth of about 15% over CY26 to CY28. Management also aims to maintain EBITDA margin in the vicinity of 18.5% over that period, which is a target rather than a reported result.
Management said it intends to grow faster than its end markets through new products, market-share gains, localisation and higher exports. It identified turbine-capacity additions, new installations and replacement demand from Indian and global wind-turbine OEMs as factors expected to support Wind Industry demand and exports.
The reported 9MCY26 revenue of ₹1,792 crore provides context for the CY26 expectation, compared with full-year CY25 revenue of ₹2,013.5 crore. Full-year CY25 EBITDA was ₹370.8 crore at an 18.4% margin, while EBITDA for 9MCY26 was ₹353.4 crore at a 19.7% margin.
The presentation does not disclose a quarterly revenue target, order book or capacity-expansion timetable for the remainder of CY26. It also states that forward-looking statements are subject to risks and uncertainties, including earnings fluctuations, competition, economic conditions, policy actions and the ability to manage growth.
Conclusion
Bonfiglioli’s first listed-company results showed faster growth in EBITDA and profit than in revenue during Q3CY26, accompanied by year-on-year expansion in EBITDA, EBIT and profit-after-tax margins. Off-Highway Mobility and exports outgrew the other disclosed segments and markets, shifting the revenue mix toward those businesses.
The next reported period will indicate progress against management’s expectation of about 20% CY26 revenue growth and its CY26-CY28 target of about 15% revenue compound annual growth with EBITDA margin near 18.5%. The presentation also makes export growth, localisation, new products and wind demand from installations and replacements relevant areas to watch.