










Denta H1 FY27 profit drops 35% as revenue and margins fall
Key highlights
- Denta’s H1 FY27 PAT fell 35% to ₹24.32 crore from ₹37.48 crore in H1 FY26.
- H1 FY27 revenue declined 9% to ₹128.79 crore, while EBITDA margin fell to 26.3% from 36.3%.
- Q2 FY27 revenue rose sequentially to ₹69.22 crore from ₹58.66 crore in Q1 FY27.
- Denta reported a ₹782.44 crore order book and won two July 2026 irrigation projects worth about ₹65.566 crore.
powered by IRIS
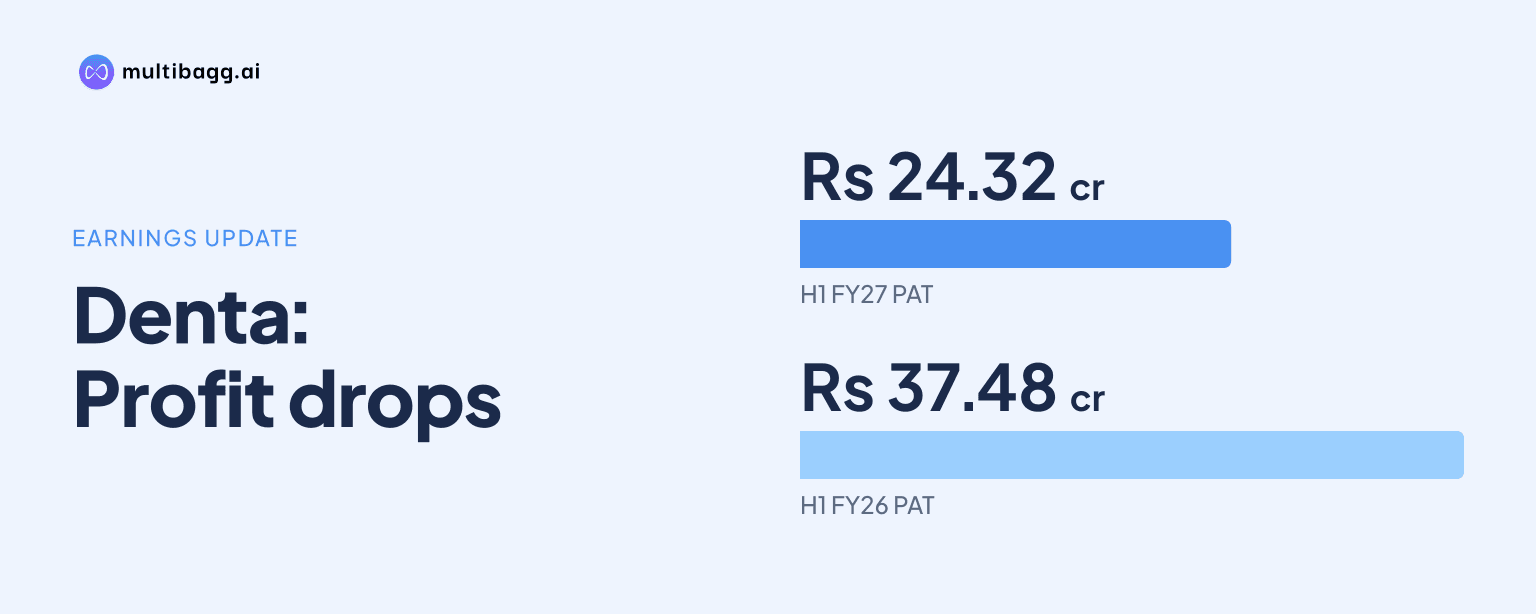
Denta Water and Infra Solutions Limited (Denta) reported profit after tax of ₹24.32 crore for H1 FY27, down 35% year on year, after revenue declined 9% to ₹128.79 crore and the EBITDA margin fell to 26.3%. Management attributed the moderation to Karnataka’s administrative transition, payment and approval cycles, and monsoon conditions.
Know Denta Water & Infra Solutions inside out
Results, valuation, peers and who's buying, in one view.
What happened to Denta’s H1 FY27 profit and revenue?
Denta’s H1 FY27 profit after tax, or PAT, fell to ₹24.32 crore from ₹37.48 crore in H1 FY26, a decline of about 35%. Revenue for the half year ended September 30, 2026 fell to ₹128.79 crore from ₹141.55 crore, a reduction of about 9%, showing that the fall in earnings was substantially larger than the decrease in revenue.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, declined to ₹33.58 crore in H1 FY27 from ₹51.30 crore a year earlier. EBITDA margin, which measures EBITDA as a share of revenue, decreased by 10 percentage points to 26.3% from 36.3%, while PAT margin fell to 19.0% from 26.5%.
Denta’s earnings per share, or EPS, also declined to ₹9.1 in H1 FY27 from ₹14.0 in H1 FY26. The simultaneous decline in EBITDA, PAT and EPS follows the lower half-year revenue base and the margin change disclosed in Denta’s financial-performance table.
What caused Denta’s H1 FY27 earnings decline?
Management said Karnataka’s state-government transition early in FY27 and subsequent monsoon conditions affected project approvals, payment cycles and on-ground execution. Denta described these operating conditions as moderating its financial performance during the first half, when revenue was ₹128.79 crore and PAT was ₹24.32 crore.
The presentation does not quantify the separate financial effect of each approval, payment or weather-related factor. It does, however, identify the sequence of mechanisms: administrative transition affected approvals and payments, while monsoon conditions affected field execution in the water-infrastructure sector.
The change in profitability was more pronounced than the revenue change. H1 revenue declined by about 9%, whereas EBITDA declined by about 35%, and the EBITDA margin moved from 36.3% to 26.3%; PAT margin similarly dropped 7.5 percentage points to 19.0%.
How did Denta’s Q2 FY27 performance compare with Q1 and last year?
Denta’s Q2 FY27 revenue improved sequentially to ₹69.22 crore from ₹58.66 crore in Q1 FY27, but remained below ₹74.27 crore in Q2 FY26. The quarter-on-quarter increase was about 18%, which management cited as evidence of a gradual recovery in execution momentum, while the year-on-year comparison still showed lower revenue.
Q2 FY27 EBITDA was ₹18.15 crore, compared with ₹15.43 crore in Q1 FY27 and ₹26.31 crore in Q2 FY26. PAT followed the same pattern, rising to ₹13.15 crore from ₹11.17 crore in Q1 FY27 but remaining below ₹18.93 crore in the prior-year quarter.
Margins did not recover sequentially in Q2 FY27 despite the higher revenue. EBITDA margin was 26.2% in Q2 FY27 versus 26.3% in Q1 FY27 and 35.4% in Q2 FY26, while PAT margin was unchanged at 19.0% sequentially and below 25.5% a year earlier.
Got a follow-up? Ask IRIS
What order book and new projects does Denta have?
Denta reported an outstanding order book of ₹782.44 crore as of September 30, 2026. Management said this order book provides visibility for future execution, although the presentation does not disclose its project-wise composition, timing of conversion into revenue, or expected margins.
In July 2026, Denta secured two irrigation-infrastructure projects worth about ₹65.566 crore, strengthening its presence in Karnataka’s water-infrastructure segment. Denta also cited its Mukkumpi Lift Irrigation Project as an example of work intended to improve groundwater recharge and regional irrigation facilities.
Denta’s September 30 snapshot listed 32 ongoing projects and 50 completed projects over 11 years since incorporation. Its stated operating scope includes water management infrastructure design, installation and commissioning, alongside road and rail infrastructure, which places the July irrigation awards within its disclosed water segment.
What does Denta expect in the second half of FY27?
Management expects execution momentum to improve in the second half of FY27 because Denta traditionally records higher execution activity in that period. This expectation is based on management’s view that weather conditions could become more favourable and administrative processes could normalise after the disruptions described for the first half.
Denta said its operational priorities are accelerating project execution, improving operational efficiency and pursuing work in irrigation, drinking-water supply, wastewater management and groundwater recharge. These are stated management plans rather than financial guidance, and the presentation gives no revenue, margin or profit target for H2 FY27.
The outlook therefore depends on the execution of the ₹782.44 crore order book, the timing of approvals and payments, and on-ground conditions. The presentation’s disclosed sequential movement offers one data point: Q2 FY27 revenue of ₹69.22 crore was higher than Q1 FY27 revenue of ₹58.66 crore, although Q2 margins remained near Q1 levels.
Conclusion
Denta’s H1 FY27 results show that a 9% decline in revenue to ₹128.79 crore coincided with a larger 35% fall in both EBITDA and PAT, as EBITDA margin decreased to 26.3% from 36.3%. Management linked the outcome to Karnataka approval and payment cycles and monsoon-related execution disruption, while Q2 revenue improved from Q1.
The next point to watch is whether Denta’s expected second-half seasonal execution increase translates into revenue from its ₹782.44 crore order book. Management has also pointed to administrative normalisation, more favourable weather and the two July 2026 irrigation awards worth ₹65.566 crore, but has not issued a quantified H2 FY27 target.