










Denta Water Q2 profit falls 31% as EBITDA margin contracts
Key highlights
- Denta Water reported Q2 FY27 PAT of Rs 13.15 crore, down from Rs 18.93 crore in Q2 FY26.
- Q2 FY27 EBITDA margin was 26.21%, compared with 35.42% a year earlier.
- H1 FY27 operating revenue was Rs 127.89 crore, versus Rs 141.55 crore in H1 FY26.
- Denta Water's confirmed order book stood at Rs 782.44 crore as of September 30, 2026.
powered by IRIS
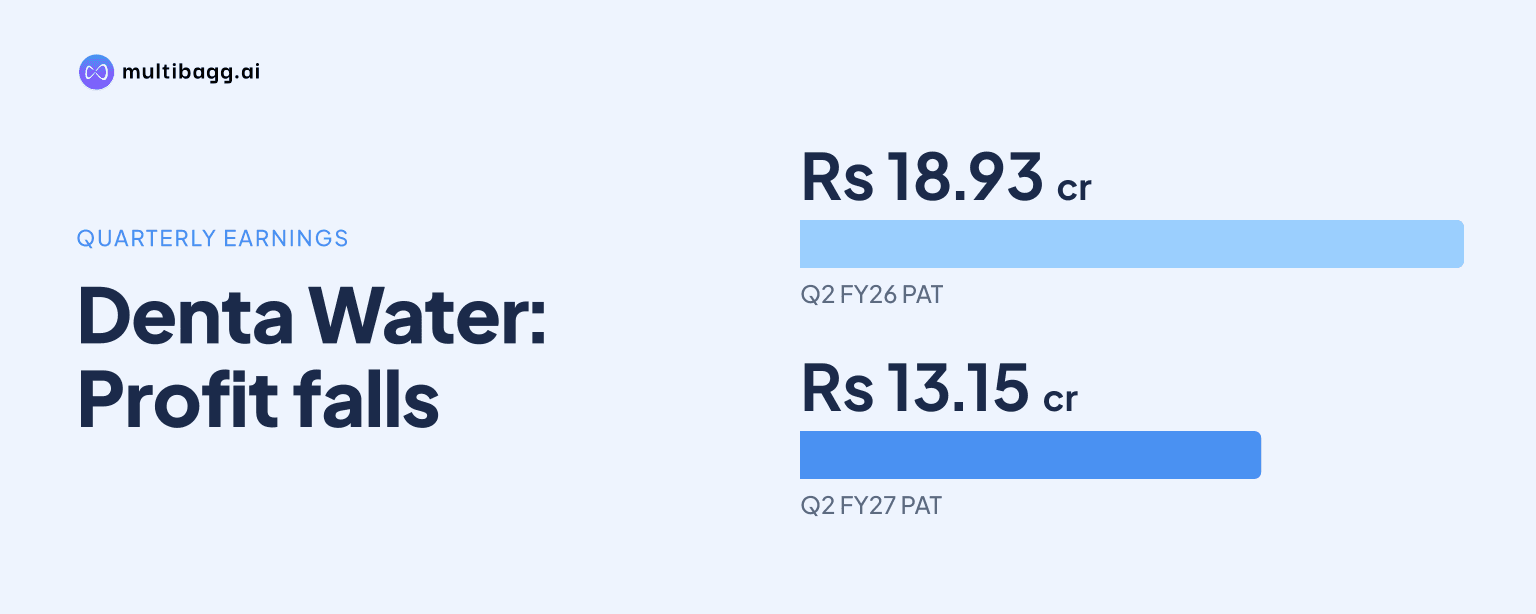
Denta Water and Infra Solutions Limited reported Q2 FY27 profit after tax of Rs 13.15 crore, down 31% from Rs 18.93 crore a year earlier, while EBITDA margin fell to 26.21% from 35.42%. Denta Water attributed first-half project-execution conditions to the monsoon and reported an order book of Rs 782.44 crore as of September 30, 2026.
Know Denta Water & Infra Solutions inside out
Results, valuation, peers and who's buying, in one view.
Why did Denta Water's Q2 FY27 profit decline?
Denta Water's Q2 FY27 profit after tax, or PAT, fell by Rs 5.78 crore year on year, from Rs 18.93 crore in Q2 FY26 to Rs 13.15 crore. The decline accompanied operating revenue of Rs 69.22 crore, compared with Rs 74.27 crore in the corresponding quarter of the previous year, a reduction of Rs 5.05 crore.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, declined faster than revenue, falling to Rs 18.15 crore from Rs 26.31 crore. EBITDA margin consequently declined by 9.21 percentage points to 26.21%, while PAT margin declined by 6.50 percentage points to 18.99% from 25.49%.
Denta Water said operating revenue grew 18% sequentially in Q2 FY27, although the announcement did not provide the preceding quarter's revenue. The available disclosures therefore show a sequential revenue increase, but year-on-year declines in Q2 revenue, EBITDA, PAT, EBITDA margin, PAT margin and EPS.
How did Denta Water perform in H1 FY27?
Denta Water reported H1 FY27 operating revenue of Rs 127.89 crore, compared with Rs 141.55 crore in H1 FY26, a fall of Rs 13.66 crore. EBITDA declined to Rs 33.58 crore from Rs 51.30 crore, while PAT fell to Rs 24.32 crore from Rs 37.48 crore over the same six-month periods.
The H1 FY27 EBITDA margin was 26.25%, compared with 36.25% in H1 FY26, a 10.00-percentage-point decline. PAT margin decreased by 7.47 percentage points to 19.01% from 26.48%, while EPS for the half year ended September 30, 2026 was Rs 9.11, against Rs 14.04 a year earlier.
Chairman C. Mruthyunjaya Swamy said the H1 FY27 outcome reflected the seasonal nature of Denta Water's business, with monsoon conditions affecting on-ground activity and project execution. He said the business typically records higher execution activity in the second half and management expects execution momentum to improve as weather conditions become more favourable.
Got a follow-up? Ask IRIS
What does Denta Water's Rs 782.44 crore order book include?
Denta Water reported a confirmed order book of Rs 782.44 crore as of September 30, 2026, including orders secured during the period. The announcement did not provide a project-wise division of that balance or a timetable for converting the order book into revenue, but said Denta Water remains focused on project execution and order-book growth.
In July 2026, Denta Water secured new projects worth about Rs 65.57 crore in Karnataka's irrigation and water-infrastructure segment. These awards included a turnkey irrigation-infrastructure project from Karnataka Neeravari Nigam Limited, or KNNL, for pickup canals, lift-irrigation systems and associated infrastructure under the KMERC Grant in Ballari district.
Denta Water also secured a subcontract to restore and improve lift-irrigation infrastructure under the Jalibenchi Lift Irrigation Scheme. The release does not disclose the individual value of either the KNNL project or the Jalibenchi subcontract, so their respective contributions to the Rs 65.57 crore of July awards cannot be determined from the announcement.
What is happening at the Mukkumpi Lift Irrigation Project?
Denta Water is advancing the Mukkumpi Lift Irrigation Project, which involves supplying six tanks intended to facilitate groundwater recharge and strengthen irrigation infrastructure. The six tanks are Hirebenakal, Venktagiri, HRG Camp, Lingadalli, Mukkumpi and Chikkbenakal, with water intended to be pumped from the Tungabhadra River.
Denta Water said the project is intended to improve underground water availability and irrigation facilities in surrounding areas, supporting agricultural activity. The announcement does not state the project value, completion date, water capacity, geographic coverage or area of agricultural land expected to benefit from the six-tank project.
Management identified Mukkumpi as an example of Denta Water's water-infrastructure execution work. After the September 30, 2026 reporting date, Denta Water said it would continue to pursue opportunities in irrigation, drinking-water supply, wastewater management and groundwater recharge.
Conclusion
Denta Water's Q2 and H1 FY27 disclosures show that the year-on-year slowdown extended from revenue to profitability: Q2 PAT fell to Rs 13.15 crore and H1 PAT to Rs 24.32 crore, while EBITDA margin declined by 9.21 percentage points in Q2 and 10.00 percentage points in H1. The Rs 782.44 crore order book and approximately Rs 65.57 crore of July awards represent disclosed work available for execution.
The next point to watch is whether Denta Water delivers the higher second-half execution activity management expects as weather conditions become more favourable. Progress on the six-tank Mukkumpi Lift Irrigation Project and conversion of the September 30, 2026 order book into revenue will also matter, though the release gives no project-completion schedules or order-book execution milestones.