










Pakka accepts Pakka Impact tax exposure as NCLT preserves recovery
Key highlights
- The NCLT sanctioned Pakka Impact’s merger into Pakka on 3 November 2026 and set 1 April 2026 as the appointed date.
- Pakka Impact’s disclosed outstanding TDS demand was Rs 10.6291 lakh under TAN LKNY05147C.
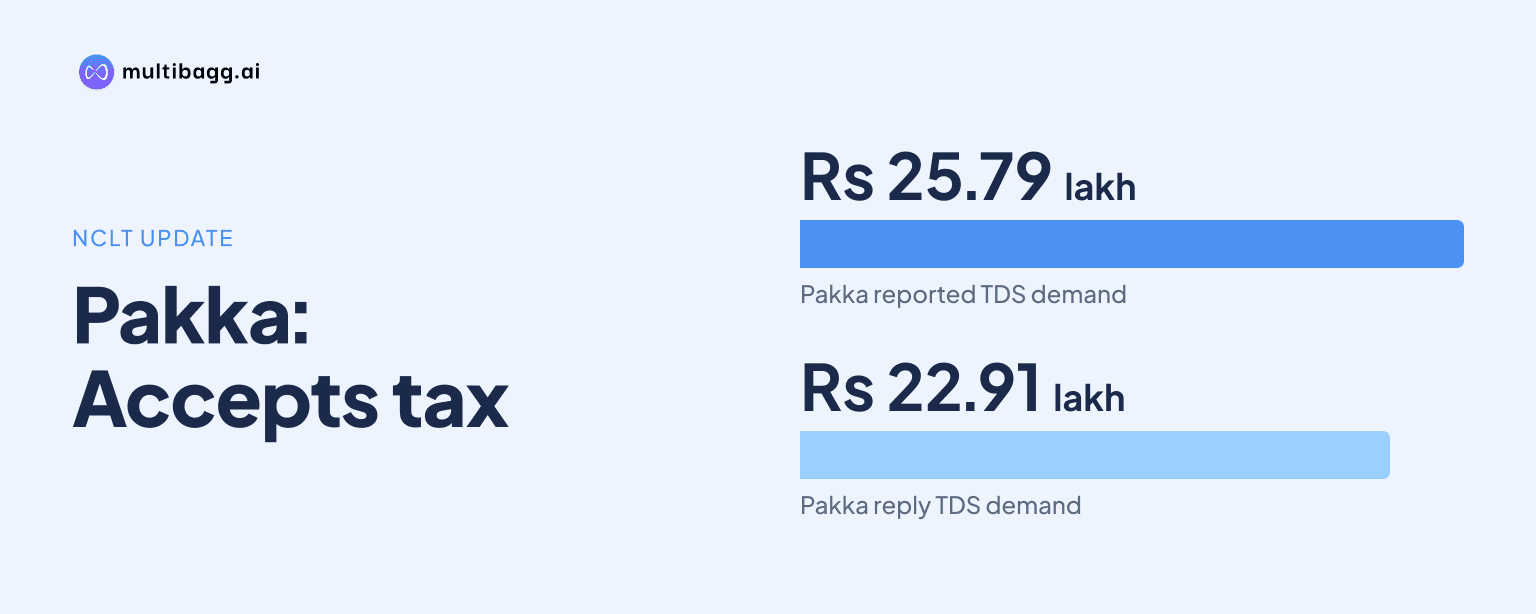
- The Income Tax Department reported Rs 25.7933 lakh against Pakka, while Pakka’s reply scheduled Rs 22.90581 lakh.
- Pakka agreed that future tax proceedings involving Pakka Impact may continue against it after dissolution.
powered by IRIS
Pakka Limited won National Company Law Tribunal (NCLT) approval on 3 November 2026 to merge Pakka Impact Limited while accepting responsibility for liabilities ultimately found payable and allowing future recovery action against the dissolved subsidiary to continue against Pakka; the undertaking covers Pakka Impact’s Rs 10.6291 lakh outstanding tax deducted at source demand.
Know Pakka inside out
Results, valuation, peers and who's buying, in one view.
What did the NCLT approve for Pakka?
The NCLT sanctioned Pakka Impact’s amalgamation with Pakka on 3 November 2026 and fixed 1 April 2026 as the appointed date, replacing the 1 April 2025 date proposed in the petition. The tribunal said the scheme would bind shareholders and creditors from the appointed date, subject to that modification.
The appointed date is distinct from the effective date, which the order defines as the point when post-order merger steps are completed and a report is submitted to the Registrar of Companies. The Official Liquidator reported on 16 September 2026 that it had no objection to Pakka Impact’s dissolution without winding up, and the companies said in an 11 October 2026 affidavit that they had received no public objection.
What income-tax demands were reported against Pakka?
The Income Tax Department reported on 8 September 2026 that Rs 25.7933 lakh of demand and proceedings were outstanding against Pakka for assessment years, or AYs, 2009-10, 2018-19 and 2021-22. It said the amounts had not been paid or disclosed in the merger petition and listed demands dated 15 March 2011, 3 February 2020 and 30 December 2023.
Pakka’s 7 October 2026 reply scheduled Rs 22.90581 lakh for the same three AYs, producing a different total from the department’s Rs 25.7933 lakh figure. The largest variance is in AY 2018-19, for which the department cited Rs 3.29840 lakh while Pakka’s schedule recorded Rs 0.42731 lakh.
Pakka said its Rs 22.90581 lakh schedule comprised matters pending for rectification, rather than settled dues. The undertaking nevertheless covers these AY 2009-10, 2018-19 and 2021-22 amounts, as well as any other demand mentioned in the tribunal’s 17 September 2026 order, to the extent they are finally found payable.
What TDS demand does Pakka Impact face?
Pakka Impact faces an outstanding tax deducted at source, or TDS, demand of Rs 10.6291 lakh under tax deduction and collection account number, or TAN, LKNY05147C, according to the Income Tax Officer (TDS), Faizabad’s 31 August 2026 communication. The demand was recorded under Pakka Impact’s former name, Yash Skills Limited.
That finding followed a 10 August 2026 communication from the Income Tax Officer-1, Faizabad, which said no demand or proceedings appeared against Pakka Impact’s permanent account number, or PAN, AAACY6673L. The officer also identified TANs for verification, after which the TDS authority reported the separate TAN-linked demand.
Pakka Impact said it reconciled the Rs 10.6291 lakh amount with default summaries on the TRACES portal: Rs 1.82730 lakh for financial year, or FY, 2021-22, Rs 0.14780 lakh for FY 2022-23, Rs 8.48980 lakh for FY 2023-24 and Rs 0.16420 lakh for FY 2025-26. Its schedule records payments for several smaller items on 24 September 2026 and a correction statement filed on 6 October 2026 for a Rs 8.44660 lakh Form 24Q demand in FY 2023-24.
Got a follow-up? Ask IRIS
Why does Pakka dispute its stated income-tax demands?
Pakka said the Rs 22.90581 lakh in its schedule did not result from scrutiny assessments or adjudicated additions. In its 7 October 2026 undertaking, Pakka said the matters arose from summary processing of returns, missing credit for taxes paid, or failure to consider amounts disclosed in returns; this is Pakka’s position, not a tax-authority or NCLT finding.
For AY 2009-10, Pakka said tax and interest of Rs 5.24588 lakh had been paid through challans totalling Rs 6.37880 lakh, and that a Rs 1.13292 lakh refund was due instead of a Rs 6.75747 lakh demand. It said its rectification application was filed on 6 March 2018, with a reminder dated 31 December 2019.
For AY 2021-22, Pakka said credit for Rs 10 lakh of advance-tax challans and Rs 1.76 lakh of another credit had not been given, while interest and fees were charged in excess. The filing says representations were made on 12 March 2024 and 14 May 2024, followed by a 7 June 2024 reminder, and that the application remained pending with the department.
How will Pakka Impact tax proceedings continue after dissolution?
Pakka and Pakka Impact jointly undertook that every Pakka Impact liability under the Income-tax Act, 1961 and the Income-tax Act, 2025 for periods up to the effective date will become Pakka’s liability once the scheme takes effect. The commitment covers tax, TDS, tax collected at source, interest, fees and penalties under PAN AAACY6673L and TANs LKNY05147C and KNPY01178C.
The undertaking also states that any assessment, reassessment, recovery action or other proceeding against Pakka Impact may continue or be initiated against Pakka. Pakka agreed not to argue that a proceeding had abated or that liability was extinguished because Pakka Impact had dissolved, and agreed to preserve Pakka Impact’s books under section 239 of the Companies Act, 2013.
The NCLT separately clarified on 3 November 2026 that sanctioning the scheme did not grant an exemption from income tax, goods and services tax, stamp duty or other charges payable under law. Pakka and Pakka Impact retained their rights to pursue correction statements, rectification applications, appeals and refunds, while undertaking to deposit amounts finally found payable with applicable interest.
Conclusion
The merger order transfers Pakka Impact’s tax exposure to Pakka without restricting the Income Tax Department’s recovery or assessment rights. The disclosed matters include Pakka Impact’s Rs 10.6291 lakh TDS demand and Pakka’s disputed-demand schedule of Rs 22.90581 lakh, while the department’s separate report put Pakka’s outstanding demand and proceedings at Rs 25.7933 lakh.
The next matters to watch are the processing of Pakka Impact’s correction statements and Pakka’s pending rectification applications, including applications dating from 6 March 2018, 20 January 2020 and 12 March 2024. The merger’s effective date also remains dependent on completion of post-order steps and submission of the required report to the Registrar of Companies.