










Pakka Wrap & Carry revenue rose 75% to Rs 105.28 crore
Key highlights
- Pakka Wrap & Carry revenue rose 75% to Rs 105.28 crore in Q2FY27 from Rs 60.06 crore in Q2FY26.
- Wrap & Carry profit before tax increased to Rs 10.11 crore from Rs 1.46 crore, lifting margin to 9.6% from 2.4%.
- Wrap & Carry volume increased 40% to 10,722 tonnes in Q2FY27 from 7,659 tonnes.
- Pakka maintained exports at 30% of Wrap & Carry sales and disclosed a solar-glass interleaving deal with Reliance.
powered by IRIS
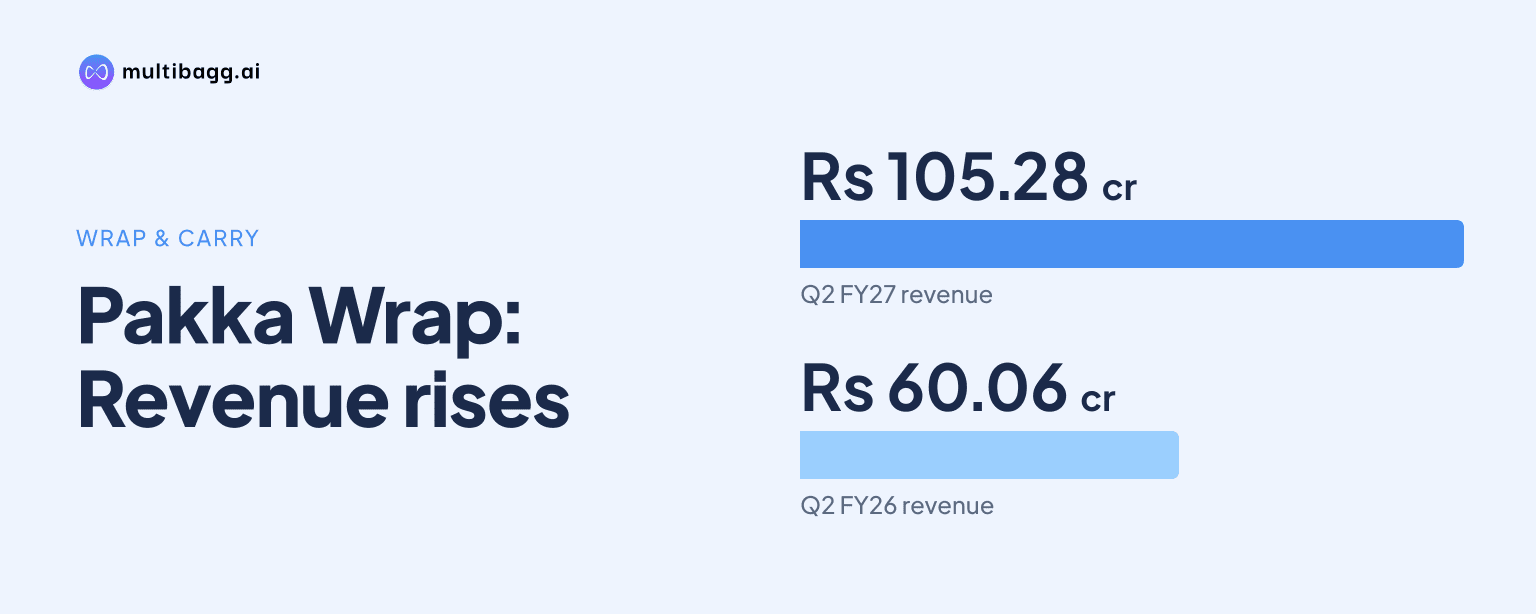
Pakka’s Wrap & Carry segment generated Rs 105.28 crore of revenue in Q2FY27, up 75% from Rs 60.06 crore in Q2FY26, while profit before tax rose to Rs 10.11 crore from Rs 1.46 crore. The segment also disclosed a new solar-glass interleaving deal with Reliance.
Know Pakka inside out
Results, valuation, peers and who's buying, in one view.
How fast did Pakka Wrap & Carry grow in Q2FY27?
Pakka Wrap & Carry revenue increased by Rs 45.22 crore, or 75%, year on year to Rs 105.28 crore in Q2FY27. The Q2FY26 revenue base was Rs 60.06 crore, while Food Service, the other separately reported segment, generated Rs 18.77 crore in Q2FY27.
Wrap & Carry volume rose 40% to 10,722 tonnes in Q2FY27 from 7,659 tonnes in Q2FY26, an increase of 3,063 tonnes. Revenue grew faster than volume over the two periods, and Pakka separately cited higher net sales realisation, or NSR, in Q2 versus Q2 last year.
What changed in Pakka Wrap & Carry profitability?
Pakka Wrap & Carry profit before tax increased by Rs 8.65 crore to Rs 10.11 crore in Q2FY27 from Rs 1.46 crore in Q2FY26. The profit-before-tax margin rose by 7.2 percentage points to 9.6% from 2.4% over the same period.
Pakka linked the Q2FY27 result to higher NSR and better contribution from pulp sales through innovative dry pulp. The presentation does not disclose separate pulp revenue, volume or margin within the Rs 105.28 crore Wrap & Carry revenue total, or quantify the contribution from realisation relative to the 10,722 tonnes of segment volume.
At the company level, earnings before interest, tax, depreciation and amortisation, or EBITDA, rose to Rs 33 crore in H1FY27 from Rs 16.2 crore in H1FY26. EBITDA margin increased to 13.7% from 10.3%, while reported profit before tax rose to Rs 13 crore from Rs 6.9 crore; these are half-year company figures rather than segment EBITDA.
What is Pakka’s Reliance interleaving deal?
Pakka disclosed a new interleaving deal with Reliance, which the presentation describes as India’s biggest facility for solar glass. Pakka identifies interleaving as a new Wrap & Carry segment, but provides no contract value, start date, production volume or customer-specific revenue for Q2FY27.
The disclosed use case is interleaving paper at the solar-glass facility rather than a quantified financial outcome. Therefore, the Rs 45.22 crore Q2FY27 revenue increase cannot be attributed specifically to the Reliance deal based on the presentation, which also does not say whether the business contributed for all or part of the quarter.
Pakka separately distinguished reported and adjusted company profit before tax in H1FY27 because of a one-time Rs 4.7 crore loss on disposal of property, plant and equipment. Reported profit before tax was Rs 13 crore and adjusted profit before tax was Rs 17.7 crore, while no comparable adjustment was presented for Wrap & Carry’s Rs 10.11 crore Q2FY27 profit before tax.
Got a follow-up? Ask IRIS
How did exports and pulp support Pakka Wrap & Carry?
Pakka maintained exports at 30% of Wrap & Carry sales despite geopolitical challenges, according to the presentation. It did not disclose Q2FY27 export revenue in rupees, the affected export markets, or the comparable Q2FY26 export percentage.
Pakka also cited improved pulp-sales contribution from innovative dry pulp alongside higher NSR and the 40% volume increase to 10,722 tonnes. The presentation does not disclose dry-pulp selling prices, costs or gross-margin effects, so their separate contribution to the Q2FY27 profit-before-tax margin of 9.6% is not specified.
Company EBITDA, excluding other income, was Rs 10.2 crore at a 10.0% margin in Q4FY26, Rs 15.4 crore at 13.2% in Q1FY27 and Rs 17.6 crore at 14.2% in Q2FY27. These company-level figures show a sequential margin increase during FY27, but they are not Wrap & Carry EBITDA figures.
How does Pakka Wrap & Carry compare with Food Service?
Pakka Wrap & Carry generated Rs 105.28 crore in Q2FY27 revenue, Rs 86.51 crore more than Food Service’s Rs 18.77 crore. Food Service revenue increased from Rs 15.76 crore in Q2FY26, but its reported loss before tax widened to Rs 1.20 crore from Rs 1.06 crore.
Food Service reported 26% year-on-year revenue growth for H1FY27 and added 35 cities, six customers and 10 products compared with last year. Those additions contrast with Wrap & Carry’s solar-glass interleaving segment and 30% export share, while the Q2FY27 reporting shows different profit outcomes between the businesses.
Conclusion
Pakka’s Q2FY27 data show Wrap & Carry combining 75% revenue growth to Rs 105.28 crore with a profit-before-tax margin increase to 9.6% from 2.4%. Volume rose 40%, and Pakka identified higher NSR, dry-pulp contribution and a 30% export mix as operating factors; Food Service generated Rs 18.77 crore but reported a Rs 1.20 crore loss before tax.
The next disclosures to watch are details of the Reliance solar-glass interleaving deal, including revenue, volume and timing, which Pakka did not provide in Q2FY27. Pakka’s ability to maintain its 30% export mix amid stated geopolitical challenges and the company EBITDA margin of 14.2% in Q2FY27 will also remain relevant.