










Pakka targets December PM4 start-up after October utilities
Key highlights
- Pakka targets a December 2026 PM4 start-up after its recovery boiler and 15 MW turbine started in October 2026.
- Capital work-in-progress rose to Rs 734.4 crore at September 2026 from Rs 554.7 crore at March 2026.
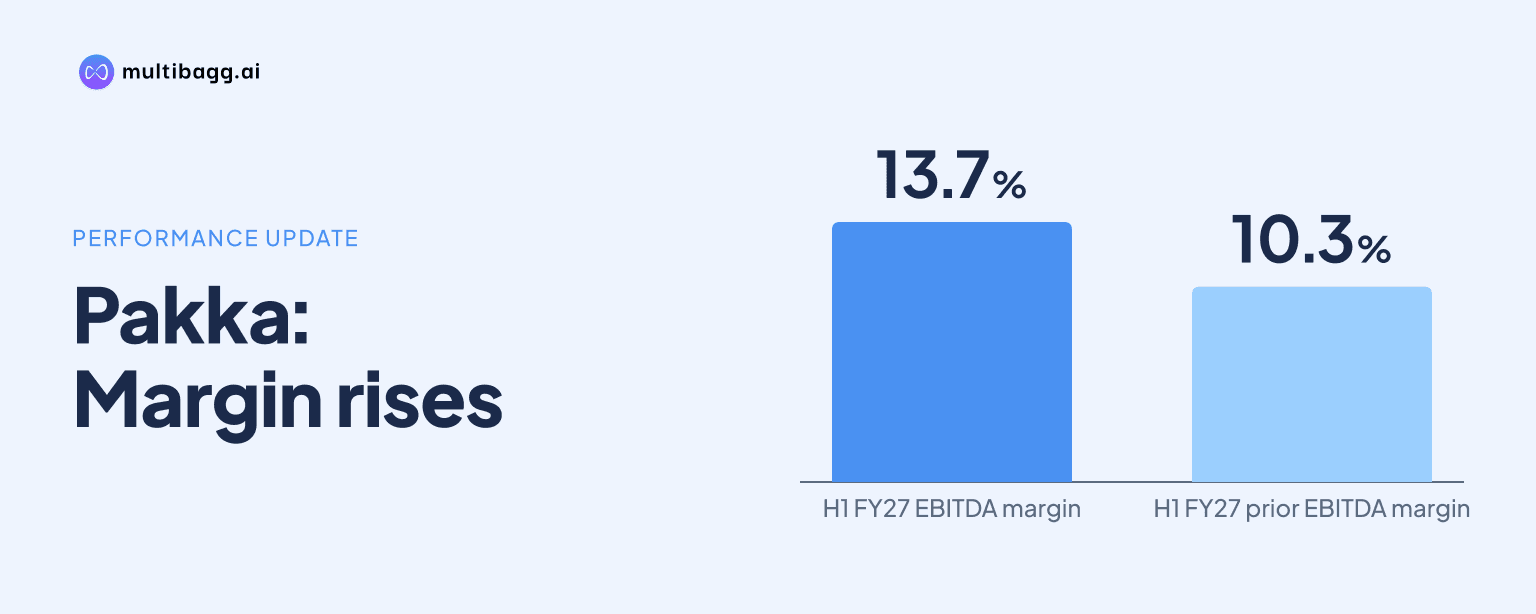
- H1 FY27 revenue reached Rs 241.2 crore, up 52.6% year on year, and EBITDA margin rose to 13.7% from 10.3%.
- Pakka says 500-plus tonnes a month of equivalent flexC base grades are selling, about 17% of PM4 capacity.
powered by IRIS
Pakka Limited targets a December 2026 start-up for Paper Machine 4 (PM4) after Project Jagriti’s recovery boiler and 15-megawatt turbine started in October 2026 and entered stabilisation, with capital work-in-progress reaching Rs 734.4 crore at September 2026 from Rs 554.7 crore in March 2026.
Know Pakka inside out
Results, valuation, peers and who's buying, in one view.
When will Pakka start PM4?
Pakka plans to start PM4 in December 2026, according to its Project Jagriti progress update. The company reports that the pulp-mill expansion is complete, while the recovery boiler, power boiler and 15-megawatt (MW) power turbine were started in October 2026 and were being stabilised.
The December event is a stated commissioning target rather than evidence of commercial output. Pakka’s Q3 FY27 commitments specifically include commissioning PM4, and its stated way forward is to complete commissioning and stabilise Project Jagriti operations before progressively increasing capacity utilisation.
PM4 is intended to enable in-house manufacturing of specialised flexC base paper at scale. Pakka describes flexC as a fibre-based flexible packaging material and lists release liners, labels, heat-sealable bags, tea and sugar sachets, food and confectionery pouches, and seed or medical packaging as initial application areas.
What has Project Jagriti completed so far?
Pakka has completed the pulp-mill expansion and started the recovery boiler and 15 MW turbine in October 2026, leaving PM4’s planned December 2026 start-up as the next disclosed operating milestone. The presentation does not state the added pulp, paper or PM4 capacity in tonnes per day or tonnes per annum.
The recovery boiler and turbine are under stabilisation, an important distinction from completed stable operation. The update says the recovery boiler started up in October 2026 and was stabilising; the same status applies to the turbine. Pakka’s Q2 commitments slide additionally says the recovery boiler, power boiler and turbine were started in October.
The project is being developed at Pakka’s integrated Ayodhya facility, which had existing installed capacity at 31 March 2026 of 130 tonnes per day (TPD) of pulp, 39,600 tonnes per annum (TPA) of packaging paper, 14.5 TPD of compostable tableware and 8.5 MW of biomass-based power. Those are existing-site figures and should not be treated as Jagriti’s incremental capacity.
How much has Pakka invested in Project Jagriti?
Pakka had Rs 734.4 crore of capital work-in-progress at 30 September 2026, up Rs 179.7 crore from Rs 554.7 crore at 31 March 2026. Capital work-in-progress is the balance-sheet category that captures assets under construction and is the clearest disclosed financial measure of the project’s build-out.
The increase in work-in-progress occurred alongside a shift in borrowing mix. Non-current borrowings increased to Rs 448.8 crore in September 2026 from Rs 307.9 crore in March 2026, while current borrowings fell to Rs 90.6 crore from Rs 149.2 crore. Total liabilities nonetheless rose to Rs 730.5 crore from Rs 645.7 crore over the same period.
Cash-flow data show the expansion’s funding demands during the first half. Net cash used in investing activities was Rs 204.7 crore in H1 FY27, compared with Rs 174.3 crore in H1 FY26, while net cash from financing activities was Rs 127.4 crore against Rs 88.6 crore. Cash and cash equivalents ended H1 FY27 at Rs 1.2 crore, compared with Rs 17.9 crore at the beginning of the period.
Got a follow-up? Ask IRIS
What demand has Pakka identified for PM4 products?
Pakka says more than 500 tonnes a month of equivalent flexC base grades are already selling, equal to about 17% of PM4 capacity. The company says it completed pilot trials in Europe and held a partner reveal at the plant before PM4’s planned December 2026 start-up.
That pre-launch sales indication relates to equivalent grades rather than reported PM4 production. Pakka has not disclosed PM4’s monthly capacity in the supplied presentation, but the stated 17% relationship implies that the company is using the 500-plus-tonne monthly sales figure as evidence of an initial market base ahead of commissioning.
The commercial programme remains at multiple stages. Pakka plans in Q3 FY27 to launch flexC base to partners and distributors, while flexible-packaging product development is described as advanced and customer trials as underway. Its other Q3 FY27 commitments include advancing development of a non-metallised flexC structure.
The project also sits beside Pakka’s existing businesses. Wrap & Carry generated Rs 292.83 crore in FY26, or 82% of FY26 segment revenue cited in the presentation, while the CHUK food-service business generated Rs 62.97 crore in FY26, up from Rs 54.69 crore in FY25. H1 FY27 Food Service revenue growth was 26% year on year, with 35 new cities, six new customers and 10 new products added.
How is Pakka’s financial performance changing during commissioning?
Pakka reported H1 FY27 revenue from operations of Rs 241.2 crore, up 52.6% from Rs 158.1 crore in H1 FY26, while EBITDA rose to Rs 33.0 crore from Rs 16.2 crore. EBITDA means earnings before interest, tax, depreciation and amortisation, and the reported margin increased to 13.7% from 10.3%.
Finance cost increased to Rs 11.5 crore in H1 FY27 from Rs 5.6 crore a year earlier, while reported profit after tax rose to Rs 9.1 crore from Rs 5.2 crore. H1 FY27 profit before tax was Rs 13.0 crore after a Rs 4.7 crore exceptional loss on disposal of property, plant and equipment; before that item, profit before tax was Rs 17.7 crore.
The H1 improvement follows a lower FY26 base. FY26 revenue was Rs 355.8 crore, down from Rs 406.0 crore in FY25, and EBITDA was Rs 42.1 crore against Rs 76.2 crore. FY26 EBITDA margin was 11.8%, compared with 18.8% in FY25, making the H1 FY27 margin of 13.7% higher than FY26’s full-year level but below FY25’s reported margin.
Conclusion
Pakka is moving Project Jagriti from construction toward operation: its pulp-mill expansion is complete, October 2026 utility start-ups are under stabilisation, and PM4 is targeted for December 2026. The project’s financial footprint is visible in Rs 734.4 crore of September capital work-in-progress, higher investment cash outflow and increased non-current borrowings, alongside H1 revenue growth and a 13.7% EBITDA margin.
The next disclosed marker is PM4 commissioning in Q3 FY27, followed by stabilisation and progressive capacity utilisation. Management’s related commitments are to launch flexC base to partners and distributors, advance non-metallised flexC development and reach Food Service profitability; the presentation does not provide a PM4 capacity figure, a commercial-production date or a project cost target.