










Pakka NCLT sanctions Pakka Impact merger from April 2026
Key highlights
- NCLT sanctioned Pakka’s absorption of wholly owned Pakka Impact on November 3, 2026.
- The tribunal changed the appointed date from April 1, 2025 to April 1, 2026.
- Pakka will issue no new shares and will cancel its Pakka Impact shareholding.
- Pakka disclosed tax demands of Rs 22.90581 lakh across AY 2009-10, AY 2018-19 and AY 2021-22.
powered by IRIS
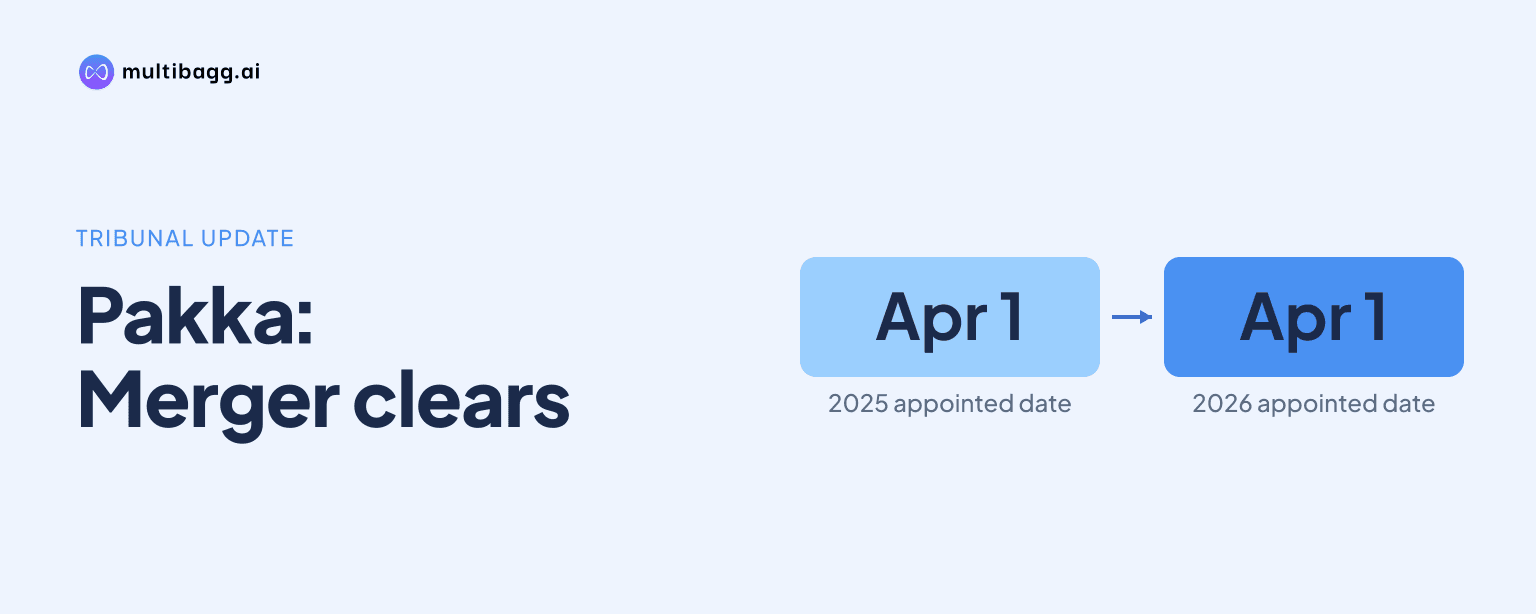
Pakka Limited received National Company Law Tribunal sanction on November 3, 2026 to absorb wholly owned subsidiary Pakka Impact Limited, with the appointed date reset to April 1, 2026 from April 1, 2025 and no new shares to be issued. The order transfers the subsidiary’s assets, liabilities, employees and proceedings when the scheme becomes effective.
Know Pakka inside out
Results, valuation, peers and who's buying, in one view.
What did NCLT sanction for Pakka?
The National Company Law Tribunal, Allahabad Bench, sanctioned Pakka’s amalgamation of Pakka Impact under Sections 230 and 232 of the Companies Act, 2013, through its order dated November 3, 2026. The tribunal said the scheme was prima facie compliant with applicable statutory requirements, necessary undertakings had been provided, and no further objections were before it.
The scheme is binding on shareholders and creditors of both petitioner companies from the appointed date of April 1, 2026. The order also says its sanction does not exempt either company from stamp duty, income tax, Goods and Services Tax, or other payments, permissions and compliance requirements that may apply under law.
Pakka was listed on BSE and NSE when the tribunal considered the scheme. The order records that no formal approval, no-objection certificate or vetting was required from BSE, NSE or the Securities and Exchange Board of India under the June 20, 2023 scheme circular because the transaction combines a wholly owned subsidiary with its parent; the scheme was nevertheless filed with BSE and NSE for disclosure.
Why did NCLT set April 1, 2026 as the appointed date?
NCLT set April 1, 2026 as the appointed date instead of the April 1, 2025 date proposed in the petition. The tribunal cited the timetable of the proceedings: the first-motion petition was filed on June 12, 2024, the first-motion order was passed on December 9, 2025, and the second-motion order was issued on November 3, 2026.
The appointed date differs from the effective date under the scheme. The order defines the effective date as the point at which the merger is completed after the relevant second-motion orders and submission of a report to the Registrar of Companies, or RoC; the November 3, 2026 order is the second-motion order for companies within the tribunal’s jurisdiction.
This distinction determines when the transfer directions operate. Property, liabilities, employees and proceedings move to Pakka when the scheme becomes effective, while the tribunal has made the scheme binding from April 1, 2026 as its appointed date.
What will Pakka receive and assume in the amalgamation?
Pakka will receive all property, rights and powers of Pakka Impact, without further act or deed, when the scheme becomes effective. The vesting is subject to charges already affecting those assets and occurs under Sections 230 and 232 of the Companies Act, 2013.
Pakka will also assume all liabilities and duties of Pakka Impact upon effectiveness. Employees in the subsidiary’s service on the effective date will become Pakka employees under the sanctioned scheme, while legal proceedings pending by or against Pakka Impact will continue by or against Pakka.
The order separately preserves the continuity of tax administration. Assessments, reassessments, recovery actions and other proceedings involving Pakka Impact may continue or be initiated against Pakka, and Pakka cannot contend that such proceedings have abated because the subsidiary is dissolved.
Got a follow-up? Ask IRIS
Will Pakka issue shares for Pakka Impact?
Pakka will not issue new shares because Pakka Impact is its wholly owned subsidiary. Instead, the equity shares of Pakka Impact held by Pakka directly or through nominees will be cancelled in accordance with the sanctioned scheme.
The order therefore contains no exchange ratio or allotment of Pakka equity to external holders. Its share-cancellation direction follows the existing parent-subsidiary ownership structure and is one reason the June 20, 2023 SEBI scheme circular did not require a formal exchange or regulatory vetting process for this amalgamation.
Pakka Impact will stand dissolved without winding up once a certified copy of the order is delivered to the RoC for registration. The companies must deliver the certified copy within 30 days of receiving it, after which the RoC is directed to consolidate documents and files relating to the two companies under Pakka’s file.
What tax obligations and filings move to Pakka?
Pakka will be responsible for Pakka Impact’s liabilities under the Income-tax Act, 1961 and the Income-tax Act, 2025 for periods up to the effective date. These liabilities include tax, tax deducted or collected at source, interest, fees and penalties, whether already raised or raised later, while the subsidiary’s pending tax proceedings can continue against Pakka.
The order identifies a demand of Rs 10.62910 lakh against Pakka Impact under TAN LKNY05147C, subject to processing of correction statements and challan credits. This includes Rs 1.79230 lakh for Form 240 for the fourth quarter of financial year 2021-22. Pakka’s demands for assessment years 2009-10, 2018-19 and 2021-22 aggregate Rs 22.90581 lakh, which is higher than the disclosed Pakka Impact demand.
These demands remain subject to correction, rectification, appeal and other remedies, and only amounts finally found payable under law must be discharged with applicable interest. Pakka must preserve Pakka Impact’s books and papers under Section 239 of the Companies Act, 2013, and must not treat the merger sanction as a waiver or concession of tax liability.
If required by the approved scheme, Pakka must file a modified income-tax return under Section 314(1) of the Income Tax Act, 2025 within six months from the end of November 2026. To the extent statutorily available and together with related obligations, Pakka may also receive Pakka Impact’s incentives, subsidies, grants, exemptions, deductions and other entitlements under customs, excise, service tax, value-added tax, sales tax, GST, entry tax and income-tax laws.
Conclusion
The November 3, 2026 order gives Pakka authority to simplify its wholly owned subsidiary structure by absorbing Pakka Impact without issuing equity. Its central modification is the tribunal’s decision to move the appointed date by one year to April 1, 2026, while maintaining continuity for the subsidiary’s assets, employees, liabilities, legal cases and tax matters.
The next disclosed steps are receipt and filing of the certified order with the RoC within 30 days, registration that leads to Pakka Impact’s dissolution without winding up, and completion of the effective-date conditions. Pakka may also need to file a modified income-tax return within six months from the end of November 2026, while the disclosed tax demands remain subject to pending correction, rectification and appellate processes.