










Data Patterns (India) Limited Sets Q2 FY27 Results Review
Key highlights
- Data Patterns will consider Q2 FY27 unaudited results on November 6, 2026.
- Motilal Oswal estimates Q2 FY27 adjusted net profit of Rs 84.5 crore, up about 72% year on year.
- Data Patterns reported Q1 FY27 revenue of Rs 116 crore and adjusted net profit of Rs 22.1 crore.
- The company had an order book of about Rs 920 crore and an executable opportunity pipeline of about Rs 2,650 crore at Q1 FY27 end.
powered by IRIS
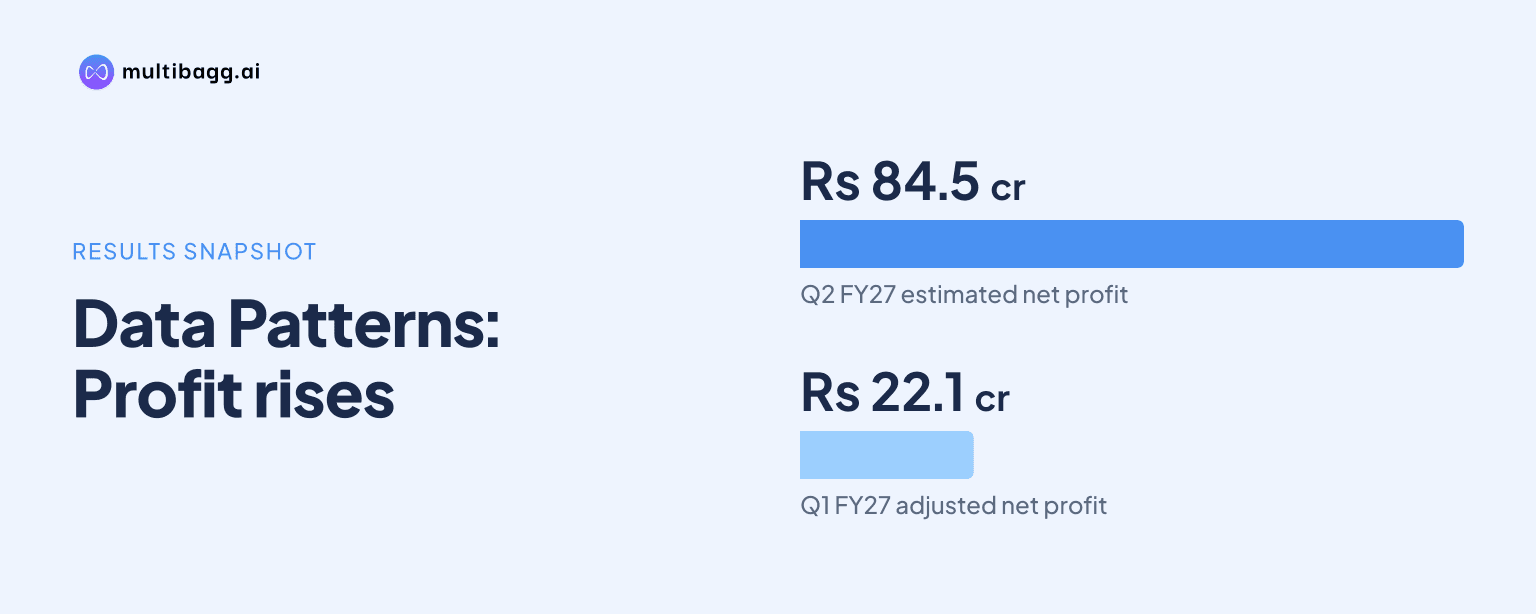
Data Patterns (India) Limited is scheduled to consider its Q2 FY27 financial results on November 6, 2026, while Motilal Oswal estimates adjusted net profit could rise 72% year on year to Rs 84.5 crore. The board meeting will consider unaudited standalone and consolidated results for the quarter and half-year ended September 30, 2026.
Know Data Patterns (India) inside out
Results, valuation, peers and who's buying, in one view.
When will Data Patterns announce its Q2 FY27 results?
Data Patterns will consider and approve its unaudited Q2 FY27 standalone and consolidated financial results at a board meeting on Friday, November 6, 2026. The company disclosed the meeting on October 30, stating that the agenda covers the quarter and half-year ended September 30, 2026. This confirms the schedule after earlier information had indicated that the date had not yet been filed with the exchanges.
The September quarter is the second quarter of FY27 and covers the period from July 1 to September 30, 2026. The reported financial statements will provide the official figures, whereas broker forecasts are estimates and may differ from the eventual outcome. Data Patterns has also scheduled an earnings conference call for November 9, 2026, at 11:00 AM IST, where management is expected to discuss consolidated and standalone performance with investors and analysts.
The call will be hosted by Go India Advisors, with company executives expected to participate. The result announcement and subsequent call are important because the June quarter was affected by customer inspection and approval delays, which management and the brokerage identified as a factor behind the lower quarterly revenue and profitability.
What is Motilal Oswal estimating for Data Patterns' September quarter?
Motilal Oswal estimates that Data Patterns could report consolidated revenue of Rs 369 crore for Q2 FY27, up 20% from Rs 307.5 crore in Q2 FY26. The brokerage expects EBITDA of Rs 104.7 crore, compared with Rs 68.5 crore a year earlier, implying growth of about 53%.
The estimate also places EBITDA margin at 28.4%, against 22.3% in the corresponding quarter last year. Adjusted net profit is forecast at Rs 84.5 crore, 72% higher than Rs 49.2 crore in Q2 FY26. These are analyst estimates, not company guidance or reported results.
The forecast reflects an expected recovery in revenue that was delayed during the June quarter. It does not establish the final quarterly performance, and investors will need to compare the reported revenue, operating margin and profit with these estimates once Data Patterns releases its financial statements.
Got a follow-up? Ask IRIS
Why was Data Patterns' Q1 FY27 performance weaker?
Data Patterns reported revenue of Rs 116 crore in Q1 FY27, up about 17% year on year, but EBITDA declined 2% to Rs 31.4 crore and adjusted net profit fell 14% to Rs 22.1 crore. Customer inspection and approval delays affected revenue recognition during the period, according to the information available on the company and brokerage outlook.
The June-quarter figures also show the uneven timing that can occur in project-led defence electronics operations. Revenue was Rs 345 crore in the March 2026 quarter and Rs 173 crore in the December 2025 quarter, compared with Rs 116 crore in June 2026. Operating profit was Rs 187 crore in March 2026, Rs 75 crore in December 2025 and Rs 25 crore in June 2026.
Motilal Oswal expects some revenue affected by the approval delays to spill into Q2 FY27. The expected improvement in the September quarter would therefore be assessed not only against the year-ago quarter, but also against the comparatively low June-quarter base. The reported result will show whether the delayed execution translated into revenue and whether operating margins recovered as estimated.
What supports Data Patterns' FY27 outlook?
Data Patterns retained its FY27 guidance for 25% revenue growth and an EBITDA margin of 35% to 40% despite the weaker first quarter. The company had an order book of about Rs 920 crore at the end of Q1 FY27, while its executable opportunity pipeline, including negotiated contracts awaiting final approvals, stood at about Rs 2,650 crore.
The stated pipeline includes opportunities in air defence radars, counter-drone systems, BrahMos seekers, naval electronics and aircraft upgrade programmes. Such programmes are relevant to future order inflows and revenue visibility, but the opportunity pipeline should not be treated as a confirmed order book because some contracts are awaiting approvals.
The company is also investing in indigenous defence technology, including electronic warfare systems, radar warning receivers and advanced communication systems. It plans to invest more than Rs 200 crore over the next two years in manufacturing infrastructure, testing facilities and artificial intelligence capabilities. These investments can support execution capacity, although they also make project conversion, margins and capital deployment relevant areas for investors to monitor.
Motilal Oswal has maintained its FY27 and FY28 estimates. Its forecasts imply compound annual growth between FY26 and FY28 of 25% for revenue, 23% for EBITDA and 30% for adjusted net profit. The November results and the management call will provide updated evidence on the pace of execution behind those projections.
Conclusion
The November 6 board meeting gives Data Patterns a formal date for its Q2 FY27 financial disclosure after a June quarter in which revenue recognition was affected by customer inspections and approvals. Motilal Oswal's estimate of Rs 369 crore revenue and Rs 84.5 crore adjusted net profit indicates an expected recovery, but the company's reported standalone and consolidated figures will be the definitive measure of performance.
Investors will next watch the published results for progress against FY27 guidance of 25% revenue growth and a 35% to 40% EBITDA margin. Management's November 9 earnings call may also clarify the status of delayed approvals, order conversion from the Rs 2,650 crore opportunity pipeline and the planned investment of more than Rs 200 crore over two years.