










Delphi World Money auditor flags ₹44.869 crore deposits
Key highlights
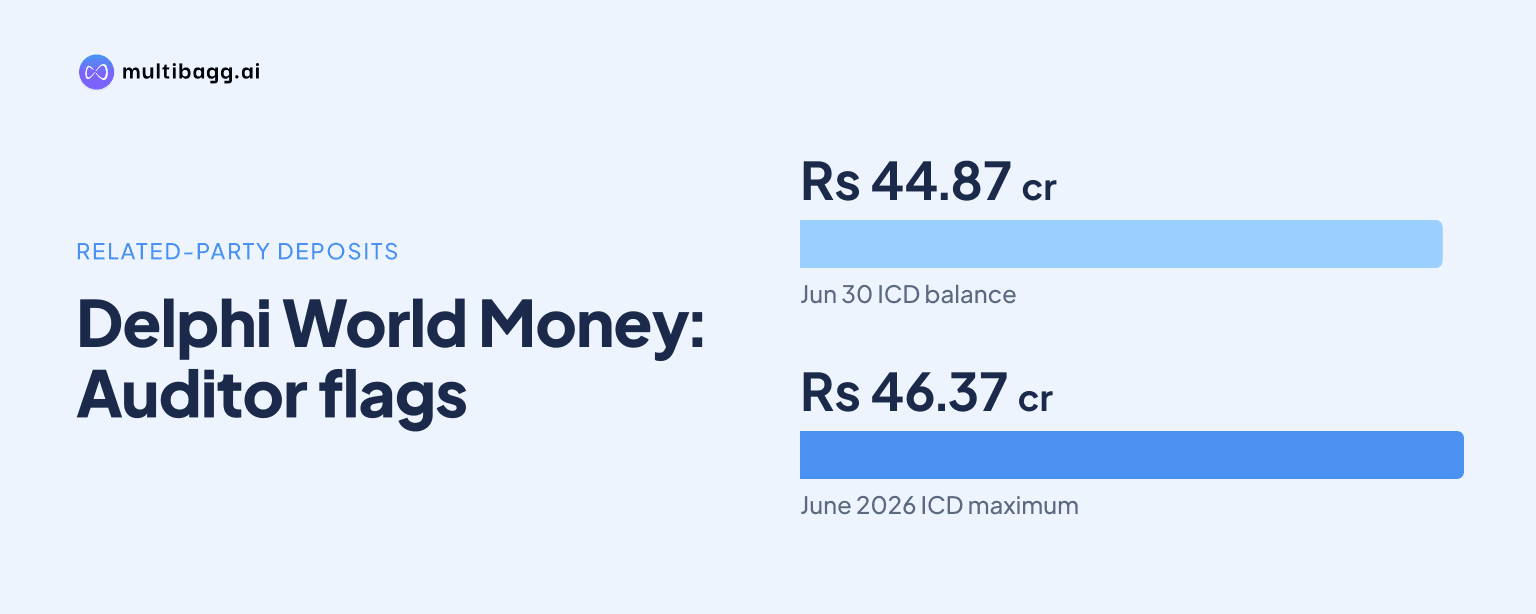
- ETPL had ₹44.869 crore of ICDs outstanding with Advik Capital Limited at June 30, 2026.
- The Advik ICD balance reached a quarterly maximum of ₹46.369 crore in the June 2026 quarter.
- The auditor said required Audit Committee and shareholder approvals were not obtained.
- ₹2.656 crore of earlier ETPL ICDs with Ebix Limited was outstanding at June 30, 2026 and was subsequently settled.
powered by IRIS
Delphi World Money Limited received a qualified review conclusion for the quarter ended June 30, 2026 because its subsidiary had ₹44.869 crore of related-party inter-corporate deposits outstanding with Advik Capital Limited without the required Audit Committee and shareholder approvals. The auditor said the resulting impact on the Group’s financial statements could not be determined.
Know Delphi World Money inside out
Results, valuation, peers and who's buying, in one view.
Why did DWML receive a qualified review conclusion?
DWML received the qualification after Ebix Travels Private Limited, or ETPL, extended inter-corporate deposits, or ICDs, to related party Advik Capital Limited during the quarter ended June 30, 2026. T R Chadha & Co LLP said it did not have sufficient appropriate evidence on the deposits’ business rationale, regulatory compliance and potential consequential implications.
The auditor issued a qualified conclusion rather than an audit opinion because the filing covers unaudited consolidated quarterly results reviewed under Standard on Review Engagements 2410. Its report dated November 11, 2026 says that, except for the possible effects of the matters in the basis for qualified conclusion, nothing came to its attention suggesting the statement failed to make required disclosures or contained a material misstatement.
The issue was not limited to a disclosure classification. The auditor said it could not determine the impact on DWML, including whether an adjustment to the June 30, 2026 consolidated statement was necessary. DWML’s accompanying statement on audit qualifications describes the qualification as one where the auditor did not quantify the impact.
The ₹46.369 crore maximum balance was ₹1.5 crore higher than the ₹44.869 crore closing balance, showing the exposure was reduced during the quarter. Separately, ₹2.656 crore of ICDs with Ebix Limited remained outstanding at June 30, 2026, and the auditor said its conclusion on comparative figures remained modified for that earlier matter.
Which approvals were missing for the Advik deposits?
DWML did not obtain the Holding Company’s Audit Committee approval or prior shareholder approval for the material related-party ICDs to Advik, according to the auditor. The report says the deposits exceeded the 10% materiality threshold of annual consolidated turnover under Regulation 23(1), read with Schedule XII, of the Securities and Exchange Board of India Listing Regulations.
For a material related-party transaction, the auditor said Regulation 23(2) requires Audit Committee approval and Regulation 23(4) requires prior shareholder approval. The report explicitly says those approvals “were not obtained”, while providing neither DWML’s annual consolidated turnover nor the amount by which the Advik deposits exceeded the threshold.
ETPL management gave a broader account of its processes in a September 29, 2026 response to concerns from its previous statutory auditor. Management said all ICD transactions were undertaken under duly approved arrangements, recorded in the books and appropriately disclosed in financial statements. The qualified conclusion nonetheless identifies the absence of the specific Holding Company-level approvals required for these material transactions.
DWML’s statement on audit qualifications calls this the second occurrence of a qualification, arising from ETPL’s review report for the period ended June 30, 2026. The earlier audit report, dated May 28, 2026, was qualified over ICDs that ETPL had placed with Ebix Limited, making the Advik exposure a new issue alongside the earlier balance.
Got a follow-up? Ask IRIS
What did the auditor identify about Advik’s financial position?
The auditor said ETPL extended the Advik ICDs despite Advik having substantial outstanding statutory dues, a negative current asset-to-current liabilities ratio and negative net worth as at June 30, 2026. Advik was also named in Provisional Attachment Order No. 16/2026, dated June 5, 2026.
The filing does not state Advik’s statutory dues, current ratio or net-worth deficit. It therefore does not support a calculation of Advik’s repayment capacity or a quantified expected loss against the ₹44.869 crore June 30 balance. The auditor’s finding is instead that evidence was insufficient to assess the rationale, compliance and possible financial consequences of the ICDs.
The Provisional Attachment Order was issued by the Directorate of Enforcement’s Raipur Zonal Office under the Prevention of Money-laundering Act, 2002, or PMLA. It provisionally attached 74.86% of Ebix Limited’s investment in Ebix Inc., USA, amounting to ₹893.03 crore, as well as certain assets of persons named in the order.
The order also restricts alienation, sale, transfer, modification and the creation of liens or charges over Ebix Inc.’s assets and investments and those of its subsidiaries, including DWML and ETPL, to the stated ₹893.03 crore extent. The Enforcement Directorate’s complaint seeking confirmation of that attachment was pending before the PMLA Adjudicating Authority when DWML filed the June-quarter results.
What is DWML management’s position on the ICDs and attachment order?
DWML management said the ₹44.869 crore Advik ICD was recoverable and that no adjustment was required to the June 30, 2026 consolidated statement. Management also maintained that Group funds and transactions were not connected with alleged proceeds of crime that are the subject of the PMLA proceedings.
Management said the ₹2.656 crore Ebix Limited ICD receivable outstanding at June 30, 2026 was fully settled after the quarter-end. That subsequent settlement concerned the earlier Ebix Limited balance, rather than the ₹44.869 crore Advik balance that remained outstanding on the reporting date and formed part of the current qualification.
DWML management said neither DWML nor ETPL was independently named as an accused or subject to a separate attachment order. Based on its assessment of the June 5, 2026 order and available information, management did not foresee a material adverse effect on the Group’s financial position, carrying values, operations, going-concern status or ability to meet financial obligations.
ETPL’s previous statutory auditor, K G Somani & Co LLP, issued an intimation under Section 143(12) of the Companies Act on September 29, 2026. It raised concerns over the attachment order and the rationale for continuing inter-company fund movements, while ETPL disputed those concerns and denied wrongdoing by the company, its officers and employees.
Conclusion
DWML’s June 2026 results carry a qualified conclusion because the auditor could not assess the effect of ₹44.869 crore in Advik-related ICDs and said the required approvals for a material related-party transaction were not obtained. The matter sits alongside the prior qualification involving ₹2.656 crore of ETPL ICDs with Ebix Limited, although management says that older balance was settled after the reporting date.
The next disclosed developments to watch are the PMLA Adjudicating Authority’s handling of the Enforcement Directorate complaint over the June 5, 2026 attachment order involving ₹893.03 crore, and any further DWML disclosure on the Advik ICD’s rationale, compliance, recoverability or approvals. The source does not state a date for either an adjudication decision or further approvals.