










DEVX net debt rose to Rs 185 crore as H1 FY27 borrowings grew
Key highlights
- DEVX reported net debt of Rs 185 crore in H1 FY27, compared with Rs 89 crore in FY26.
- Gross debt reached Rs 222 crore in H1 FY27, including Rs 131 crore of long-term debt and Rs 91 crore of short-term debt.
- DEVX’s annualised net-debt-to-EBITDA ratio was 2.93x in Q2 FY27, versus 2.10x in FY26.
- DEVX disclosed a pipeline of 17 new centres covering approximately 2.81 million square feet.
powered by IRIS
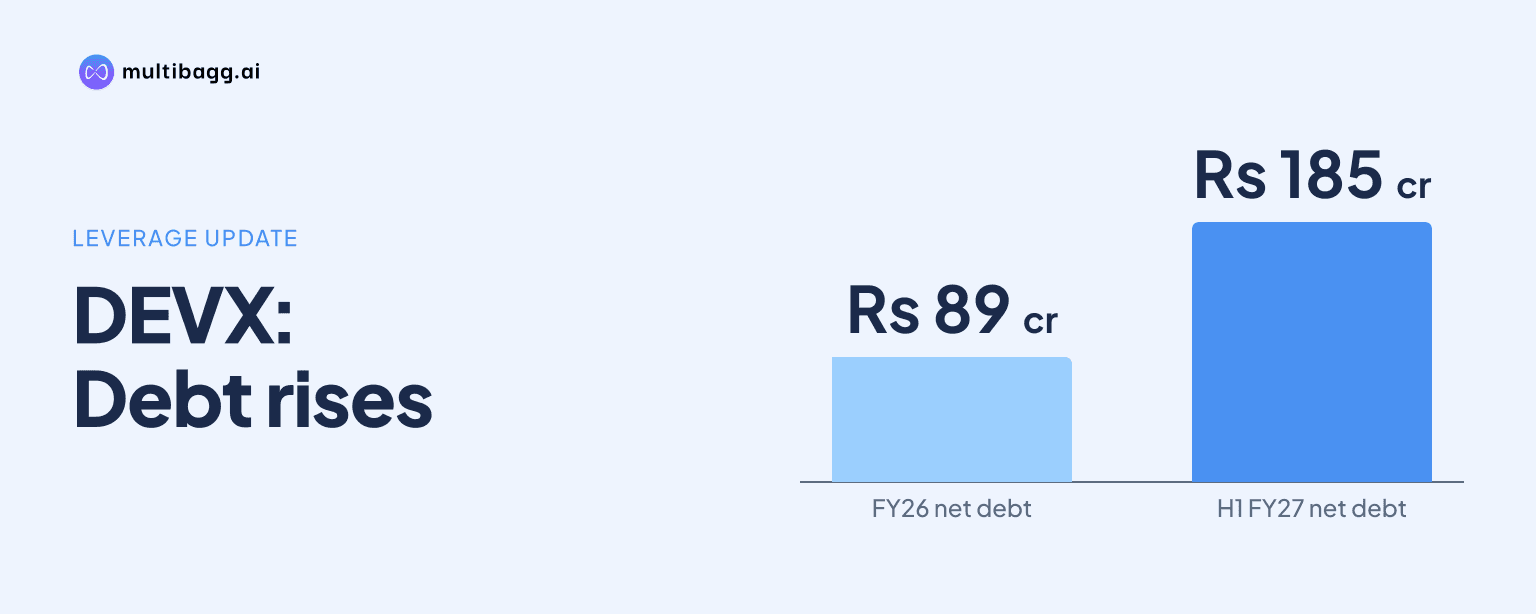
DEVX reported net debt of Rs 185 crore in H1 FY27, up from Rs 89 crore in FY26, after gross debt increased to Rs 222 crore from Rs 145 crore and cash declined to Rs 37 crore from Rs 55 crore. Its annualised net-debt-to-EBITDA ratio rose to 2.93x from 2.10x.
Know Dev Accelerator inside out
Results, valuation, peers and who's buying, in one view.
How did DEVX’s debt position change in H1 FY27?
DEVX’s reported net debt increased by Rs 96 crore between FY26 and H1 FY27, reversing the reduction from Rs 127 crore in FY25 to Rs 89 crore in FY26. Gross debt rose by Rs 77 crore between FY26 and H1 FY27, while cash and cash equivalents fell by Rs 18 crore, according to the consolidated capital-structure disclosure.
The higher borrowings were split between long-term and short-term debt. Long-term debt stood at Rs 131 crore in H1 FY27, compared with Rs 81 crore in FY26, while short-term debt rose to Rs 91 crore from Rs 64 crore. DEVX had reported gross debt of Rs 131 crore in FY25, consisting of Rs 99 crore of long-term debt and Rs 32 crore of short-term debt.
What funding did DEVX disclose for expansion and refinancing?
DEVX said Rs 100 crore raised through non-convertible debentures, or NCDs, supported refinancing and provided resources for expansion. The presentation does not provide a maturity schedule, interest cost, lender breakdown or a reconciliation of NCD proceeds to the Rs 222 crore gross-debt balance in H1 FY27.
The H1 FY27 debt increase came as DEVX operated 28 centres across 12 cities, covering 1.16 million square feet. The chairman said DEVX commenced operations as lessee of the JUPLA/EAPL property under an operating-company and property-company, or OpCo-PropCo, model, and initiated a tokenisation process to broaden funding options.
DEVX’s cash position also changed across the three disclosed periods. Cash and cash equivalents rose from Rs 3 crore in FY25 to Rs 55 crore in FY26, then declined to Rs 37 crore in H1 FY27. The difference between gross debt and reported net debt was therefore Rs 37 crore in H1 FY27, compared with Rs 55 crore in FY26.
How did DEVX’s leverage ratios move against earnings?
DEVX’s annualised net-debt-to-earnings before interest, tax, depreciation and amortisation, or EBITDA, ratio increased to 2.93x in Q2 FY27 from 2.10x in FY26 and 2.70x in FY25. The presentation labels these ratios as annualised and uses Indian Generally Accepted Accounting Principles, or IGAAP, for the EBITDA measure.
Debt relative to equity also increased from FY26 levels. Gross-debt-to-equity was 1.03x in Q2 FY27, against 0.78x in FY26, while net-debt-to-equity was 0.85x, compared with 0.48x. Both ratios remained below the FY25 figures of 2.39x for gross debt to equity and 2.32x for net debt to equity.
Return on capital employed, or ROCE, was 12.5% in H1 FY27, up from 9.9% in FY26 but below 17.1% in FY25. Return on equity, or ROE, was 7.0% in H1 FY27, compared with 7.4% in FY26 and 4.3% in FY25. DEVX also reported an ACUITE BBB rating with a stable outlook for long-term borrowings.
Got a follow-up? Ask IRIS
What operating growth accompanied DEVX’s higher leverage?
DEVX reported revenue of Rs 134 crore in H1 FY27 and Rs 80.2 crore in Q2 FY27. The chairman said Q2 FY27 revenue rose 54.8% year on year and profit after tax reached Rs 5.5 crore, more than tripling from the prior-year quarter, while H1 FY27 profit after tax was 3.7 times the corresponding previous period.
The operating portfolio had 17,412 seats in Q2 FY27, of which 15,872 were occupied, producing occupancy of 91.2%. This was higher than the 88.3% reported in Q2 FY26, although it was below the 91.9% recorded in Q1 FY27. Mature-centre occupancy rose to 81.0% in Q2 FY27 from 61.8% a year earlier.
Revenue-to-rent was 2.90x in Q2 FY27, compared with 2.40x in Q2 FY26 and 2.36x in Q1 FY27. DEVX identified managed space as its largest Q2 FY27 revenue segment at 51% of Rs 80.2 crore, followed by design and build at 29%; in H1 FY27, managed space represented 57% of Rs 134 crore.
What is DEVX planning as debt and capacity increase?
DEVX disclosed a pipeline of 17 new centres covering approximately 2.81 million square feet. Management said its priorities over coming quarters are to commission centres in phases, strengthen leasing and improve utilisation while growing its global capability centre, or GCC, services offering. The presentation does not state the capital spending required, timing by centre or a future debt target for this pipeline.
Management also said DEVX is developing payroll, talent sourcing and information-technology infrastructure services for small and mid-sized global companies establishing GCCs in India. Its development-management model is intended to work with landowners without investing in land acquisition or construction, while the OpCo-PropCo arrangement and tokenisation process are described as funding-structure initiatives.
Conclusion
DEVX entered H1 FY27 with Rs 185 crore of reported net debt, Rs 222 crore of gross debt and a 2.93x annualised net-debt-to-EBITDA ratio. Those measures increased from FY26 even as Q2 FY27 revenue reached Rs 80.2 crore, occupancy was 91.2%, and mature-centre occupancy and revenue-to-rent improved from the prior-year quarter.
The next disclosed operating test is delivery of the 17-centre, 2.81-million-square-foot pipeline in phases, alongside leasing and utilisation improvements. The effects of the Rs 100 crore NCD-supported expansion, the JUPLA/EAPL lease arrangement and the planned broader funding options on debt, cash and annualised leverage ratios remain matters to watch in coming quarters.