








Emrock CFO’s direct stake reaches 24.47% after conversion
Key highlights
- Parth Tulsibhai Patel converted 13.2 lakh warrants into Emrock equity shares on October 30, 2026.
- Patel’s direct Emrock holding became 52.16 lakh shares, or 24.47% of paid-up capital.
- The disclosed net purchase value for the 13.2 lakh shares was Rs 1.452 crore.
- Patel retained 17.94 lakh warrants or convertible securities, equal to 8.41% of paid-up capital.
powered by IRIS
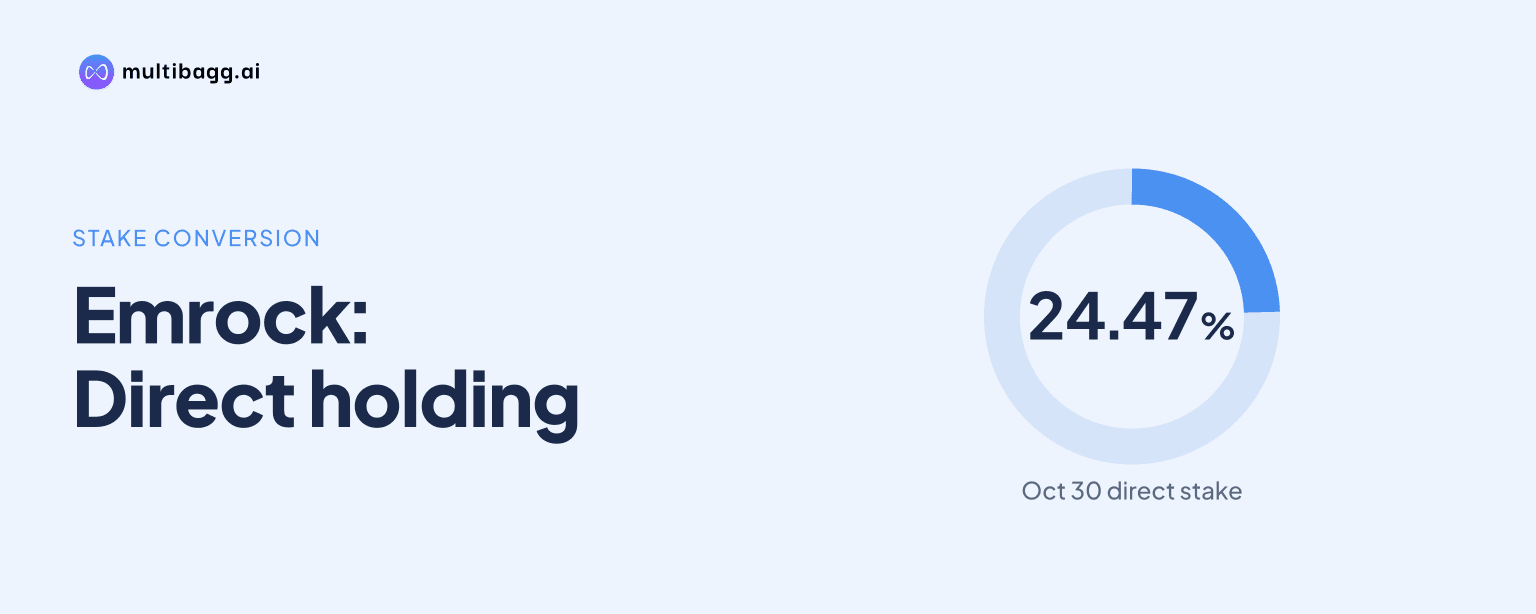
Emrock Corporation Limited’s Director and Chief Financial Officer, Parth Tulsibhai Patel, converted warrants into 13.2 lakh equity shares on October 30, 2026, resulting in a direct holding of 24.47% after the allotment. The purchase schedule reports a net purchase value of Rs 1.452 crore for the shares acquired.
Know Emrock Corporation inside out
Results, valuation, peers and who's buying, in one view.
How did Parth Patel’s direct stake in Emrock change?
Parth Patel’s direct Emrock holding rose by 13.2 lakh shares to 52.16 lakh shares after the October 30, 2026 warrant conversion. The post-acquisition direct holding represented 24.47% of Emrock’s paid-up share or voting capital, while the filing records the acquired shares as carrying voting rights.
Before the acquisition, Patel held 38.96 lakh voting shares, reported as 24.63% of then paid-up share capital. His direct share count therefore increased by 13.2 lakh shares, but the reported paid-up-capital percentage declined by 0.16 percentage points to 24.47% after the share base shown in the disclosure increased.
The October 31, 2026 disclosure identifies Patel as a director and CFO of Emrock and marks him as a member of its promoter or promoter group. It was filed under Regulation 29(2) of the Securities and Exchange Board of India, or SEBI, Substantial Acquisition of Shares and Takeovers Regulations, 2011.
What was the mechanism and value of Patel’s acquisition?
Patel acquired the 13.2 lakh shares through preferential allotment following conversion of warrants into equity shares, rather than through an open-market or off-market trade. The acquisition date and the date of receipt of allotment intimation were both stated as October 30, 2026.
The purchase-details schedule records a net purchase value of Rs 1.452 crore for the 13.2 lakh shares. Dividing the disclosed value by the disclosed share count gives Rs 110 per share, while the filing separately states that each equity share has a face value of Rs 10.
Emrock does not provide a separate conversion-price explanation, premium break-up, or salient conversion ratio for the acquired securities in this disclosure. Its table instead describes the salient features of the securities acquired as not applicable, consistent with the reported acquisition having already resulted in equity shares.
The filing records paid-up equity share capital of Rs 15.82 crore, divided into 158.20 lakh equity shares, before the acquisition. After the acquisition, it records paid-up equity share capital of Rs 21.32 crore, divided into 213.20 lakh equity shares, both based on equity shares with a Rs 10 face value.
How many Emrock warrants does Patel still hold?
Patel held 17.94 lakh warrants or convertible securities after the October 30 conversion, according to Emrock’s Regulation 29 disclosure. Those instruments represented 8.41% of post-acquisition paid-up share or voting capital and 6.24% of total diluted share or voting capital.
Before the transaction, the filing shows Patel with 31.14 lakh warrants or convertible securities, equal to 19.68% of then paid-up capital and 10.83% on a diluted basis. The number of warrant-linked instruments shown therefore declined by 13.2 lakh, matching the number of equity shares acquired through conversion.
The disclosure defines diluted share or voting capital as the total number of shares assuming full conversion of outstanding convertible securities and warrants into equity shares. Emrock reported total diluted share or voting capital after the acquisition at 2,87,55,491 equity shares, compared with 213.20 lakh paid-up equity shares immediately after the allotment.
The remaining 17.94 lakh instruments are distinct from Patel’s 52.16 lakh direct equity shares because the warrants or convertible securities were reported separately from shares carrying voting rights. The filing does not state a date by which the remaining instruments must be converted.
Got a follow-up? Ask IRIS
What is Patel’s total reported Emrock holding after conversion?
Patel’s combined reported Emrock position after the conversion was 70.10 lakh shares and warrant-linked instruments, or 32.88% of paid-up share or voting capital. On the fully diluted basis used in the filing, the combined position was 24.38%.
That combined total consists of 52.16 lakh direct equity shares and 17.94 lakh warrants or convertible securities. Patel’s direct shares alone represented 24.47% on the paid-up basis and 18.14% on the diluted basis, showing the effect of including all outstanding convertible securities and warrants in the denominator.
Before the conversion, Patel’s combined disclosed holding was also 70.10 lakh shares and warrant-linked instruments, based on 38.96 lakh shares and 31.14 lakh warrants. The transaction changed the composition of that total from warrant-linked instruments to direct equity shares, rather than increasing the combined number reported in the disclosure.
What changed in Emrock’s share capital after the disclosure?
Emrock’s disclosed paid-up equity share count was 213.20 lakh shares after the acquisition, compared with 158.20 lakh shares before it. The two reported capital figures differ by 55 lakh shares, and the corresponding stated paid-up equity capital rose by Rs 5.50 crore from Rs 15.82 crore to Rs 21.32 crore.
Patel’s conversion involved 13.2 lakh shares, or less than the 55 lakh-share difference between the before-and-after paid-up share counts in the filing. The disclosure identifies Patel’s mode of acquisition as preferential allotment by warrant conversion, but it does not reconcile the full 55 lakh-share change in paid-up capital within this document.
The post-acquisition diluted share count exceeded the disclosed paid-up count by 74.35 lakh shares, using 2,87,55,491 shares on a diluted basis and 213.20 lakh paid-up shares. This reflects the filing’s assumption of conversion of outstanding instruments and does not mean all those assumed shares had been issued as paid-up equity by October 30, 2026.
For Patel, the immediate result was 52.16 lakh direct equity shares and 17.94 lakh remaining warrant-linked instruments. Beyond the completed October 30 conversion, Emrock’s filing does not disclose a conversion timetable, further allotment plan, or the terms governing Patel’s remaining instruments.
Conclusion
The October 30, 2026 conversion moved 13.2 lakh instruments in Patel’s disclosed position into direct Emrock equity shares worth Rs 1.452 crore. His direct shareholding became 24.47%, while his total reported position, including 17.94 lakh warrants or convertible securities, stood at 32.88% on the paid-up-capital basis and 24.38% on the diluted basis.
The next ownership change to watch is any conversion of Patel’s remaining 17.94 lakh warrant-linked instruments, which were reported as 8.41% of paid-up capital. The filing does not specify their conversion timing or ratio, and it does not reconcile the entire 55 lakh-share increase between its pre- and post-acquisition paid-up share counts.