










Eureka Forbes H1 revenue rose 15.1% as gratuity lifted PAT
Key highlights
- Eureka Forbes standalone H1 FY27 revenue rose 15.1% to Rs 1,590.4 crore from Rs 1,381.2 crore in H1 FY26.
- Adjusted EBITDA increased 15.5% to Rs 194.6 crore, while the adjusted EBITDA margin remained 12.2%.
- PAT before exceptional items grew 14.1% to Rs 114.2 crore, compared with 28.6% growth in reported PAT to Rs 128.8 crore.
- The H1 FY27 result included a one-time Rs 19.5 crore pre-tax gain from reversal of gratuity expense.
powered by IRIS
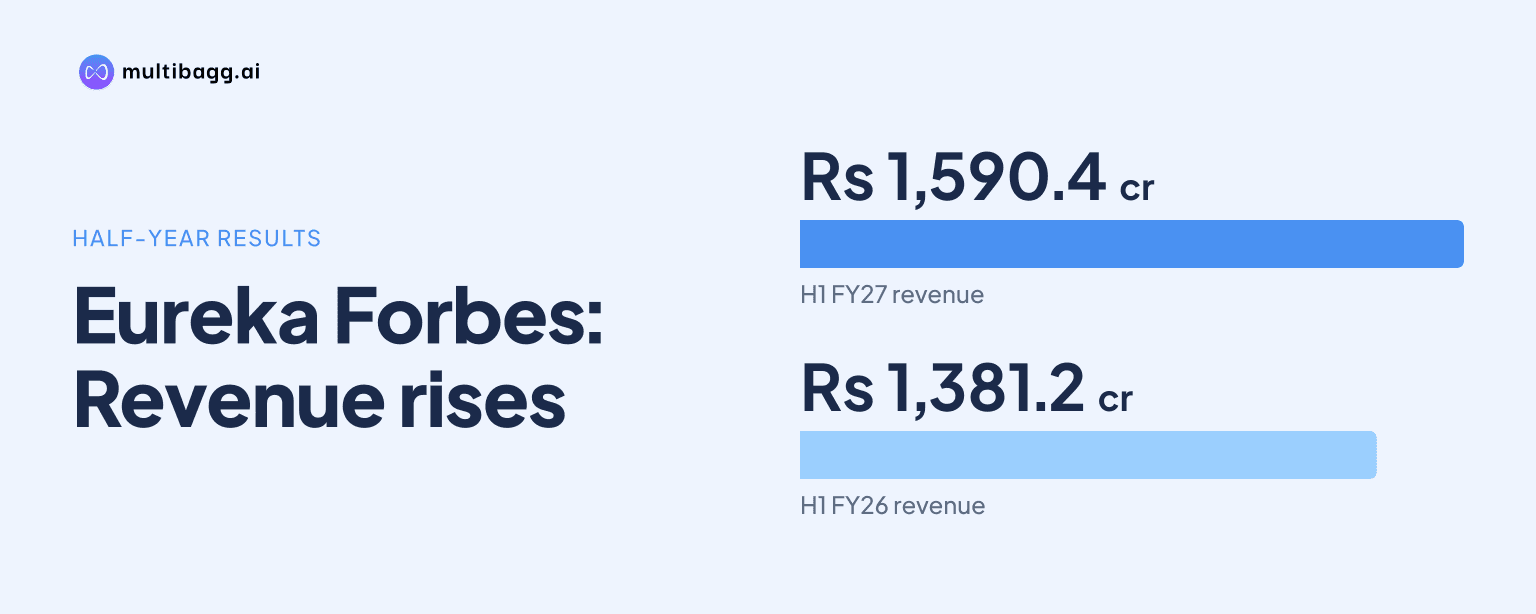
Eureka Forbes reported standalone H1 FY27 revenue growth of 15.1% to Rs 1,590.4 crore, accelerating from the 12.7% growth cited for H1 FY26. Reported profit after tax, or PAT, rose 28.6% to Rs 128.8 crore, but included a Rs 19.5 crore one-time pre-tax gain from reversal of gratuity expense; PAT before exceptional items increased 14.1%.
Know Eureka Forbes inside out
Results, valuation, peers and who's buying, in one view.
How fast did Eureka Forbes grow in H1 FY27?
Eureka Forbes increased H1 FY27 revenue by Rs 209.2 crore to Rs 1,590.4 crore from Rs 1,381.2 crore in H1 FY26. The 15.1% growth rate was 2.4 percentage points above the 12.7% H1 FY26 growth rate disclosed in the presentation.
Management said Q2 FY27 revenue increased 15.0% year on year and that growth was broad-based across channels and categories. The presentation attributes H1 FY27 growth to multiple growth engines, including the core water-purifier business and emerging categories, but does not provide revenue by category or channel.
The comparison shows that adjusted earnings before interest, tax, depreciation and amortisation, or adjusted EBITDA, grew 15.5%, broadly in line with revenue. Reported PAT rose faster at 28.6%, whereas the pre-exceptional PAT measure increased 14.1%, reflecting the effect of the Q1 FY27 gratuity reversal.
What drove Eureka Forbes revenue growth by category?
Eureka Forbes said its core water-purifier business grew at a high-teens rate year on year in H1 FY27, exceeding the 15.1% company revenue growth rate. Management attributed that increase to strong volume growth and price increases, and said the business achieved strong market-share gains without disclosing market-share figures.
In emerging categories, Eureka Forbes attributed robotics growth to premiumisation and water-softener growth to volume-led acceleration. The presentation identifies Forbes Robo Clean and Forbes Smart Clean in cleaning, Forbes Air Purifier in air purification, and Aquaguard products in water purification, but does not disclose H1 FY27 sales for those product lines.
Management described growth as broad-based across categories and channels in Q2 FY27, alongside 15.0% revenue growth for the quarter. The H1 presentation therefore identifies the mechanisms behind growth, including volumes, price increases and premiumisation, but does not quantify each contributor to the Rs 209.2 crore revenue increase.
How did Eureka Forbes costs and margins change?
Eureka Forbes reported adjusted EBITDA of Rs 194.6 crore in H1 FY27, up 15.5% from Rs 168.5 crore in H1 FY26. Its adjusted EBITDA margin was 12.2% in both periods, with the detailed table showing a 4-basis-point increase despite the inflationary headwinds cited by management.
Total expenses increased 11.7% to Rs 705.2 crore, slower than the 15.1% rise in revenue. Consequently, total expenses as a proportion of revenue fell to 44.3% from 45.7%, a 138-basis-point reduction that the presentation linked to operating leverage.
Employee benefit expenses rose 12.2% to Rs 181.0 crore, service charges increased 7.8% to Rs 179.1 crore, and other expenses grew 13.5% to Rs 345.1 crore. After a Rs 13.2 crore employee stock option plan, or ESOP, charge, EBITDA was Rs 181.4 crore, up 15.4% from Rs 157.1 crore.
Finance cost was broadly unchanged at Rs 3.2 crore in H1 FY27, while depreciation rose 21.3% to Rs 20.9 crore and amortisation increased 19.1% to Rs 17.6 crore. These charges meant EBITDA margin remained 11.4% in both H1 FY27 and H1 FY26, with a 3-basis-point increase in the detailed statement.
Got a follow-up? Ask IRIS
Why did Eureka Forbes reported PAT rise faster than underlying profit?
Eureka Forbes reported PAT of Rs 128.8 crore in H1 FY27, up 28.6% from Rs 100.1 crore in H1 FY26, because the result included an exceptional item. The presentation states that Q1 FY27 reported PAT included a one-time pre-tax gain of Rs 19.5 crore from reversal of gratuity expense.
PAT before exceptional items was Rs 114.2 crore, up 14.1% from Rs 100.1 crore. This disclosed pre-exceptional growth rate was closer to the 15.1% revenue increase than the 28.6% rise in reported PAT.
Profit before tax, or PBT, increased 27.9% to Rs 172.5 crore from Rs 134.9 crore. Adjusted PBT, which Eureka Forbes defines as PBT excluding exceptional items and ESOP charges, rose 13.6% to Rs 166.2 crore from Rs 146.2 crore; the presentation does not disclose a separate tax effect for the Rs 19.5 crore gain.
Reported PAT margin was 8.1% in H1 FY27, according to the key-highlights page. The difference between reported PAT of Rs 128.8 crore and PAT before exceptional items of Rs 114.2 crore was Rs 14.6 crore after tax, while the disclosed exceptional gain was Rs 19.5 crore on a pre-tax basis.
What is Eureka Forbes management expecting after H1 FY27?
Eureka Forbes management said the H1 FY27 outcome strengthened its confidence in delivering a meaningful step-up in growth in FY27. This was management’s stated outlook, not numerical guidance, because the presentation provides no full-year revenue, profit or margin target.
Management cited momentum across the core business, emerging categories and channels after revenue grew 15.1% in H1 FY27 and adjusted EBITDA margin remained 12.2%. It said it remained focused on sustainable profitable growth through execution discipline while managing the inflationary pressures described in the presentation.
The H1 FY27 highlights also list net surplus of Rs 304 crore. The presentation identifies continued high-teens water-purifier growth, premiumisation in robotics and volume-led water-softener growth as operating trends, but does not specify future category revenue or market-share targets.
Conclusion
Eureka Forbes accelerated revenue growth from 12.7% in H1 FY26 to 15.1% in H1 FY27, while adjusted EBITDA increased 15.5% to Rs 194.6 crore and its 12.2% margin remained broadly unchanged. The 28.6% increase in reported PAT included a Rs 19.5 crore pre-tax gratuity-expense reversal, leaving the disclosed PAT-before-exceptional-items growth rate at 14.1%.
The next reported test is management’s stated aim of a meaningful FY27 growth step-up while maintaining profitable growth amid inflationary pressures. Readers can watch whether water purifiers retain high-teens growth and whether robotics premiumisation and volume-led water-softener growth continue, as Eureka Forbes has not disclosed full-year numerical targets or category-level revenue figures.