










Fidel Softech revenue climbs 90% while PAT rises 5.83%
Key highlights
- Fidel Softech’s first-half FY 2026-27 revenue rose 90% to Rs 75.91 crore, while PAT increased 5.83% to Rs 6.78 crore.
- US and Asia-Pacific operations contributed 88% of first-half revenue and operated at single-digit PAT margins during their scale-up phase.
- Q2 FY 2026-27 revenue was Rs 37.97 crore, up 64.05% year over year but only 0.12% sequentially.
- Fidel added six Japanese clients in Q2 and reported a Japan team of more than 150 members following its acquisitions.
powered by IRIS
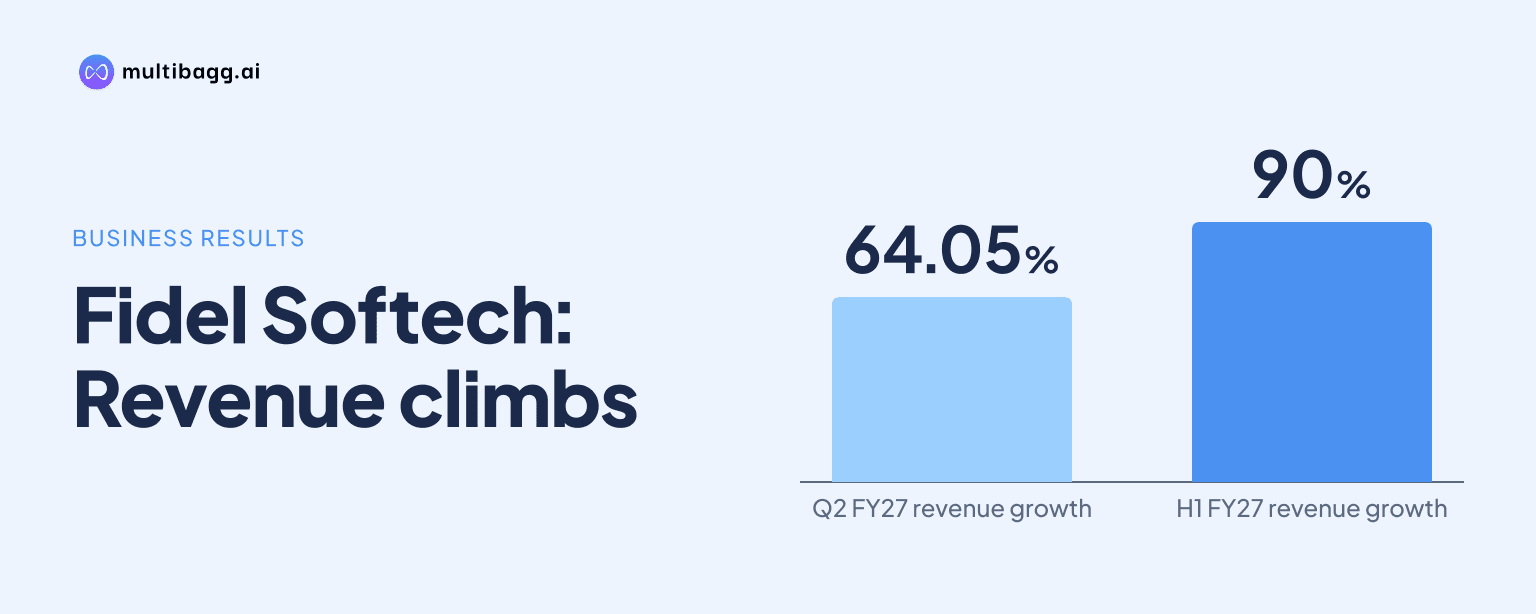
Fidel Softech reported consolidated first-half FY 2026-27 revenue of Rs 75.91 crore, a stated 90% increase from Rs 39.78 crore a year earlier, while profit after tax rose 5.83% to Rs 6.78 crore. Fidel said 88% of revenue came from US and Asia-Pacific markets operating at single-digit PAT margins during their scale-up phase.
Know Fidel Softech inside out
Results, valuation, peers and who's buying, in one view.
Why did Fidel's first-half revenue grow faster than profit?
Fidel's revenue grew faster than profit because its overseas operations were still in a scale-up phase with single-digit profit after tax, or PAT, margins. Consolidated revenue increased by Rs 36.13 crore to Rs 75.91 crore in the first half of FY 2026-27, whereas PAT increased by Rs 38 lakh from Rs 6.40 crore to Rs 6.78 crore.
Profit before tax, or PBT, rose 5.44% to Rs 8.89 crore from Rs 8.43 crore, also far below the 90% revenue increase. Fidel said high growth had brought slight margin moderation because of scaling and investments, and its quarterly-results commentary cited strategic investments and acquisitions as reasons for reduced profit margins.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 22.5% to Rs 10.64 crore in the detailed half-year comparison. A separate half-year table in the presentation lists EBITDA for FY 2026-27 as Rs 10.40 crore, so the source contains a Rs 24 lakh difference between its two disclosed EBITDA figures.
What did Fidel report for Q2 FY 2026-27?
Fidel reported consolidated Q2 FY 2026-27 revenue of Rs 37.97 crore, EBITDA of Rs 5.61 crore, PBT of Rs 4.62 crore and PAT of Rs 3.60 crore. Revenue rose 64.05% from Rs 23.15 crore in Q2 FY 2025-26, but was only 0.12% above Rs 37.93 crore in Q1 FY 2026-27.
Profit increased sequentially despite the near-flat revenue line. EBITDA rose from Rs 5.02 crore in Q1 FY 2026-27 to Rs 5.61 crore in Q2, while PBT increased from Rs 4.27 crore to Rs 4.62 crore and PAT moved from Rs 3.17 crore to Rs 3.60 crore.
The Q2 revenue base was also broadly retained from the preceding quarter. Fidel recorded Rs 37.27 crore in Q4 FY 2025-26, Rs 37.93 crore in Q1 FY 2026-27 and Rs 37.97 crore in Q2 FY 2026-27, compared with Rs 25.29 crore in Q3 FY 2025-26.
Fidel added six Japanese clients in Q2, initiated an offshore project through Techvine US and connected machine data to the cloud for a manufacturing firm through its hi-tech solution. The presentation does not disclose the revenue, contract value or profit contribution of these individual operating developments.
Got a follow-up? Ask IRIS
Which markets and services account for Fidel's activity?
Fidel reported Asia Pacific, including India, as 73% of geographical performance, followed by the United States at 16% and Europe and the Middle East at 11%. It separately said the United States and Asia-Pacific together represented 88% of first-half revenue, while the geographic chart totals 89% for those regions because of the stated 73% and 16% shares.
IT consulting represented 80% of division-based performance and localization accounted for 20%. Fidel said IT Consulting & Services continued to stabilise and grow, while multilingual data engineering, over-the-top, or OTT, subtitling and software localization showed growth alongside its language-localization work.
Japan is the operating mechanism Fidel presents for cross-border delivery. Its Japan platform combines local relationships, bilingual project management and project management office capability, managed operations and enterprise access with India and global engineering scale, artificial intelligence and data talent, localization and post-delivery support.
Fidel said its Japan acquisitions had built a team of more than 150 members in Japan. The company said integration could convert that presence into wallet share through IT, managed IT operations, cybersecurity, enterprise solutions, localization, bilingual staffing, AI and data, and hi-tech services for electronics and smart manufacturing.
What is Fidel's stated margin and growth outlook?
Fidel expects a similar revenue mix next year and says margins have potential to improve as overseas scale matures. Management did not provide a target PAT margin, a timing for improvement or a separate forecast for the US and Asia-Pacific businesses that generated 88% of first-half revenue.
Management said it would focus on quality margins after describing consolidation from strategic investments and acquisitions. Its capital-allocation material says Japanese-yen borrowings carry rates of 2% to 3.5%, have five-to-eight-year tenures and are naturally hedged through Japan revenue; the company says they are used primarily as a strategic growth enabler for acquisitions.
Fidel also reported 0% equity dilution so far and said it had positive cash flow and adequate liquidity for operations, growth and macro stability. These statements sit alongside the company's plan to use acquisitions and its Japan revenue base as part of its expansion mechanism.
The presentation states an ambition to reach Rs 500 crore in five years, described as five times growth in five years, after scaling from about Rs 25 crore to Rs 102 crore. Fidel characterises the ambition as profitable growth with disciplined capital allocation, but does not disclose annual revenue milestones, acquisition spending or a date-specific margin target.
Conclusion
Fidel's first-half FY 2026-27 figures show substantial sales expansion without proportional PAT growth: revenue increased 90% to Rs 75.91 crore, while PAT increased 5.83% to Rs 6.78 crore. The presentation links that gap to the scale-up of US and Asia-Pacific operations, which accounted for 88% of revenue and were operating at single-digit PAT margins, while IT consulting represented 80% of division-based activity.
The next results will show whether the similar overseas mix management expects next year begins to deliver the margin improvement it says may follow from mature scale. Progress on the Rs 500 crore five-year ambition, integration of the more-than-150-member Japan team and the contribution from six Japanese clients added in Q2 FY 2026-27 are the disclosed developments to watch.