










Focus Lighting retains Rs 1.76 crore aged receivable unprovided
Key highlights
- Focus Lighting had a Rs 1.76 crore government-entity receivable outstanding for more than two years at September 30, 2026.
- Focus Lighting reported Rs 3.30 crore due from a subsidiary and Rs 1.05 crore due from a related party, including accrued interest.
- Focus Lighting recorded no impairment or expected-credit-loss provision on the Rs 4.35 crore combined subsidiary and related-party balances.
- Focus Lighting’s standalone six-month profit after tax increased to Rs 4.99 crore from Rs 3.16 crore.
powered by IRIS
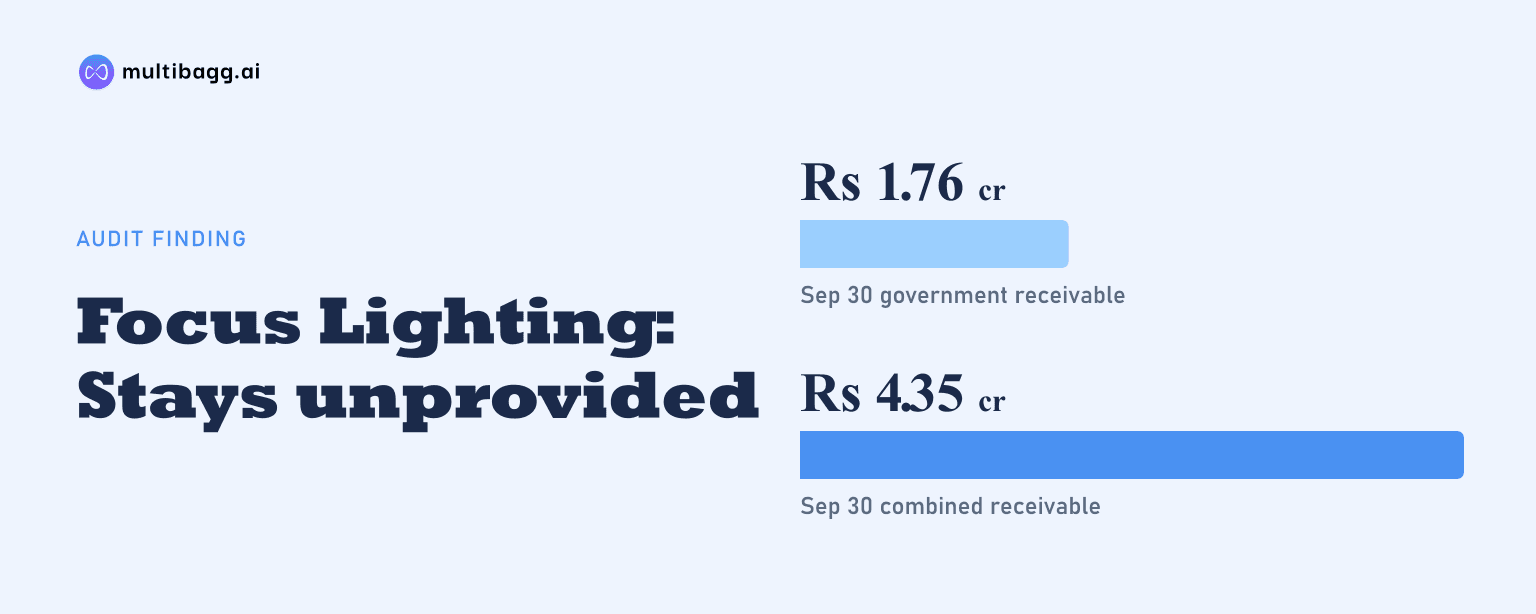
Focus Lighting and Fixtures Limited (Focus Lighting) retained a Rs 1.76 crore trade receivable from a government entity without provision at September 30, 2026, although it had been outstanding for more than two years. The limited-review report also highlighted Rs 4.35 crore of outstanding loans and advances to a subsidiary and related party without impairment provision.
Know Focus Lighting & Fixtures inside out
Results, valuation, peers and who's buying, in one view.
Why did Focus Lighting leave the government receivable unprovided?
Focus Lighting said the Rs 1.76 crore trade receivable due from a government entity was fully recoverable at September 30, 2026 and therefore needed no provision. The balance had remained outstanding for more than two years, but management cited the nature of the counterparty and past experience that collections from government entities are generally subject to extended realisation.
N. A. Shah Associates LLP drew attention to the aged government balance in its limited-review report on the standalone results for the quarter and half year ended September 30, 2026. The auditor stated that it relied on management’s assessment of recoverability and past collection experience when considering the Rs 1.76 crore amount.
The aged government balance is separate from the broader receivables categories in the standalone balance sheet. Current trade receivables declined to Rs 31.69 crore at September 30, 2026 from Rs 39.06 crore at March 31, 2026, while non-current trade receivables increased to Rs 6.75 crore from Rs 4.04 crore.
What funding balances did Focus Lighting’s auditor highlight?
Focus Lighting had a Rs 3.30 crore loan and advance outstanding to a subsidiary and Rs 1.05 crore outstanding to a related party at September 30, 2026, both including accrued interest. The Rs 4.35 crore combined balance was identified in the standalone auditor’s emphasis-of-matter disclosure as having been granted in the normal course of business.
Management considered the subsidiary and related-party amounts fully recoverable based on their business plans, prospects and current financial positions. Focus Lighting consequently had not made a provision for impairment or expected credit loss, the accounting assessment of potential non-collection, on either the Rs 3.30 crore subsidiary amount or the Rs 1.05 crore related-party amount.
The standalone cash-flow statement recorded Rs 1.64 crore of loans given to a subsidiary during the six months ended September 30, 2026, compared with Rs 34.89 lakh in the corresponding six months of 2025. That cash-flow movement is distinct from the Rs 3.30 crore period-end loan and advance balance, which includes accrued interest.
Did the auditor modify its conclusion on Focus Lighting’s results?
No, N. A. Shah Associates LLP did not modify its limited-review conclusion on Focus Lighting’s standalone financial results for the quarter and half year ended September 30, 2026. The auditor said nothing had come to its attention that caused it to believe the results were not prepared in accordance with applicable Indian Accounting Standards, or that they contained a material misstatement.
The report was a limited review rather than a full audit. Under Standard on Review Engagements 2410, the auditor said its procedures consisted primarily of inquiries of company personnel and analytical procedures, providing less assurance than an audit and not resulting in an audit opinion.
The emphasis-of-matter disclosure covered the Rs 1.76 crore aged government receivable and the Rs 4.35 crore of subsidiary and related-party balances. The auditor explicitly said its conclusion was not modified in respect of the subsidiary and related-party funding matter, while the report’s overall conclusion on the standalone results remained unmodified.
Got a follow-up? Ask IRIS
What changed in Focus Lighting’s assets and cash position?
Focus Lighting’s standalone total assets increased to Rs 201.82 crore at September 30, 2026 from Rs 186.89 crore at March 31, 2026. Property, plant and equipment rose to Rs 60.17 crore from Rs 36.72 crore, whereas capital work-in-progress fell to Rs 9.40 crore from Rs 31.51 crore over the same six-month period.
Cash and cash equivalents stood at Rs 1.18 crore at September 30, 2026, compared with Rs 66.02 lakh at March 31, 2026. For the six months ended September 30, 2026, Focus Lighting reported Rs 8.92 crore of net cash generated from operating activities, Rs 8.18 crore used in investing activities and Rs 21.59 lakh used in financing activities.
Non-current loans within standalone financial assets rose to Rs 4.40 crore at September 30, 2026 from Rs 3.77 crore at March 31, 2026. Current loans moved in the other direction, declining to Rs 38.62 lakh from Rs 69.32 lakh, indicating that the reported increase in loan assets was within the non-current category.
How did Focus Lighting’s half-year results compare with last year?
Focus Lighting reported standalone revenue from operations of Rs 101.72 crore for the six months ended September 30, 2026, compared with Rs 85.88 crore in the corresponding 2025 period. Profit after tax increased to Rs 4.99 crore from Rs 3.16 crore, while basic earnings per share rose to Rs 0.75 from Rs 0.47.
Finance costs increased to Rs 1.21 crore in the 2026 half year from Rs 31 lakh a year earlier. Employee-benefit expense increased to Rs 15.11 crore from Rs 12.80 crore, and depreciation and amortisation rose to Rs 5.75 crore from Rs 4.50 crore.
Profit before tax was Rs 6.69 crore for the six months ended September 30, 2026, against Rs 4.21 crore in the comparable 2025 period. Focus Lighting describes direct and contract manufacturing as its sole reportable segment, so the filing does not allocate revenue, profit or receivables between products, geographies, the government counterparty or the funding recipients.
Conclusion
Focus Lighting’s September 2026 filing centres on management’s recoverability judgements for three identified balances: the Rs 1.76 crore government receivable overdue by more than two years, the Rs 3.30 crore subsidiary loan and advance, and the Rs 1.05 crore related-party balance. Auditors highlighted these matters without modifying their limited-review conclusion, while standalone half-year revenue and profit after tax increased year on year.
The next disclosures to watch are any reported collection of the aged government receivable, repayment of the subsidiary or related-party balances, or a revised impairment assessment. Focus Lighting also said state rules under the four Labour Codes had not yet been notified and that it would give an appropriate accounting effect as further developments arise, without disclosing a date or amount.