










Galaxy Medicare H1 FY27 Profit Falls 24.4% to ₹1.53 Crore
Key highlights
- Galaxy Medicare reported H1 FY27 revenue from operations of ₹20.19 crore, up 7.8% year on year.
- Galaxy Medicare’s H1 FY27 net profit was ₹1.53 crore, down 24.4% from ₹2.02 crore.
- Galaxy Medicare’s operating margin was 10.4% in H1 FY27 versus 14.7% in H1 FY26.
- The limited review highlighted a ₹50 lakh unadjusted advance to the IPO book running lead manager.
powered by IRIS
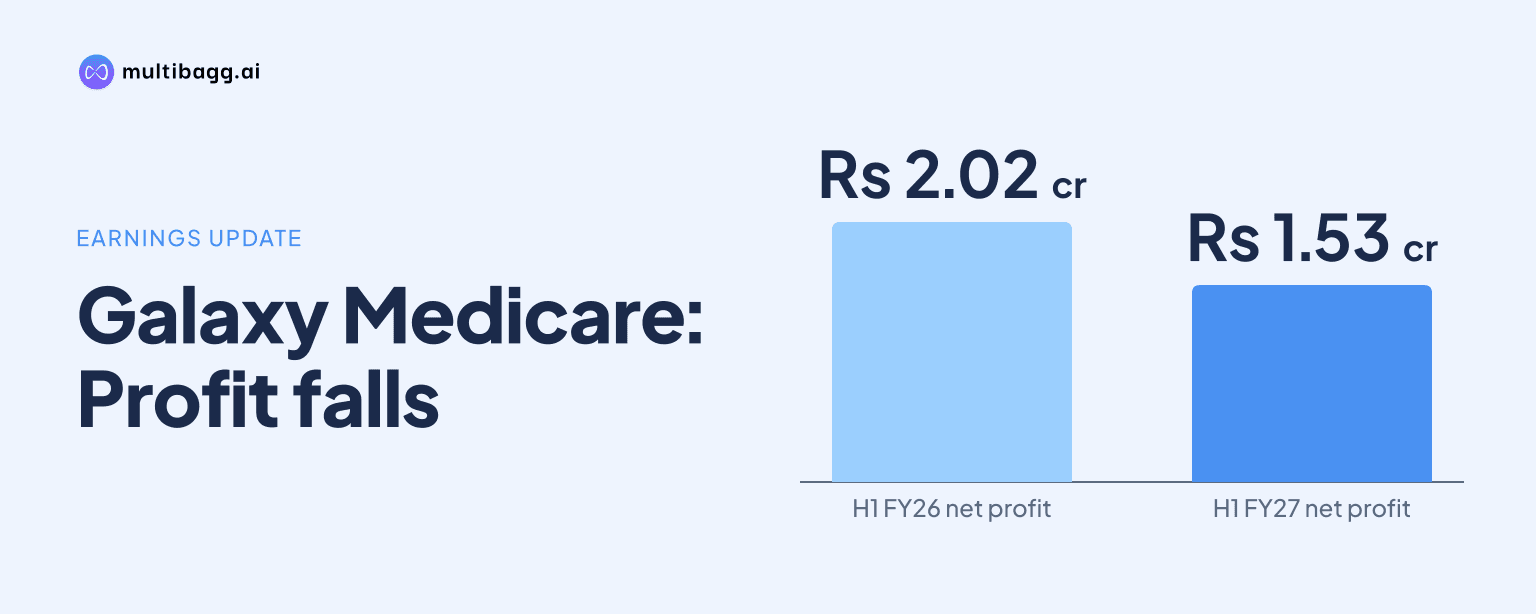
Galaxy Medicare Limited reported standalone H1 FY27 net profit of ₹1.53 crore, down 24.4% from ₹2.02 crore a year earlier, despite revenue from operations rising 7.8% to ₹20.19 crore for the half-year ended September 30, 2026. The result shows that revenue growth did not translate into higher profit during the period.
Know Galaxy Medicare inside out
Results, valuation, peers and who's buying, in one view.
What did Galaxy Medicare report for H1 FY27?
Galaxy Medicare reported revenue from operations of ₹20.19 crore in H1 FY27, compared with ₹18.73 crore in H1 FY26. Total income rose to ₹21.19 crore from ₹19.06 crore, supported by other income of ₹1.00 crore, compared with ₹0.33 crore in the corresponding previous period.
Profit before tax stood at ₹2.21 crore, lower than ₹2.81 crore in H1 FY26. Profit after tax was ₹1.53 crore against ₹2.02 crore a year earlier. Basic earnings per share for the half-year was ₹1.01. The company disclosed these figures in its standalone unaudited financial results for the half-year ended September 30, 2026.
The revenue increase was modest in relation to the decline in profitability. Revenue grew by about ₹1.46 crore year on year, while net profit declined by roughly ₹0.49 crore. This resulted in a lower profit conversion from the company’s operating activity during the reported period.
How did the H1 FY27 result compare with the preceding half-year?
Galaxy Medicare’s H1 FY27 revenue was lower than the ₹21.34 crore reported in H2 FY26, while net profit was also below the ₹1.63 crore recorded in the preceding half-year. Total income was ₹21.19 crore in H1 FY27, compared with ₹22.34 crore in H2 FY26.
The company’s operating margin was 10.4% in H1 FY27, compared with 9.4% in H2 FY26 and 14.7% in H1 FY26. This indicates an improvement from the immediately preceding half-year but a marked reduction from the comparable period a year earlier. Operating profit, which excludes other income, was reported to be 52.0% lower year on year.
Profit before exceptional items and tax was ₹2.21 crore in H1 FY27, against ₹1.94 crore in H2 FY26 and ₹2.81 crore in H1 FY26. Profit before tax was also ₹2.21 crore, as against ₹2.12 crore in H2 FY26. The difference between the pre-exceptional and reported pre-tax figures in H2 FY26 reflects the figures presented in the company’s results summary.
What did the auditor flag in Galaxy Medicare’s review?
Galaxy Medicare’s limited review report included an emphasis of matter relating to a ₹50 lakh advance paid to the book running lead manager for its initial public offering. The amount remains unadjusted and has been classified under short-term loans and advances in the financial statements.
An emphasis of matter draws attention to an item already disclosed in the financial statements. The reported review observation does not change the H1 FY27 revenue or profit figures, but it identifies a balance-sheet item that investors may monitor alongside the company’s disclosures on the use of IPO proceeds.
Galaxy Medicare also submitted a statement on deviation or utilisation of IPO proceeds with its H1 FY27 results. The fresh issue size in the IPO was ₹17.86 crore. The available information does not state a revised adjustment schedule for the ₹50 lakh advance, so no conclusion on its eventual treatment can be drawn from the disclosed data.
Got a follow-up? Ask IRIS
What is the financial background to the latest result?
Galaxy Medicare operates in surgical dressings and casting consumables. In FY26, it reported revenue of ₹40.00 crore, up 2.0% from FY25. EBITDA declined 6.5% to ₹4.30 crore, and EBITDA margin moderated to 10.8% from the prior year’s level.
The company reported FY26 profit of ₹3.42 crore, compared with ₹3.37 crore in FY25 and ₹3.71 crore in FY24. The H1 FY27 result therefore extends the pattern of pressure on profitability, with the half-year profit of ₹1.53 crore below the comparable H1 FY26 figure.
Product concentration is an important operating context. POP Bandage and Elastic Adhesive Bandage accounted for 87% of FY26 revenue. The company’s reported FY26 capacity utilisation was 106% for POP Bandage and 91% for Elastic Adhesive Bandage, figures cited in support of its capacity-expansion rationale.
How does the result matter for investors and operations?
Galaxy Medicare’s latest numbers show that sales expanded while net profit and operating profit declined from the year-earlier period. For investors, the main reported indicators are the 7.8% revenue increase, the 24.4% fall in profit after tax, and the reduction in operating margin to 10.4% from 14.7% in H1 FY26.
The company’s business also has geographical and product concentration. Bangladesh accounted for about 83% of FY26 export sales, while POP Bandage and Elastic Adhesive Bandage remained the dominant products. These disclosed concentrations provide context for assessing the company’s operating performance, although the H1 FY27 filing does not quantify product-wise or country-wise sales for the half-year.
Galaxy Medicare informed the exchange that its board would meet on November 14, 2026, to consider the unaudited financial results for the half-year ended September 2026. Earlier, the board met on May 29, 2026, to consider the audited annual results for the year ended March 2026 and dividend matters. The H1 FY27 results were reported on November 14, 2026.
Conclusion
Galaxy Medicare delivered higher H1 FY27 revenue but lower profitability, with revenue from operations at ₹20.19 crore and net profit at ₹1.53 crore. The result is also notable for the lower year-on-year operating margin and the limited review emphasis of matter on the unadjusted ₹50 lakh IPO-related advance.
Investors can watch subsequent disclosures on the utilisation of the ₹17.86 crore fresh IPO proceeds, the status of the ₹50 lakh advance, and whether revenue growth is accompanied by a recovery in operating margin and net profit. The company’s disclosed capacity-expansion rationale and concentration in key products and export markets remain relevant operational factors.