










Generic Engineering auditor repeats WIP valuation qualification
Key highlights
- Generic Engineering’s auditor repeated a qualified conclusion for the September 30, 2026 standalone results.
- Total inventory was Rs 77.88 crore at September 30, 2026, but the filing did not separately disclose the WIP balance.
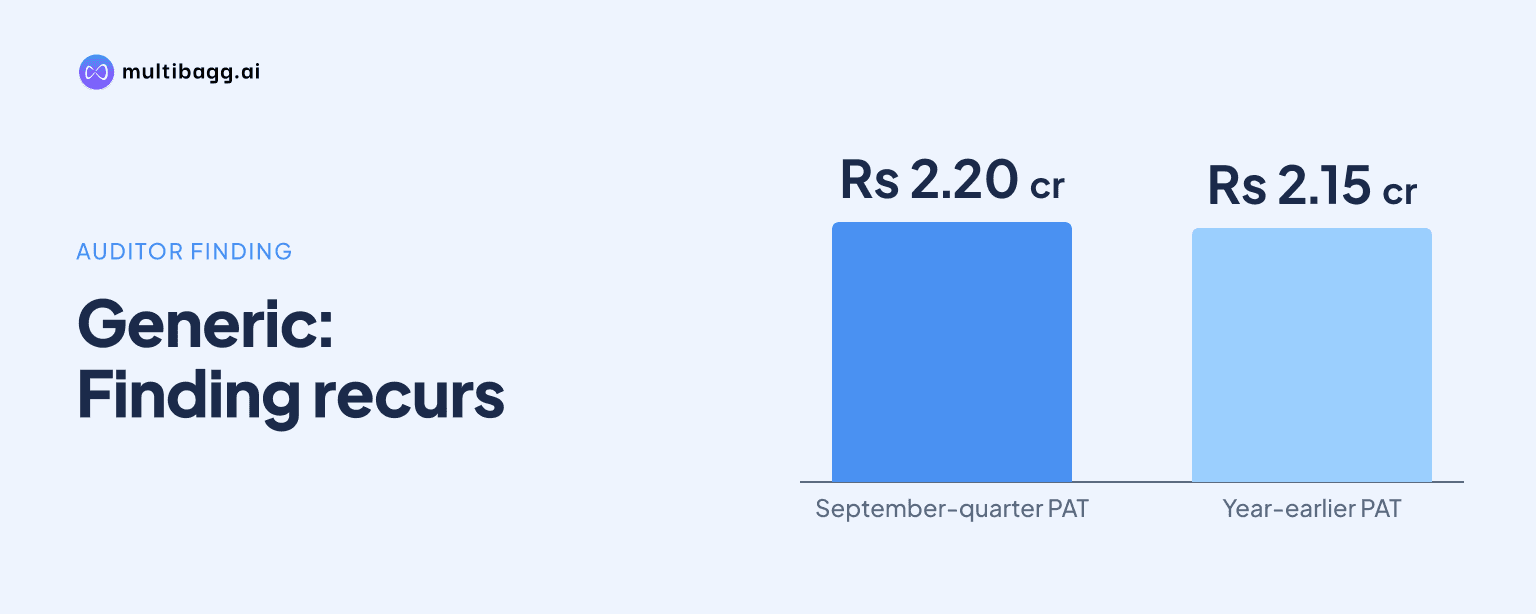
- Standalone September-quarter profit after tax was Rs 2.20 crore, compared with Rs 2.15 crore a year earlier.
- Management estimated nil impact and said it expects WIP to be realised into revenue within one year.
powered by IRIS
Generic Engineering Construction and Projects Limited received a repeated qualified conclusion on its September 30, 2026 standalone results because the auditor could not verify costs accumulated in work-in-progress within total inventory of Rs 77.88 crore. The auditor said any required valuation write-down or obsolescence provision, and its financial effect, remain unascertainable.
Know Generic Engineering Construction & Projects inside out
Results, valuation, peers and who's buying, in one view.
Why did Generic Engineering receive a repeated qualification?
Generic Engineering received the repeated qualification because it did not provide sufficient and appropriate evidence supporting the costs accumulated in work-in-progress, or WIP, for ongoing construction and project contracts as at September 30, 2026. Statutory auditor Bilimoria Mehta & Co. said management had furnished engineering completion certificates that evidenced the WIP’s existence, but had not supplied cost records, cost-allocation details or the basis used to calculate accumulated costs.
The company’s November 14, 2026 statement on audit-qualification impact identifies the frequency of the qualification as “repeated.” The auditor issued a qualified conclusion in its limited review of the standalone quarter and six months ended September 30, 2026. A limited review conducted under Standard on Review Engagements 2410 provides moderate assurance and is less extensive than an audit, according to the auditor’s report.
The same WIP matter also appears in the auditor’s qualified conclusion on the consolidated financial results for the September 2026 quarter and six-month period. The consolidated report describes the inventory as belonging to the holding company and repeats that the auditor cannot assess whether the WIP is correctly valued. Its conclusion was not modified for the group’s share of loss from an unaudited joint venture, which was Rs 0.03 lakh for the quarter.
What financial effect could the WIP issue have?
The auditor said it could not determine whether Generic Engineering’s WIP required a write-down to net realisable value, or NRV, or a provision for obsolescence. Because the company did not provide the cost evidence sought, the auditor also could not determine the consequential impact, if any, on standalone results for the quarter and six months ended September 30, 2026.
The filing does not separately state the rupee value of WIP within the Rs 77.88 crore inventory balance at September 30, 2026. Total inventory was slightly lower than Rs 78.29 crore at March 31, 2026. Management’s engineering completion certificates therefore supported physical existence, but the auditor’s concern is specifically whether the costs capitalised in the WIP balance support its reported valuation.
Generic Engineering’s qualification-impact statement shows no difference between the reported and adjusted figures because the potential impact was not quantified. The statement labels its Rs 2.21 crore figure as net profit, although it matches the profit-before-tax figure in the standalone profit and loss account. Management estimated the financial impact at nil, while the auditor said the evidence available did not allow it to independently assess that estimate.
How did Generic Engineering's reported results change?
Generic Engineering reported revenue from operations of Rs 62.96 crore for the quarter ended September 30, 2026, compared with Rs 61.59 crore in the corresponding quarter of 2025. Profit before tax declined to Rs 2.21 crore from Rs 2.63 crore, while profit after tax rose to Rs 2.20 crore from Rs 2.15 crore. These reported results remain subject to the auditor’s unquantified WIP valuation qualification.
For the six months ended September 30, 2026, revenue from operations increased to Rs 115.05 crore from Rs 113.55 crore a year earlier. Profit before tax fell to Rs 4.61 crore from Rs 6.10 crore, whereas profit after tax increased to Rs 4.23 crore from Rs 4.16 crore. Finance costs declined to Rs 4.77 crore from Rs 6.32 crore over the same six-month comparison.
The balance sheet showed total assets of Rs 530.79 crore at September 30, 2026, compared with Rs 518.02 crore at March 31, 2026. Trade receivables rose to Rs 219.74 crore from Rs 197.85 crore, while cash and cash equivalents declined to Rs 1.48 crore from Rs 4.33 crore. Current borrowings increased to Rs 74.60 crore from Rs 57.08 crore, and non-current borrowings rose to Rs 9.18 crore from Rs 0.32 crore.
Got a follow-up? Ask IRIS
Which business segments and cash flows changed most?
Generic Engineering’s Construction to Services segment generated revenue of Rs 51.53 crore in the September 2026 quarter, up from Rs 32.82 crore a year earlier. Trading Material revenue fell to Rs 1.20 crore from Rs 28.77 crore. The segment statement reported total segment revenue of Rs 52.73 crore, below the Rs 62.96 crore revenue from operations in the standalone profit and loss account; the filing does not explain the difference.
Construction to Services recorded segment profit before interest and tax of Rs 4.25 crore in the September 2026 quarter, down from Rs 6.19 crore in the year-earlier quarter. Trading Material segment profit declined to Rs 0.02 crore from Rs 0.67 crore. Construction to Services assets were Rs 529 crore at September 30, 2026, compared with Rs 1.79 crore of Trading Material assets.
Net cash flow from operating activities was an outflow of Rs 21.93 crore for the period ended September 30, 2026, compared with an inflow of Rs 18.33 crore in the prior-year period. The cash-flow statement recorded a Rs 20.13 crore change in trade and other receivables and a Rs 16.48 crore change in trade and other payables. Net financing cash flow was an inflow of Rs 20.20 crore, against an outflow of Rs 5.89 crore a year earlier.
What is Generic Engineering's response to the auditor's concern?
Generic Engineering estimated the impact of the qualification at nil, saying it had obtained engineering completion certificates and valuations supporting the WIP’s existence. Management said it was confident the WIP would be realised as revenue within one year and accordingly did not anticipate an impact from the qualification. The filing does not provide a project-level schedule or a quantified WIP amount to support the one-year realisation expectation.
The auditor did not conclude that management’s nil estimate was incorrect. Instead, it said that certificates and valuations did not provide sufficient audit evidence on cost records, cost allocation and the calculation basis for WIP costs. This distinction means that management’s expectation of realisation within one year is a disclosed assessment, while the valuation effect on the September 2026 standalone figures remains unquantified by the auditor.
Generic Engineering also disclosed that the New Labour Codes became effective from November 21, 2025. Management said, based on its assessment and actuarial valuation, no material incremental impact arose on gratuity obligations in the September 2026 quarter. It continues to assess other areas, including the contract workforce, and said it will recognise any impact after relevant central and state rules and clarifications are issued.
Conclusion
The repeated qualification concerns the evidence supporting the valuation of Generic Engineering’s construction WIP rather than the existence of that WIP. The company reported September-quarter profit after tax of Rs 2.20 crore and six-month revenue from operations of Rs 115.05 crore, but the auditor could not calculate whether a WIP write-down or obsolescence provision would change those reported figures.
The next disclosed matter to watch is management’s plan to realise the WIP into revenue within one year. A subsequent filing could show whether Generic Engineering provides the cost records, allocation workings and cost-computation basis that Bilimoria Mehta & Co. said were missing, enabling an assessment of the WIP valuation and any required adjustment.